


TriNet Group (TNET) has rolled out a fresh wave of HR tools aimed at small and mid sized employers, integrating leave management, recruiting, spending control and AI assistance more tightly into its core platform.
The recent HR upgrades come as TriNet Group’s shares trade at US$75.78, with a 1 month share price return of 16.39% and a year to date share price return of 32.55%. Over a longer horizon, the 3 year total shareholder return has declined 24.01% and the 5 year total shareholder return has declined 21.77%, which indicates that momentum has picked up recently while longer term holders have experienced weaker outcomes.
Scan for other HR and automation companies showing fresh product momentum with our curated 39 profitable AI stocks that aren't just burning cash.
After a 32.55% year to date jump and with new HR tools hitting the market, is TriNet Group still offering a margin of safety for fresh buyers, or has the recent rerating already captured most of the upside potential?
Most Popular Narrative: 14% Overvalued
TriNet Group last closed at $75.78, while the most followed narrative pegs fair value at $66.20 using a 7.93% discount rate. That gap sets the stage for a story that leans on AI tools, new products and distribution reach to justify today’s higher price.
The increasing complexity of workforce regulations and compliance requirements is expected to drive higher demand for TriNet Group's outsourced HR services, which can support client retention and long term recurring revenue growth.
The acceleration in SMB adoption of remote and hybrid work models is pushing more businesses to seek flexible PEO solutions, which can expand TriNet Group's addressable market and lift customer acquisition and overall revenues.
See why 1 investors see TriNet Group as 14% overvalued.
Result: Fair Value of $66.20 (OVERVALUED)
Still, shrinking worksite employee volumes and persistently high health cost trends could pressure TriNet Group’s revenue base and squeeze margins if pricing cannot fully adjust.
Find out about the key risks to this TriNet Group narrative.
Another View: TriNet Group Through A Cash Flow Lens
The narrative crowd calls TriNet Group about 14% overvalued at $75.78 against a fair value of $66.20, using earnings assumptions and a 7.93% discount rate. The SWS DCF model tells a very different story. On that framework, TNET at $75.78 is trading at roughly a 61% discount to an estimated future cash flow value of $192.34, which frames the same price as materially undervalued instead of stretched.
That kind of gap between an earnings based fair value of $66.20 and a cash flow based estimate of $192.34 raises a practical question for investors. Is the market correctly fading longer term cash generation, or are earnings focused views underestimating what TriNet Group’s recurring HR platform and AI tools could throw off over time?
Look into how the SWS DCF model arrives at its fair value.
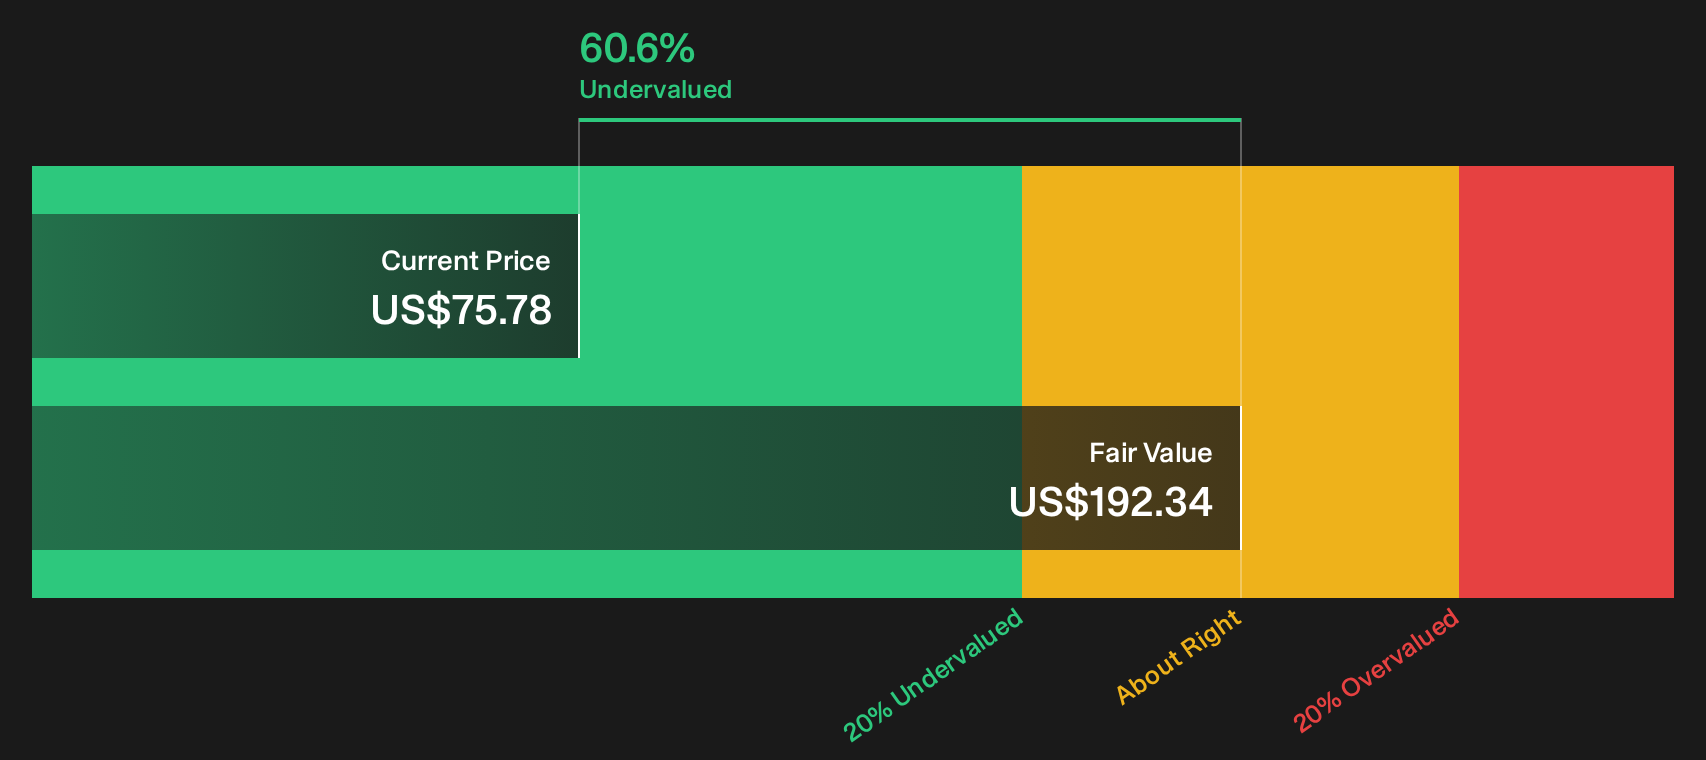
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out TriNet Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on TriNet Group and its fair value always create strong opinions. Move quickly, test the numbers yourself, and pressure test both sides of the story with the 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond TriNet Group?
If TriNet Group has you thinking harder about price versus potential, do not stop with a single ticker. Broader idea flow is where better portfolios often begin.
- Target powerful upside potential by scanning focused opportunities through the 21 high quality undiscovered gems.
- Prioritise resilience and sleep better at night by zeroing in on the 30 resilient stocks with low risk scores.
- Strengthen your core holdings with companies that pair sensible leverage and healthy cash metrics across the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com