


Energizer Holdings (ENR) has drawn fresh attention after recent share moves, with the stock closing at US$22.57. Investors are weighing modest recent gains against weaker multi year total returns and the company’s latest financial profile.
The recent 4.01% 7 day share price return and 7.27% 90 day gain suggest some momentum is building in Energizer Holdings, yet the 1 year total shareholder return declined 1.45% and the 5 year total shareholder return fell 23.44%, reminding investors that recent strength follows a weaker longer term record.
Scan beyond Energizer Holdings and compare its recent swings with a curated 29 high quality undervalued stocks that may offer stronger fundamentals at similar or more attractive valuations.
Energizer Holdings has bounced in the short term while longer term returns remain weak, which leaves a practical call for investors. Is this a reasonable entry point now, or does patience make more sense once price meets value?
Preferred Multiple of 19x: Is it justified?
Energizer Holdings looks slightly expensive on headlines, with a P/E ratio of 19x against the global Household Products industry average of 16.8x, even though the last close sits at $22.57 and recent returns have been subdued.
The P/E multiple compares what investors are currently paying for each dollar of Energizer Holdings earnings. For a mature consumer products group that sells batteries, auto care and lighting, that earnings based lens matters because cash generation and balance sheet risk tend to drive long term outcomes more than rapid top line expansion.
On one side, the stock is described as good value against its peer set, with the same 19x P/E below a 23.7x peer average. On the other, that valuation is called expensive against both the global Household Products industry on 16.8x and an estimated fair P/E of 18.9x, which implies the current ratio is very slightly above the level the market could move towards if pricing fully matched this modelled benchmark.
Put differently, the market is paying a premium to the broader industry but a discount to closer peers, and only a fractionally higher multiple than the fair ratio suggests. That mixed signal leaves Energizer Holdings looking only modestly rich on earnings, rather than clearly mispriced in either direction, and focuses attention on whether future profit growth and debt levels justify even a small premium to the fair P/E band.
Explore the SWS fair ratio for Energizer Holdings.
Result: Price-to-Earnings of 19x (ABOUT RIGHT)
Still, a weak 5 year shareholder return and a discount to a US$22 analyst price target could pressure sentiment if earnings momentum or balance sheet strength weaken.
Find out about the key risks to this Energizer Holdings narrative.
Another View: DCF Points to Deep Discount
The earnings multiple paints Energizer Holdings as only slightly expensive, yet the SWS DCF model pulls in a very different direction. On that lens, the stock at $22.57 is described as trading roughly 75% below an estimated future cash flow value of $90.29, which implies a very steep discount if those cash assumptions hold up.
When one framework says “about right” on earnings and another flags a big gap on cash flows, it raises a straightforward question. Which risk matters more for you: paying a bit above a fair ratio now, or relying on a long range cash flow path that may or may not materialise?
Look into how the SWS DCF model arrives at its fair value.
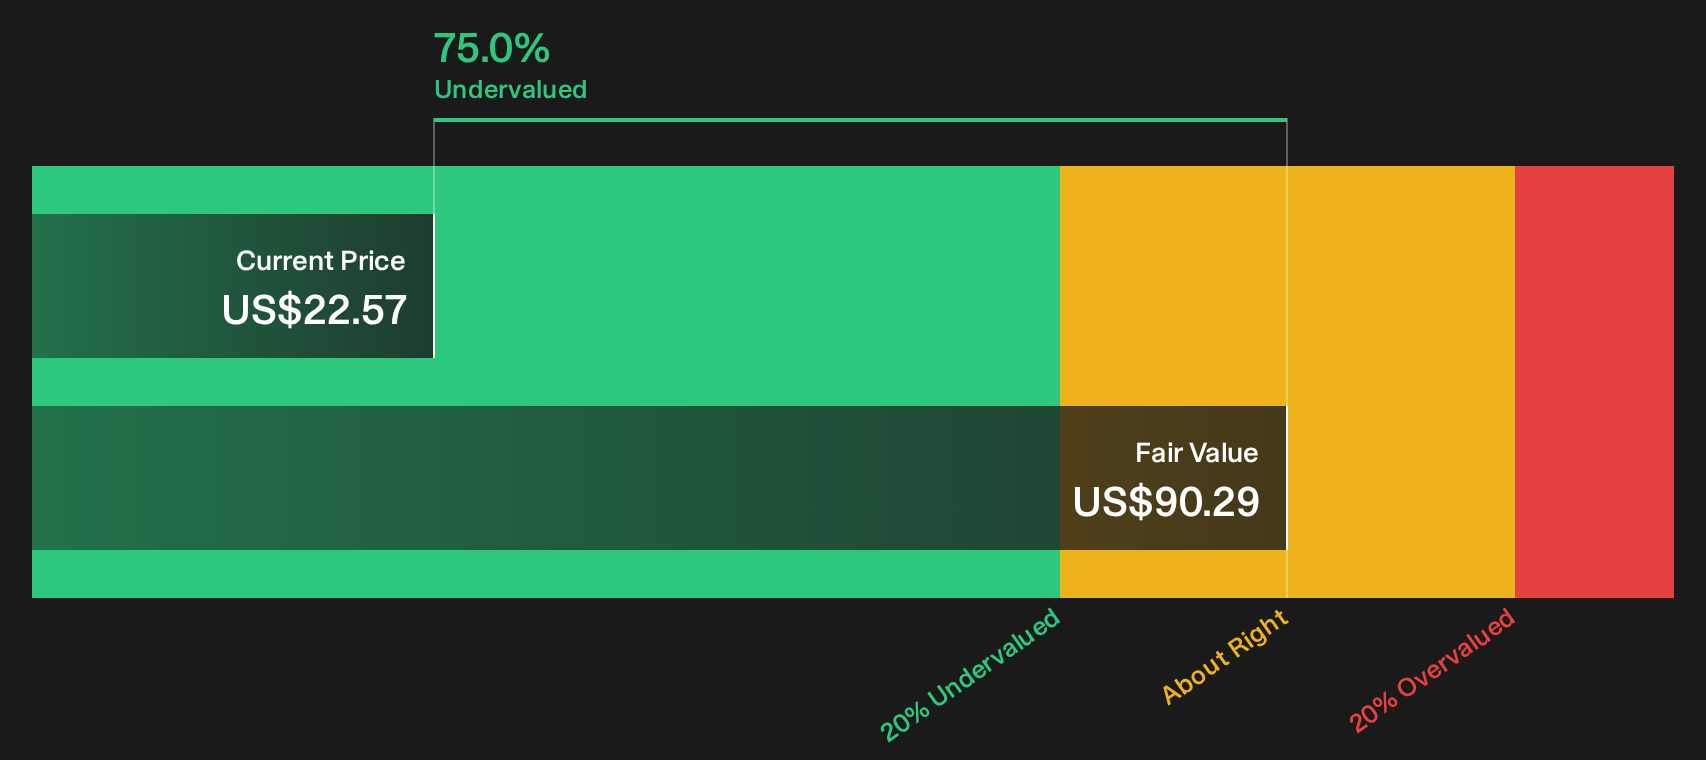
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Energizer Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Energizer Holdings can either be a warning sign or an opening. Act while the data is fresh and weigh both sides through 2 key rewards and 4 important warning signs
Looking for more investment ideas beyond Energizer Holdings?
Do not stop your research with Energizer Holdings. Use fresh stock ideas from the Simply Wall Street Screener to spot opportunities that might better fit your plan.
- Zero in on mispriced quality and scan a curated pool of undervalued opportunities through the 29 high quality undervalued stocks.
- Build a portfolio with staying power by focusing on companies that carry robust finances using the list of solid balance sheet and fundamentals (24 results).
- Hunt for future leaders early and sift through financially sound under the radar opportunities via the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com