


Paycom Software (PAYC) has drawn fresh attention after its recent share price move, with the stock closing at US$274.59 and posting double digit percentage gains over the past month and past 3 months.
That one month surge is not happening in isolation, since Paycom Software’s share price return of 24.55% over 30 days and 81.49% over 90 days sits alongside an 80.18% year to date share price return and a 38.93% 1 year total shareholder return. This suggests that momentum has been building as investors reassess both growth prospects and perceived risk.
Scan for other payroll and HR software players showing similar momentum by checking the curated list of 21 high quality undiscovered gems alongside Paycom Software's recent surge.
After a move like Paycom Software’s, investors usually split into two camps. Is this the early stage of a rerating, or has most of the upside already been priced in as the valuation now stands?
Most Popular Narrative: 23% Overvalued
On the most followed view of Paycom Software, the fair value sits at $222.59 compared with the latest close of $274.59. This points to a meaningful valuation gap that investors now need to explain through growth, margins and capital returns.
Ongoing automation and AI driven product development across Paycom Software's single database HCM suite, including tools such as Beti and GONE that management links to reduced manual processing and higher client satisfaction, continues to support strong revenue retention and operational efficiencies that can sustain EBITDA margin strength and earnings power.
See why 82 investors see Paycom Software as 23% overvalued.
Result: Fair Value of $222.59 (OVERVALUED)
Still, the bullish Paycom Software narrative leans heavily on IWant remaining differentiated and on data center investments delivering lasting cost savings rather than adding new expense pressure.
Find out about the key risks to this Paycom Software narrative.
Another View: Our DCF Says Paycom Software Looks Cheap
The analyst narrative frames Paycom Software as 23% overvalued against a fair value of $222.59, yet the Simply Wall St DCF model points in the opposite direction. On that cash flow view, PAYC at $274.59 trades about 51% below an estimated value of $561.12, which presents a different perspective on risk and potential reward. This raises the question of which lens to rely on more: the earnings multiple or the long term cash generation.
Readers who want to see how this cash flow view is built number by number can review the full model and then decide which assumptions feel realistic for Paycom Software and which do not. Look into how the SWS DCF model arrives at its fair value.
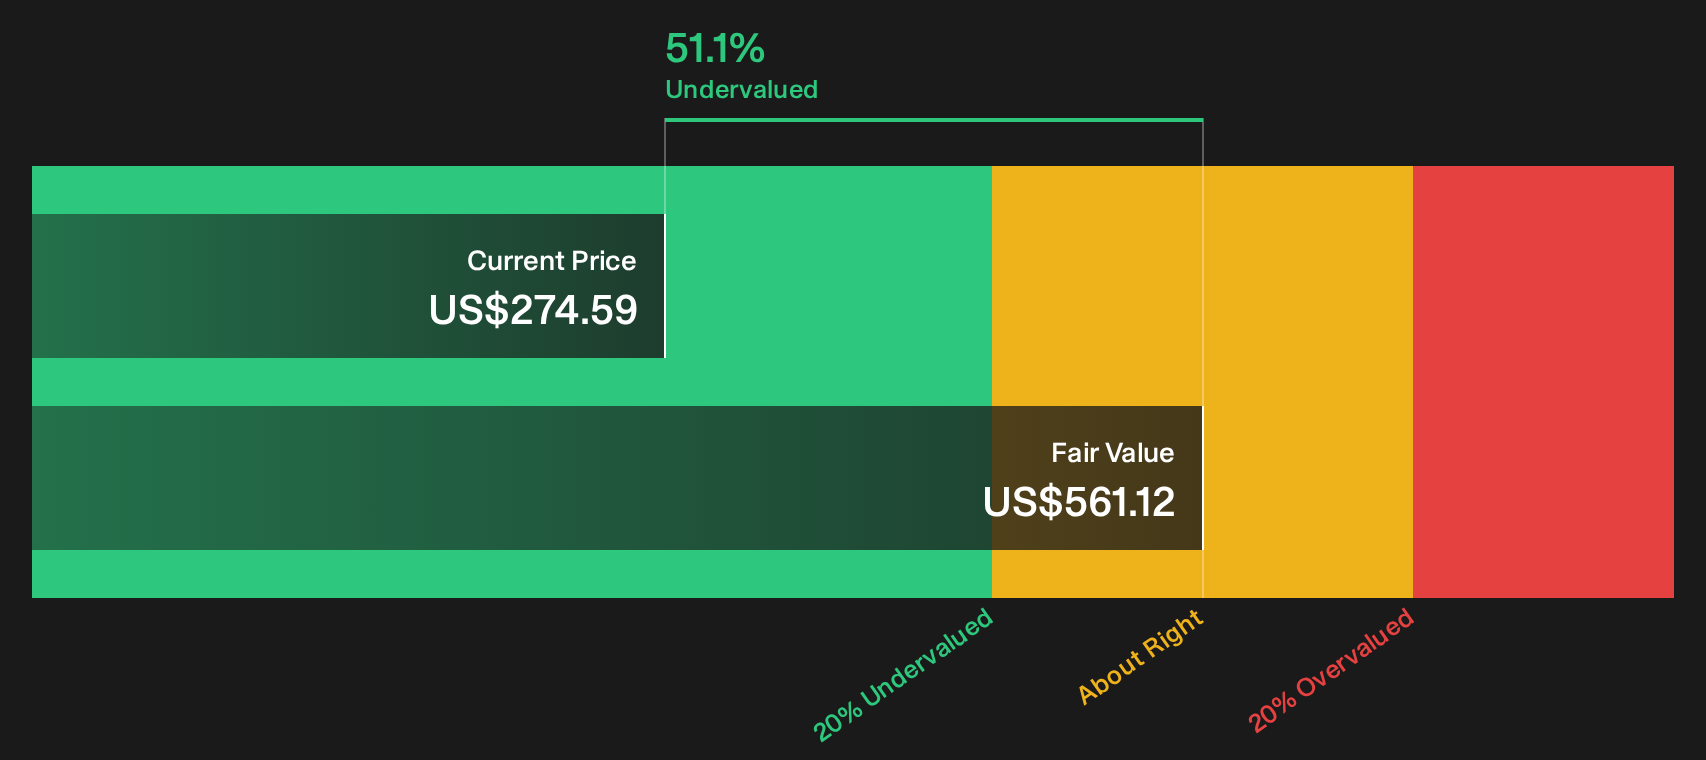
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Paycom Software for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Paycom Software’s value story so far. Take a close look at the numbers and sentiment yourself, then weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Paycom Software?
If Paycom Software has your attention, do not stop here. Use the broader universe of stocks to test your thesis, compare quality and pressure test your watchlist.
Cast a wider net across resilient businesses by reviewing a 30 resilient stocks with low risk scores that already screen well on risk factors and balance sheet strength.
Target potential mispricings by scanning a 29 high quality undervalued stocks that combine solid fundamentals with share prices that trail underlying metrics.
Build a more income focused watchlist by checking a 5 dividend fortresses that offer higher yields alongside stability characteristics many investors look for.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com