


BeOne Medicines (ONC) is back in focus after new survival findings from the Phase 3 HERIZON-GEA-01 study at ESMO 2026 positioned TEVIMBRA plus ZIIHERA and chemotherapy as a potential first-line standard in HER2-positive gastroesophageal cancer.
Against that clinical backdrop, BeOne Medicines’ shares trade at US$377.63, with a 30 day share price return of 4.65% and a 90 day gain of 15.87% that has gathered pace around the October ESMO updates, while a 3 year total shareholder return of about 121.55% points to strong longer run momentum.
Scan how BeOne Medicines fits alongside other oncology-focused opportunities by reviewing the hand-picked 34 healthcare AI stocks that tie cutting-edge cancer research to listed equities.
BeOne Medicines now looks like a heavyweight in oncology after the ESMO lift, yet the share price already reflects a long list of successes. Are investors paying a fair price for that strength today?
Most Popular Narrative: 13% Undervalued
BeOne Medicines is trading at $377.63 against a widely followed fair value narrative of about $433.02, which frames the current ESMO optimism against what analysts think the business is worth based on long term fundamentals.
BeOne's strong revenue growth (41% YoY in Q2; updated full-year guidance of $5 to $5.3b) is underpinned by rapid demand expansion for differentiated, best-in-class oncology therapies like BRUKINSA supported by a growing, aging population and increased global healthcare spending, both of which point to a sustainably expanding addressable market and future revenue growth.
See why 20 investors see BeOne Medicines as 13% undervalued.
Result: Fair Value of $433.02 (UNDERVALUED)
Still, BeOne Medicines leans heavily on BRUKINSA and the CLL franchise, and any clinical or regulatory setback there could quickly challenge this undervaluation story.
Find out about the key risks to this BeOne Medicines narrative.
Another View On BeOne Medicines’ Valuation
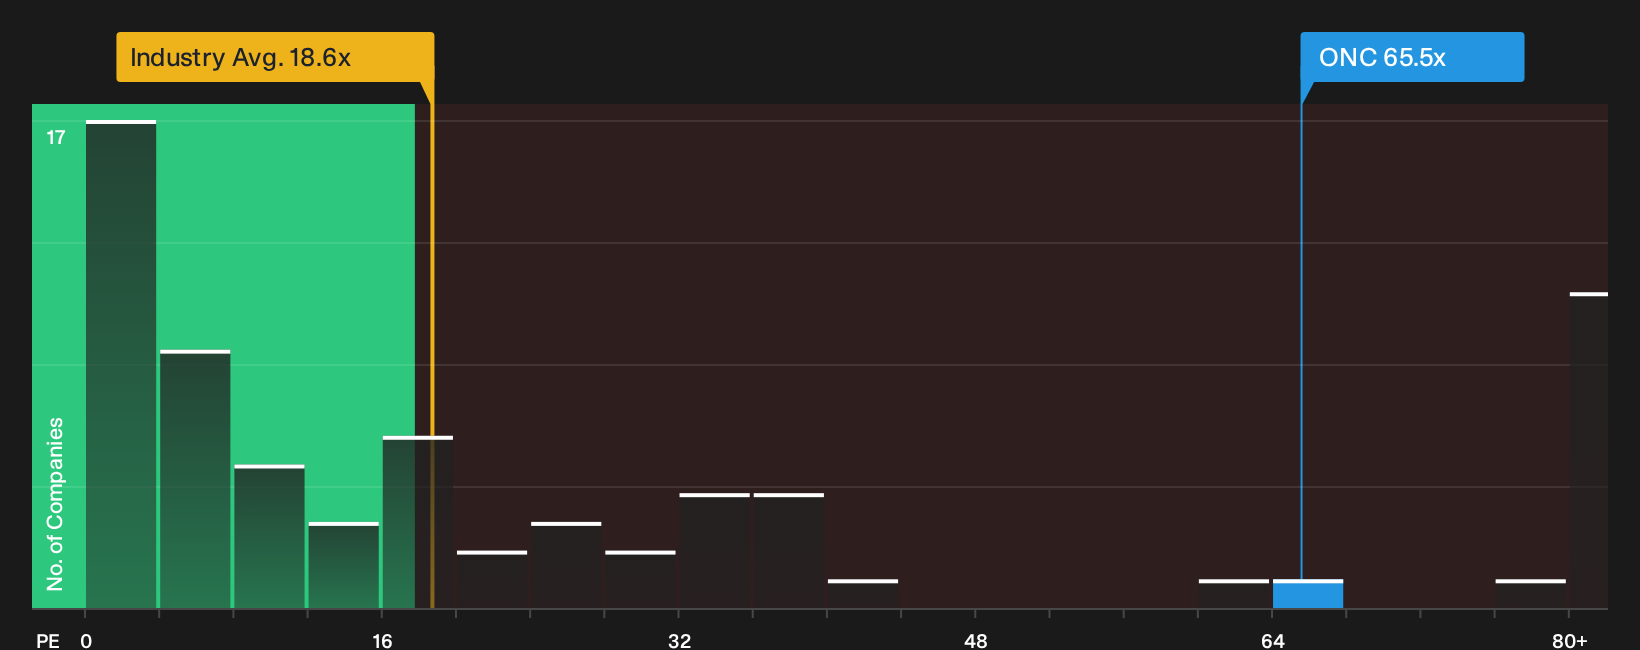
The popular fair value story paints BeOne Medicines as undervalued at $377.63 versus a $433.02 target. A simple earnings multiple tells a sharper story. The current P/E of 65.5x sits well above the fair ratio of 35.2x, the US Biotechs average of 18.6x, and a 29.2x peer group. That kind of gap can signal rich expectations, so the real question is whether you think the market drifts toward that fair ratio or stays comfortable paying a premium.
To see how those earnings multiples stack up against broader peers in more detail, take a look at See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Confident about the bullish tone running through this BeOne Medicines story, or think the optimism is overdone? Move quickly, review the underlying factors yourself, and then weigh those positives against the full breakdown of 3 key rewards.
Looking for more BeOne Medicines style ideas?
If BeOne Medicines has sharpened your focus on oncology and quality, do not stop there. Use a few targeted screens to surface your next candidates before others do.
- Target resilient balance sheets and steady fundamentals by filtering through a list of solid balance sheet and fundamentals (24 results).
- Hunt for quality at a reasonable price by scanning the 29 high quality undervalued stocks that match your return and risk preferences.
- Build a portfolio that pays you regularly by reviewing the 5 dividend fortresses with robust income potential.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com