


HPCL contract win puts Technip Energies in focus
Technip Energies (ENXTPA:TE) drew fresh investor attention after securing a large EPC contract from Hindustan Petroleum Corporation for key units in the Lube Modernization and Bottom Upgradation project at Mumbai Refinery.
Investors have reacted quickly to the HPCL win, with Technip Energies’ share price up 2.8% over the past day and recording a 7.1% 1 month share price return. At the same time, the year to date share price return is down 5.6% and the 1 year total shareholder return has declined 15.1%, while the 3 year total shareholder return is up 64.9%, highlighting stronger longer term gains alongside more mixed recent momentum.
Scan beyond Technip Energies and see which energy infrastructure contractors are also drawing fresh attention with a curated list of 42 power grid technology and infrastructure stocks
The HPCL contract has nudged Technip Energies’ share price higher, yet analyst targets and intrinsic estimates still sit materially above today’s €30.8 level. So where does fair value really look anchored now?
Most Popular Narrative: 22% Undervalued
On the most followed view, Technip Energies screens as materially undervalued, with a fair value of €39.44 against the latest €30.8 close. That gap rests on how its backlog, margins and cash generation play out from here.
Very strong recent order intake of €12.7b in the first half of 2026 and a record €25b backlog, around three times full year revenue, point to Technip Energies still having a large volume of LNG and energy infrastructure projects to execute. This can feed revenue and earnings over multiple years once converted.
See why 24 investors see Technip Energies as 22% undervalued.
Result: Fair Value of €39.44 (UNDERVALUED)
Still, Technip Energies’ story can break if Middle East disruption costs linger and higher corporate expenses or tax rates keep more cash from reaching shareholders.
Find out about the key risks to this Technip Energies narrative.
Another View: Technip Energies on earnings multiples
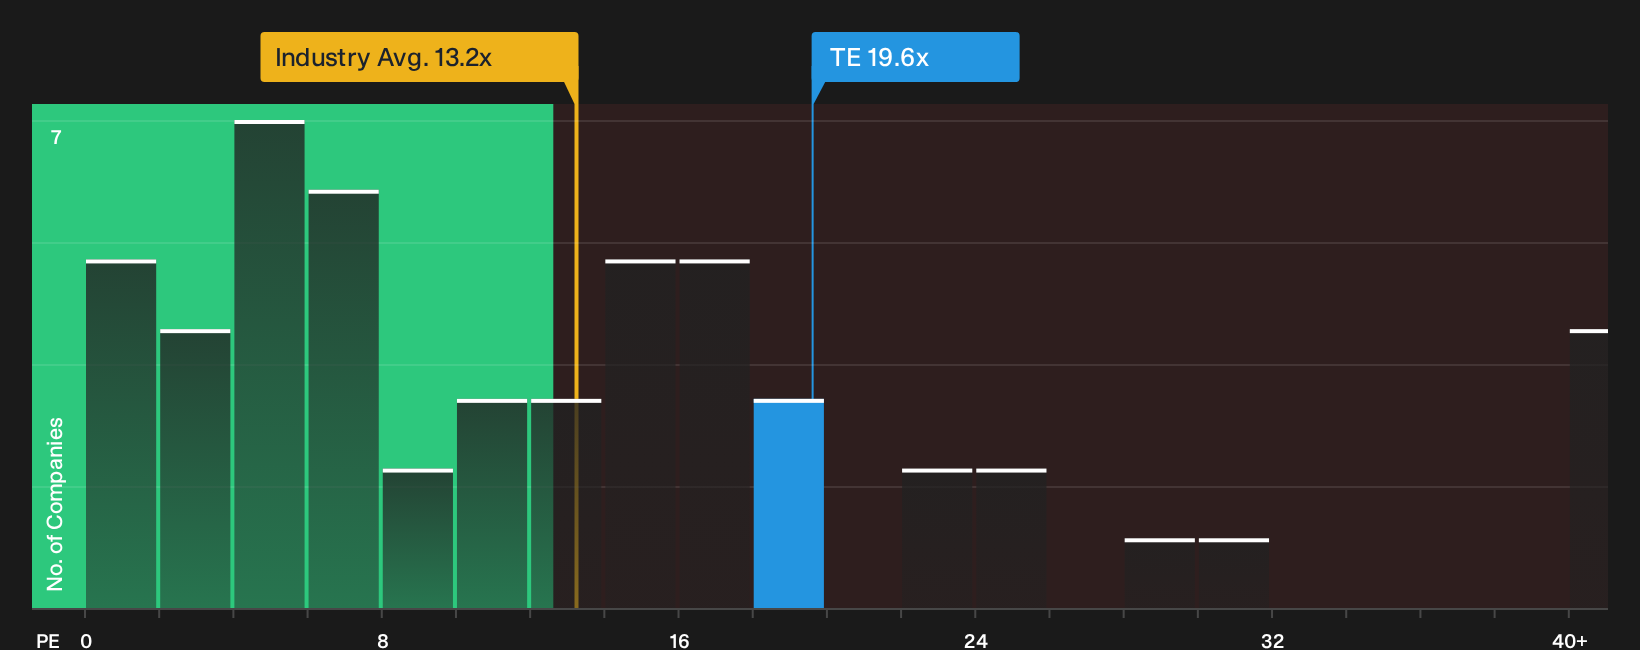
The discounted cash flow work and analyst fair value hint at upside, yet the simple earnings multiple presents a tougher picture. Technip Energies trades on a P/E of 19.6x, which is higher than both the European Energy Services group on 13.2x and its own fair ratio of 17.6x. That premium suggests less margin for error on execution and profit recovery if sentiment turns again.
For a closer look at how this pricing gap compares with the underlying numbers, and where the market could move if it leans toward the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of upside and concern around Technip Energies leaves you undecided, act promptly and test the thesis against the full picture. Balance the early signals by weighing the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Technip Energies?
Consider expanding your watchlist with tools that help surface companies by quality, resilience and income potential.
- Explore potential mispricings by scanning a curated pool of companies that screen as quality yet may be overlooked through the 194 high quality undervalued stocks.
- Support your capital base by finding businesses that pair higher yields with staying power using the targeted 229 dividend fortresses.
- Reduce portfolio stress and focus on durability by filtering for companies that pass a strict resilience check via the 221 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com