


EastGroup Properties (EGP) put acquisitions at the center of its latest update, increasing its 2026 acquisitions guidance to US$360 million and arranging US$485 million in forward equity to support that pipeline.
These acquisition plans land after a strong run in the stock, with EastGroup Properties showing a year to date share price return of 10.63% and a 1 year total shareholder return of 15.00%. However, the 90 day share price return is down 5.31%, hinting that shorter term momentum has cooled even as longer term performance remains positive.
Spot opportunities similar to EastGroup Properties' acquisition driven story by scanning our hand picked list of solid balance sheet and fundamentals (24 results) that may be positioned to deploy capital with comparable financial flexibility.Fresh guidance, a softer 90 day share move and a US$199.02 share price put EastGroup Properties at an interesting crossroads. Does the current valuation already reflect that acquisition push, or is patience the better call?
Most Popular Narrative: 13% Undervalued
On the most followed view of EastGroup Properties, a fair value of $227.90 sits above the recent $199.02 share price. This puts real weight on how the development and acquisition playbook is executed from here.
The main factor that needs to go right is that EastGroup Properties continues to execute on its development-led growth plan, including expanding its 2026 development and acquisition programs while keeping the balance sheet conservative and leasing velocity healthy across its markets.
The numbers imply the share price treats EastGroup Properties as still having meaningful upside if the company continues to grow FFO per share in line with raised 2026 guidance and converts its development pipeline and infill land bank into higher NAV over time.
See why 7 investors see EastGroup Properties as 13% undervalued.
Result: Fair Value of $227.90 (UNDERVALUED)
Still, if rent spreads keep easing and West Coast softness persists, the upbeat EastGroup Properties story could look stretched compared with those fair value assumptions.
Find out about the key risks to this EastGroup Properties narrative.
Another View: Multiples Paint A Richer Picture For EastGroup Properties
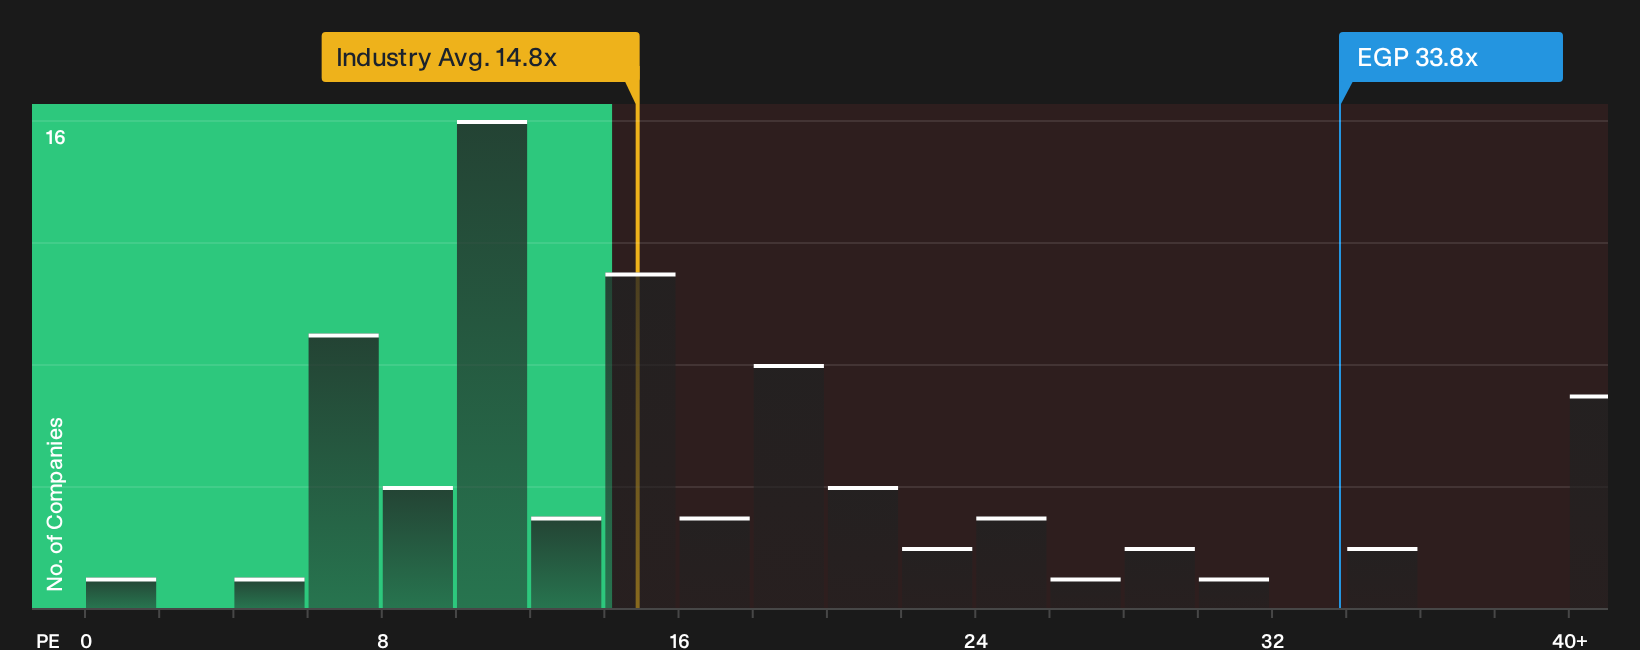
While the narrative fair value and DCF work suggest EastGroup Properties may trade below intrinsic value, the plain P/E math tells a tougher story. EGP changes hands at 33.8x earnings, versus 14.8x for the global Industrial REITs group and a fair ratio estimate of 32.6x. That richer tag narrows the margin for error and leaves you asking whether the premium is a cushion or a crack in the thesis.
For investors who prefer to anchor views on earnings based valuation, the next step is to see what the numbers imply for this price in more detail. You can do this in our valuation breakdown, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on EastGroup Properties so far. If you want to move quickly rather than rely on any single angle, consider both sides of the story by reviewing the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond EastGroup Properties?
If EastGroup Properties has you thinking about where capital can work hardest next, widen your lens with a few focused stock idea shortlists on Simply Wall St.
- Target potential mispricings by scanning a curated group of companies flagged as having strong fundamentals yet modest valuations through the 29 high quality undervalued stocks.
- Prioritize durability over drama and sort for businesses with healthier balance sheets and cleaner fundamentals using the list of solid balance sheet and fundamentals (24 results).
- Hunt for less crowded opportunities by reviewing a focused pool of under-followed stocks with solid metrics in the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com