


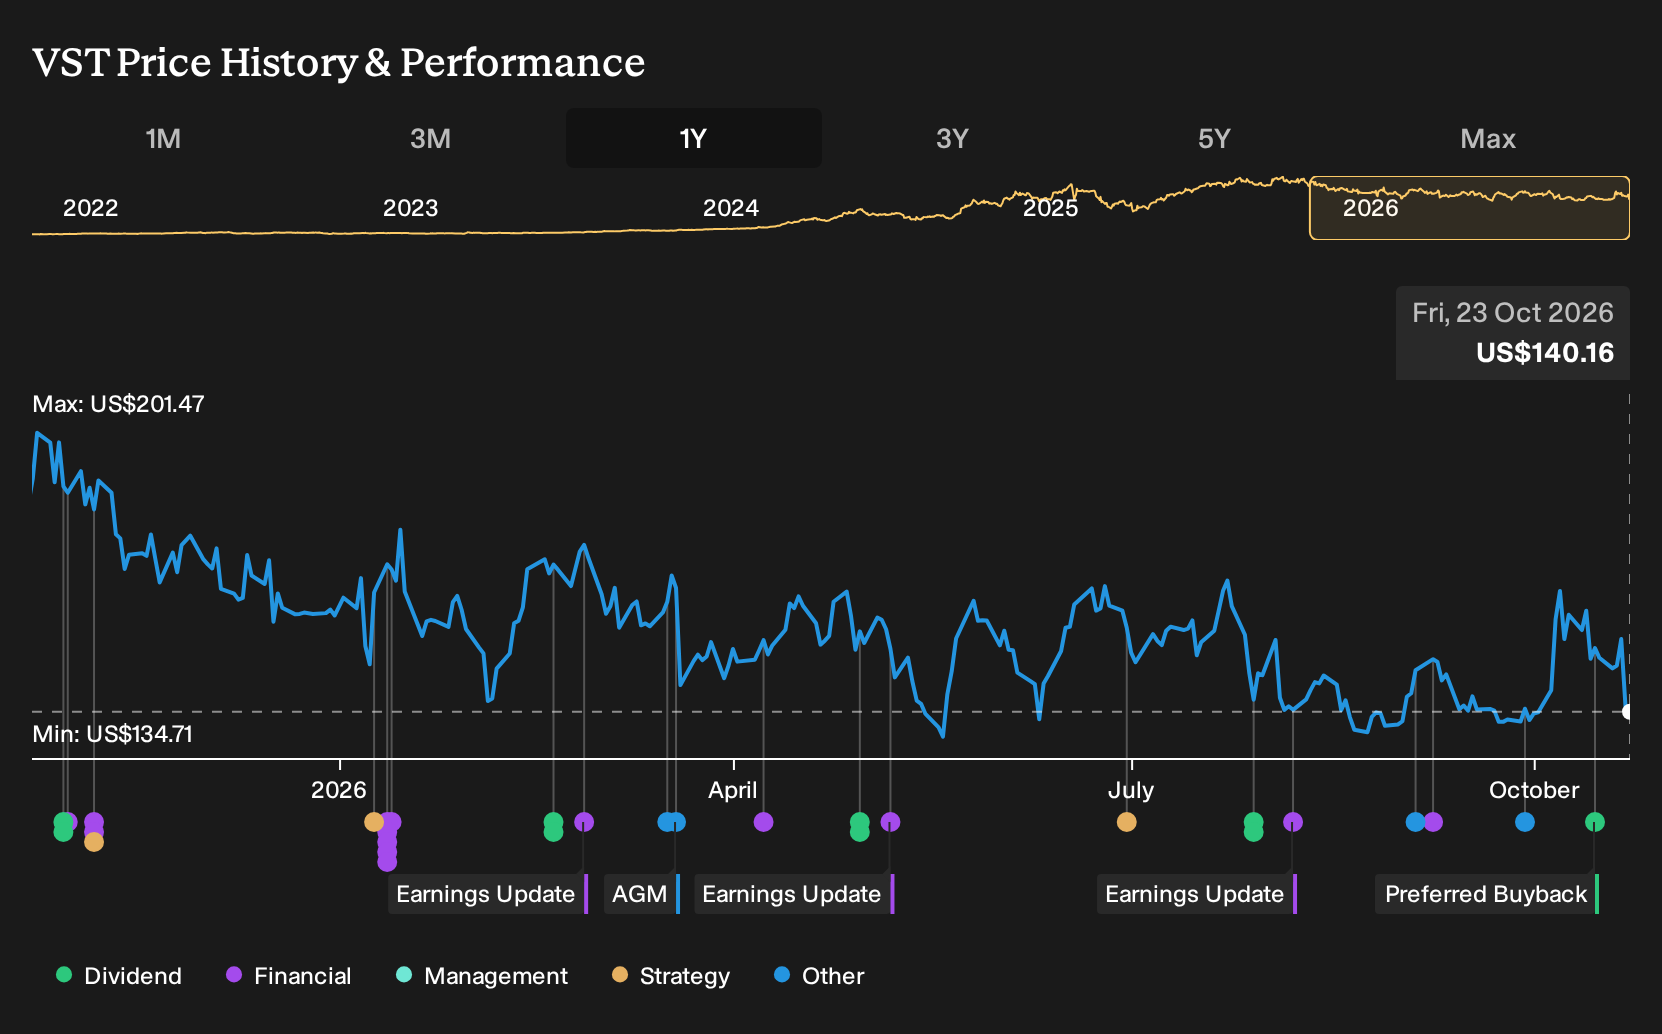
- Vistra Corp. has already redeemed all 1,000,000 shares of its 8.0% Series A preferred stock for US$1,000 per share, removing an 8.0% cumulative distribution layer and terminating all associated rights other than payment of the redemption amount.
- The retirement of this US$1.0b high-coupon preferred security frees up ongoing cash outflows that could be redirected toward debt repayment, common shareholder returns, or funding long-term nuclear power commitments to AI-driven data centers.
- We will now look at how redeeming high-cost preferreds may reshape Vistra's investment narrative around AI-linked power demand.
Scan beyond Vistra and this preferred stock redemption story to compare it with other power and grid plays tied to AI-driven demand using our hand-picked 42 power grid technology and infrastructure stocks.
Vistra Investment Narrative Recap
To own Vistra, you need to believe that long term electricity demand from AI linked data centers and broader load growth will support steady use of its 44,000 MW fleet and its mix of nuclear, gas, coal, solar and storage. The key near term swing factor is how quickly contracted AI and data center demand converts into actual volumes and cash receipts.
The biggest current operational risk is that soft wholesale prices in ERCOT and potential regulatory friction around data centers limit returns on new projects. The Series A preferred redemption mainly cleans up the capital stack. It does not materially change those core demand and pricing drivers in the short run.
The most relevant recent announcement alongside the preferred redemption is the conditional US$4.2b federal loan commitment for Vistra's nuclear uprates tied to 20 year contracts with Meta. That package anchors a significant portion of future output to a single hyperscaler and to AI data center power needs on defined terms.
For you, the link between those nuclear uprates and the preferred redemption is about funding flexibility and execution risk. The government loan, long dated PPAs and retired 8.0% preferred distributions together focus attention on Vistra's ability to deliver projects on time, manage high leverage and withstand swings in power prices while regulatory and mark to market risks remain in the background.
Vistra's current analyst blueprint points to revenues of US$26.0b and earnings of US$4.1b by 2029, based on forecast annual revenue growth of 10.7% and an earnings increase of about US$2.1b from US$2.0b today.
Uncover why Vistra's fair value indicates a 52% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You have an alternate script for Vistra that focuses on demand risk, not just capital costs. The most bearish analysts worry AI power needs disappoint and leave those 20 year contracts feeling heavy, so they model revenue at only US$19.7b and earnings of US$4.0b by 2029. That is far more cautious than consensus. Those forecasts were set before this preferred redemption, so you may want to ask how clearing an 8.0% layer could shift either story. Analyst opinions can differ widely, so explore both the upbeat and skeptical cases before deciding where you land.
Explore 13 other Vistra fair value estimates, including one that suggests as much as 7% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Vistra research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Vistra. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vistra's overall financial health at a glance.
Looking For More Investment Ideas Beyond Vistra?
If dissecting Vistra's AI power story has sharpened your thinking, you can apply that same lens to a broader watchlist using the Simply Wall St Screener to spot other companies that may fit your goals.
- For investors who care most about paying less for quality, scan for potential value opportunities using our 29 high quality undervalued stocks that combine fundamentals with pricing signals.
- If steady income is your priority, focus on companies offering meaningful cash returns through our curated set of 5 dividend fortresses that highlight higher-yield payouts.
- When resilience matters more than excitement, narrow the field to businesses with stronger balance sheets and lower risk profiles using the list of solid balance sheet and fundamentals (24 results) as your starting point.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com