


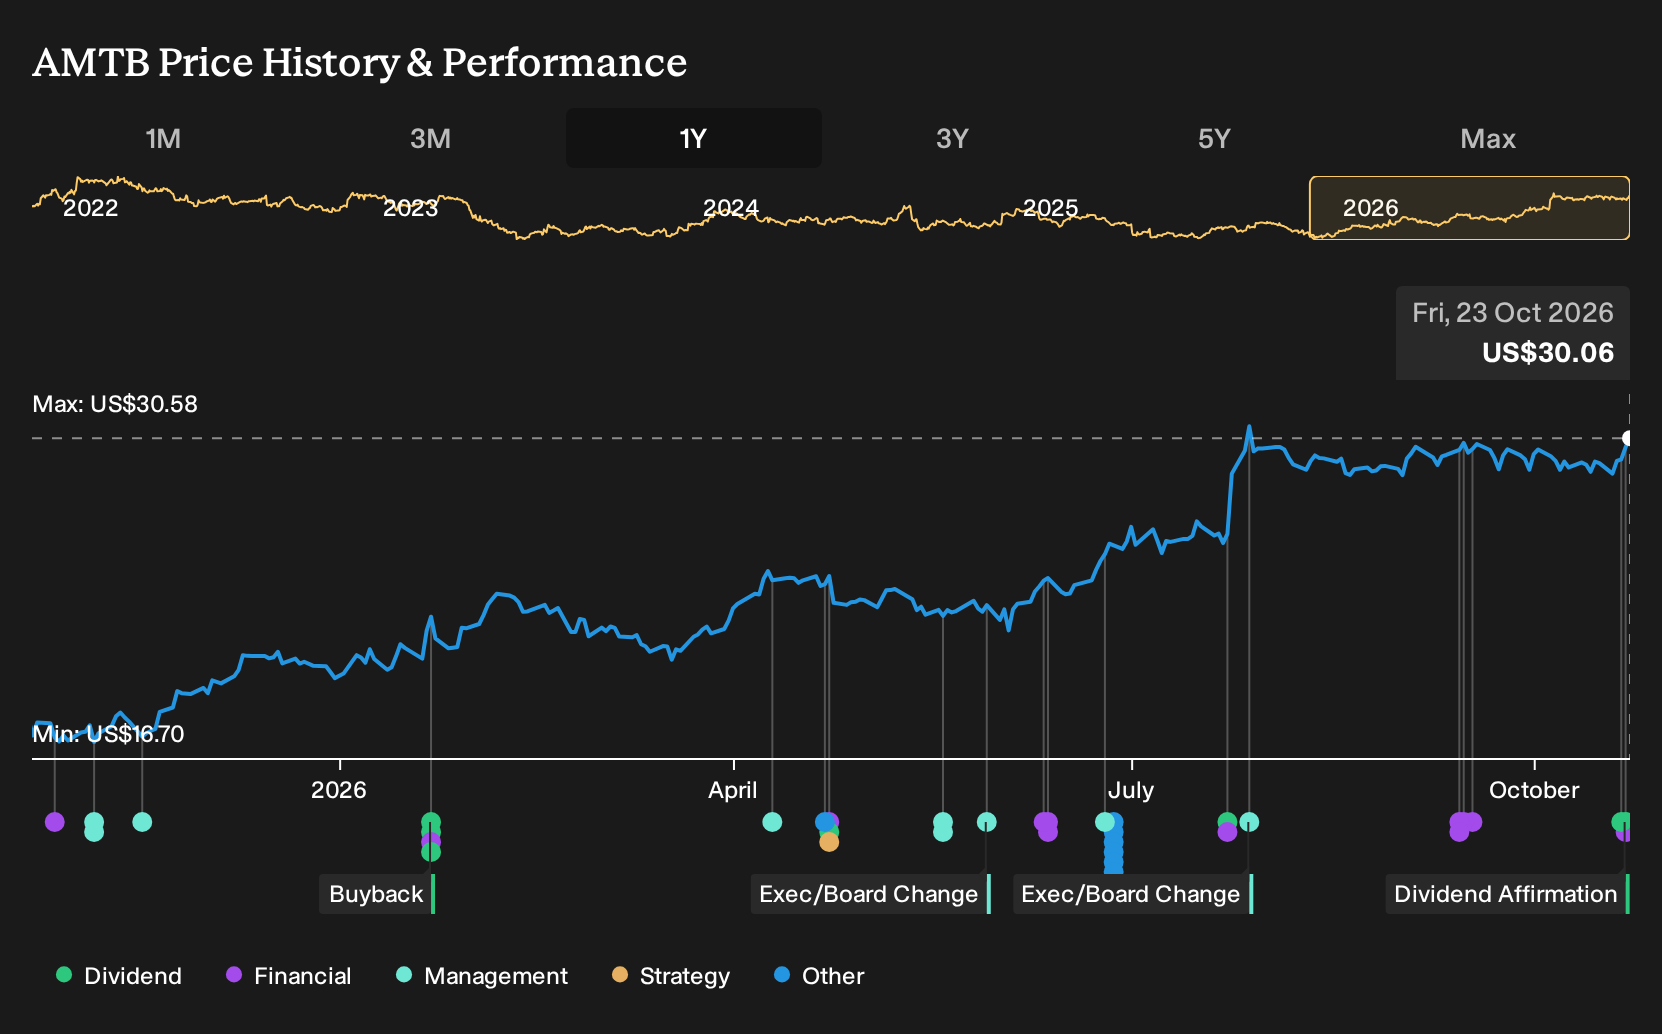
- Amerant Bancorp reported third quarter 2026 net income of US$25.72 million, with basic EPS from continuing operations of US$0.66, and declared a US$0.09 per share cash dividend payable on November 27, 2026 to shareholders of record on November 13, 2026.
- The bank paired higher profitability with active capital management, completing US$36.81 million of buybacks through September 2026 and then increasing remaining repurchase authority to US$50 million, with an extended plan through December 31, 2027.
- Next, the focus shifts to how Amerant Bancorp's reported third quarter profitability might influence the existing investment narrative around funding and capital returns.
Amerant Bancorp Investment Narrative Recap
For Amerant Bancorp, the core belief as a shareholder is that the bank can turn its funding mix, expense work and credit discipline into steadier profitability. The Q3 2026 earnings print, with higher net income and EPS, points to better execution, but the key near term catalyst still sits in credit costs and loan quality trends, not headline profit.
The biggest risk remains renewed credit stress or pressure on net interest income that erodes those earnings gains. The latest quarter does not fully remove that concern, although reported asset quality indicators improved. If credit provisions or funding costs flare up again, the recent profitability momentum could prove fragile.
The most relevant piece of recent news is the higher US$50 million buyback authorization running through the end of 2027. That sits alongside the maintained US$0.09 quarterly dividend and gives Amerant Bancorp multiple levers for capital returns while it works on funding and loan mix.
For you, the key question is how that capital plan interacts with catalysts around deposit growth, expense savings and fee income. Persistent risks around bad loans and a relatively low allowance mean execution on credit underwriting still matters more than headline repurchase capacity or short term share price reactions.
Amerant Bancorp's narrative projects US$477.8 million revenue and US$145.6 million earnings by 2029. This projection assumes 6.9% yearly revenue growth and an earnings increase of about US$89.2 million from US$56.4 million today.
Uncover why Amerant Bancorp's fair value indicates a 6% potential upside to its current price, which could narrow quickly if sentiment shifts toward Amerant Bancorp.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Amerant Bancorp research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Amerant Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Amerant Bancorp's overall financial health at a glance.
Looking For More Investment Ideas Beyond Amerant Bancorp?
After reviewing Amerant Bancorp, it can help to zoom out and compare it with other businesses that share similar traits around balance sheet strength, income potential and risk. The Simply Wall St Screener lets you filter by exactly those qualities so you can build a watchlist that matches your own comfort level and goals.
- If you care most about financial resilience, start with a curated list of solid balance sheet and fundamentals (24 results) that can help you focus on companies built on stronger footing.
- For investors who prioritize steadier income streams, use a hand picked 5 dividend fortresses to see which businesses currently offer higher yields with an emphasis on sustainability.
- When you want to look beyond the usual tickers, scan a targeted 21 high quality undiscovered gems that highlights quality fundamentals where market attention may still be limited.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com