


- Vertex Pharmaceuticals reported Phase 3 RAINIER data for povetacicept in IgA nephropathy, with a 52.0% proteinuria reduction at Week 36 and a 49.8% decrease versus placebo in a large, fully enrolled global trial.
- The company is advancing a patient focused IgAN program that pairs dual BAFF and APRIL inhibition with autoinjector dosing every 4 weeks and a dedicated Phase 3b experience study.
- We will now examine how Vertex Pharmaceuticals' IgAN proteinuria data and autoinjector plans could influence its broader renal investment narrative.
Vertex Pharmaceuticals Investment Narrative Recap
Vertex Pharmaceuticals asks you to believe that cystic fibrosis cash flows can support a much broader rare disease engine in renal, endocrinology, hematology, pain and diabetes. The RAINIER IgA nephropathy data and NEJM publication speak directly to that kidney ambition, while the key near term catalyst remains regulatory decisions on new drugs, including povetacicept.
The biggest operational risk still relates to concentration in cystic fibrosis and the added complexity from the Crinetics deal, which brings debt and integration work. The recent IgAN update does not change those risks but it does make execution in renal disease more visible, which could matter if CF pricing or volumes soften.
The most relevant recent announcement here is the advancement of povetacicept through the Phase 3 RAINIER program in IgA nephropathy, paired with the new PAVANT IgAN patient experience study using an autoinjector. That package turns Vertex Pharmaceuticals’ kidney effort from a slide in an investor deck into a live late stage program with device work built in.
Operationally, that matters because management has framed renal disease as part of a potential US$10 billion opportunity across four conditions, with RAINIER as one pillar and inaxaplin in APOL1 mediated kidney disease as another. The more cleanly Vertex executes on these renal trials and patient friendly delivery, the more diversified its earnings base could become relative to cystic fibrosis heavy revenue today.
Vertex Pharmaceuticals' current analyst narrative points to US$17.6b in revenue and US$6.3b in earnings by 2029, off a base of US$4.4b in earnings today and an assumed 11.7% yearly increase in revenue. This implies an earnings uplift of about US$1.9b over that period.
Uncover why Vertex Pharmaceuticals' fair value indicates a 9% potential upside to its current price that may not last much longer.
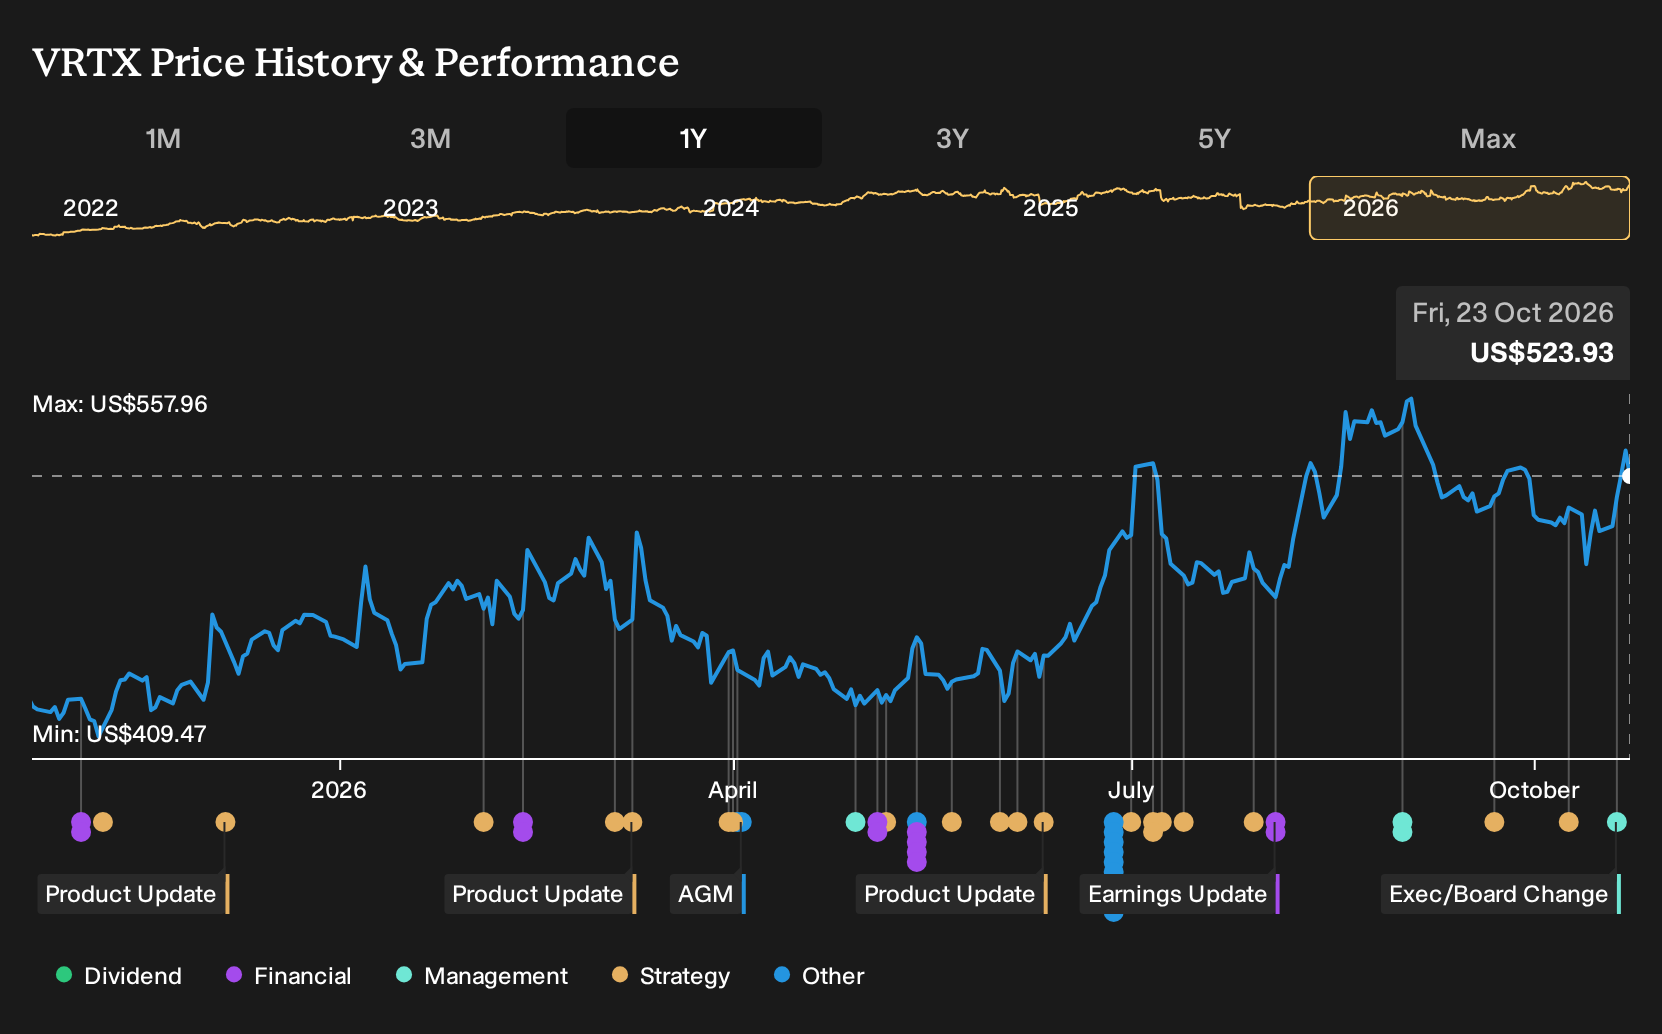
Exploring Other Perspectives
Some of the most optimistic analysts treat Vertex Pharmaceuticals’ renal push as the real swing factor. Their models from before this RAINIER update were already building in revenue of about US$19.1b and US$7.6b of earnings by 2029, far above consensus. Views like that may change as new IgAN data and device plans are absorbed.
Explore 4 other Vertex Pharmaceuticals fair value estimates, including one that suggests as much as 48% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Vertex Pharmaceuticals research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Vertex Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vertex Pharmaceuticals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Vertex Pharmaceuticals?
Once you have a view on Vertex Pharmaceuticals, it can help to pressure test that thinking against a wider watchlist built from other high quality opportunities. The Simply Wall St Screener lets you filter for traits that matter to you, whether that is balance sheet strength, consistency of returns, or quieter companies that are not yet widely followed.
- If resilience and lower perceived risk are a priority, start by scanning a 30 resilient stocks with low risk scores that may help you build a more stable watchlist around your higher conviction positions.
- If you care most about financial strength, broaden your research with a list of solid balance sheet and fundamentals (24 results) that can highlight businesses with room to invest through different market conditions.
- If you want to get ahead of the crowd, look through a 21 high quality undiscovered gems that focuses on quality fundamentals before they are widely talked about.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com