


As the UK market navigates the challenges posed by weak trade data from China, reflected in the recent declines of both the FTSE 100 and FTSE 250 indices, investors are increasingly looking for resilient growth opportunities. In such an environment, companies with high insider ownership can be particularly appealing as they often indicate strong internal confidence and alignment with shareholder interests.
Top 10 Growth Companies With High Insider Ownership In The United Kingdom
| Name | Insider Ownership | Earnings Growth |
| TPXimpact Holdings (AIM:TPX) | 19.5% | 106% |
| TEAM (AIM:TEAM) | 32% | 85.3% |
| Quantum Base Holdings (AIM:QUBE) | 31.8% | 111.8% |
| Mortgage Advice Bureau (Holdings) (LSE:MAB1) | 18.5% | 22.4% |
| Hochschild Mining (LSE:HOC) | 38.3% | 21.6% |
| Gulf Keystone Petroleum (LSE:GKP) | 12.6% | 21.1% |
| Energean (LSE:ENOG) | 19.3% | 32.8% |
| EARNZ (AIM:EARN) | 10.1% | 104.2% |
| Crimson Tide (AIM:TIDE) | 33% | 119.1% |
| Built Cybernetics (AIM:BUC) | 22.6% | 122.1% |
Let's dive into some prime choices out of the screener.
Kainos Group (LSE:KNOS)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Kainos Group plc provides information technology services across the United Kingdom, Ireland, North America, Central Europe, and other international markets with a market cap of £1.53 billion.
Operations: Kainos Group's revenue is primarily derived from Digital Services (£241.74 million), Workday Products (£81.75 million), and Workday Services (£107.61 million).
Insider Ownership: 20.3%
Kainos Group is positioned for growth with forecasted revenue and earnings increases of 11.6% and 15% annually, outpacing the UK market averages. Despite recent share price volatility, Kainos's Return on Equity is expected to be very high at 43.9% in three years. The company recently approved a final dividend of 19.8 pence per share, though its dividend history remains unstable. Revenue guidance for March 2027 suggests figures between £498 million and £514 million, surpassing expectations.
- Click here to discover the nuances of Kainos Group with our detailed analytical future growth report.
- The valuation report we've compiled suggests that Kainos Group's current price could be inflated.
Playtech (LSE:PTEC)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Playtech plc is a technology company that offers gambling software, services, content, and platform technologies with a market cap of £1.04 billion.
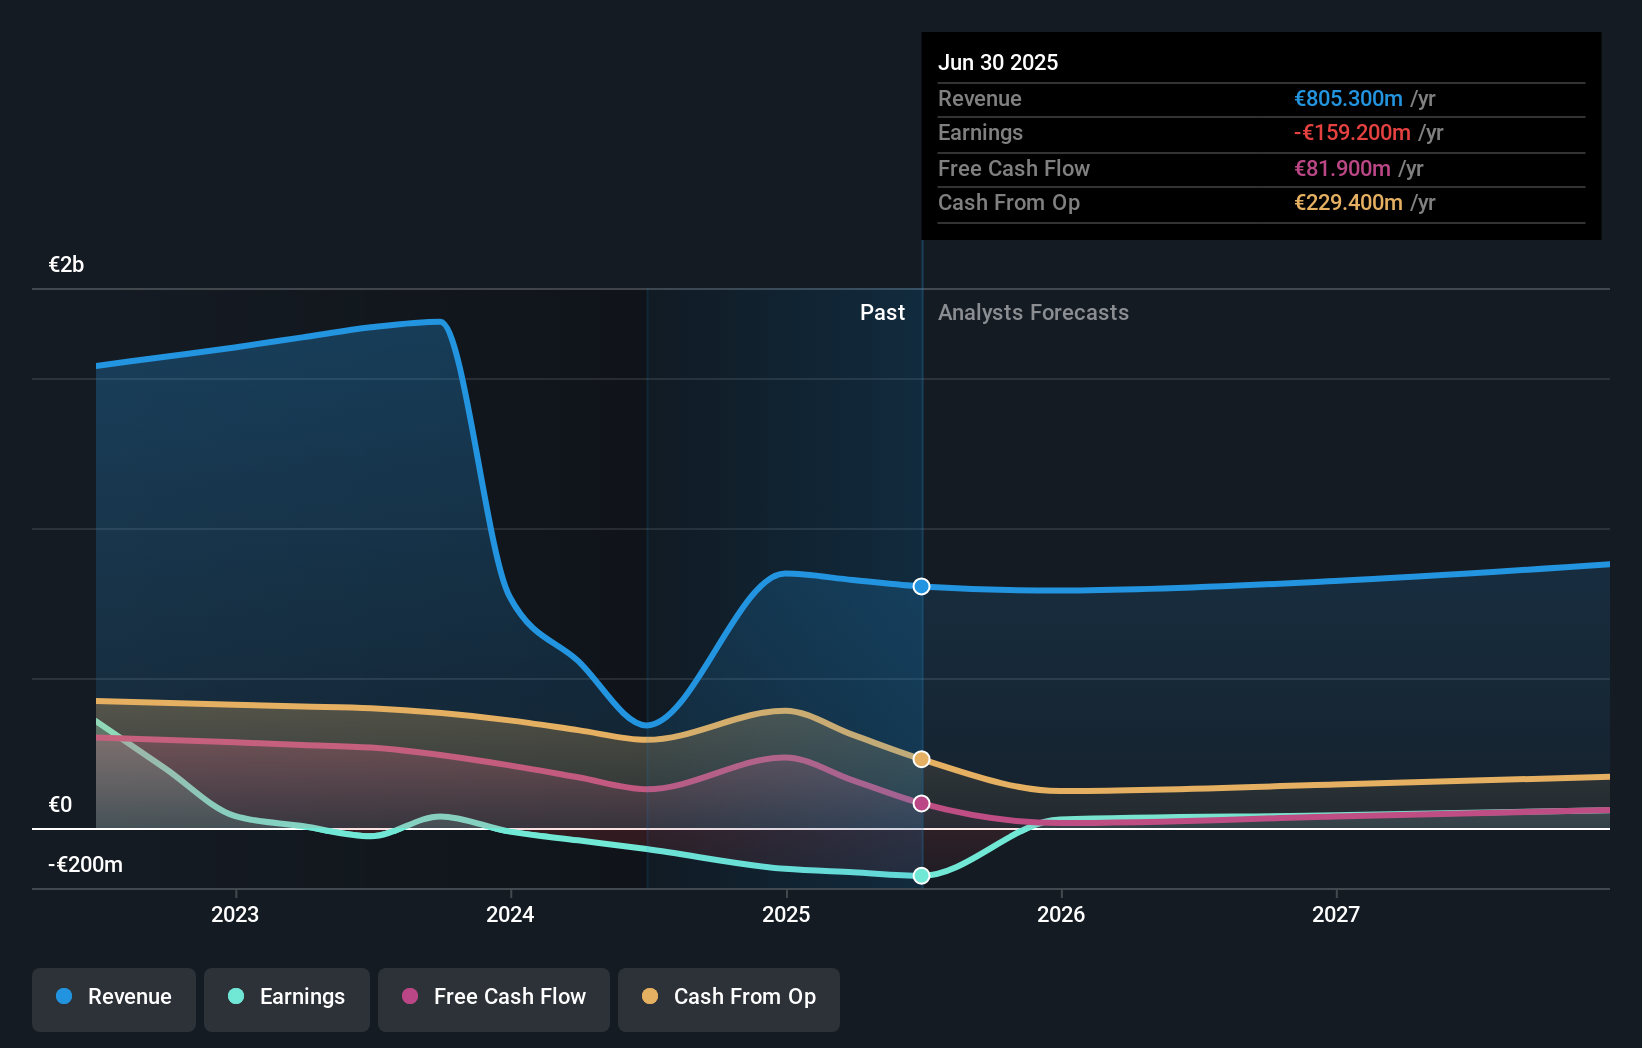
Operations: The company's revenue segments consist of B2B generating €735.50 million, HAPPYBET contributing €4.70 million, and Sun Bingo and Other B2C providing €64.80 million.
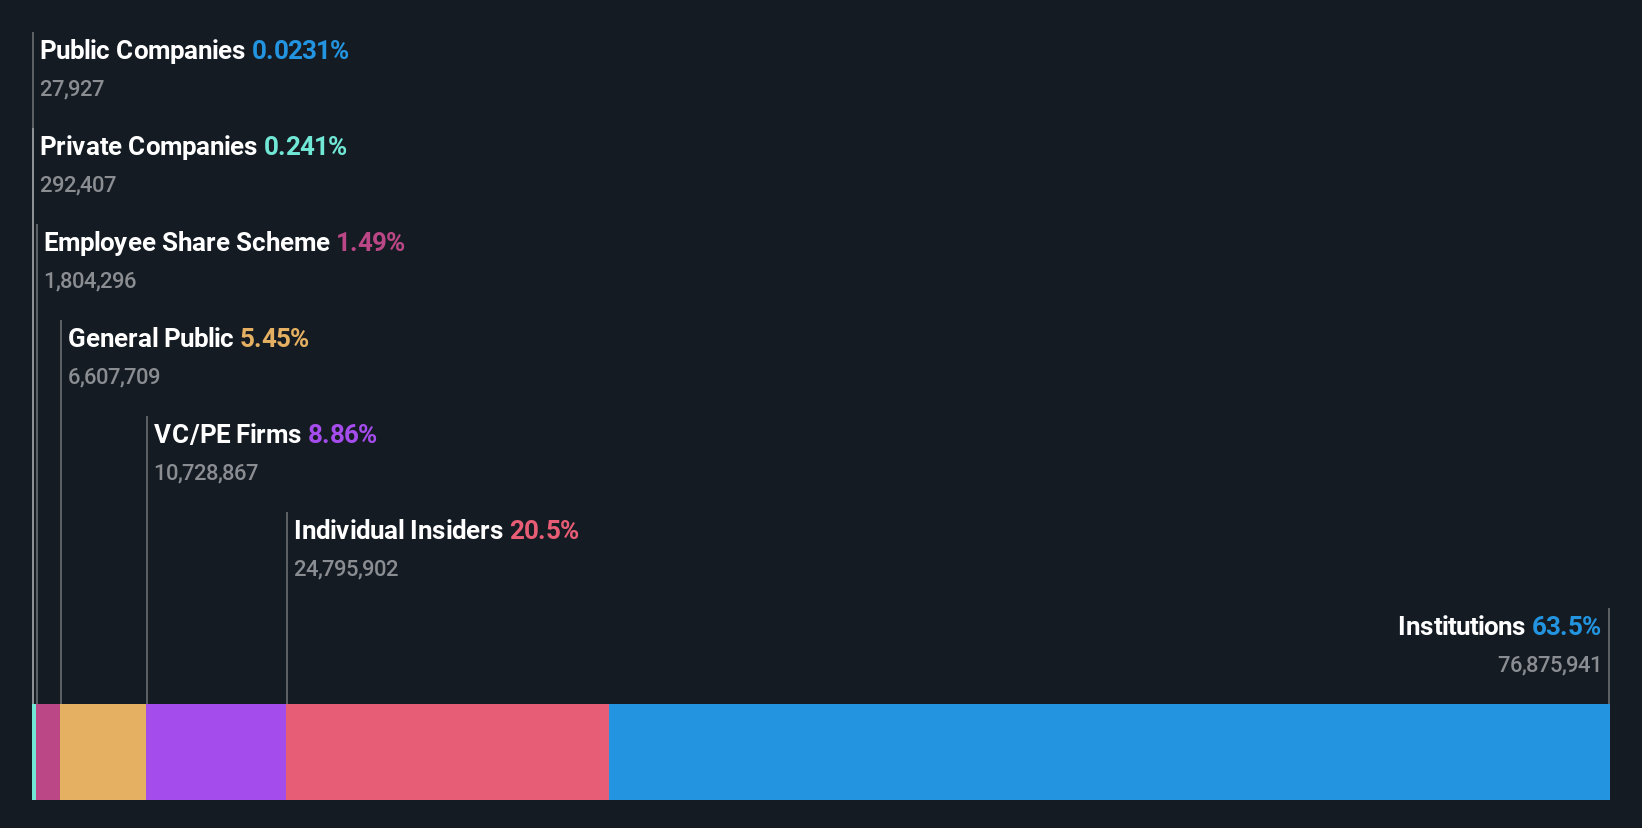
Insider Ownership: 10.8%
Playtech's growth potential is evident with earnings projected to rise significantly at 31.22% annually, outpacing the UK market. Despite slower revenue growth of 5.3%, it still exceeds the market average of 3.6%. Recent debt refinancing, replacing €300 million notes with €350 million ones at lower interest rates, strengthens its financial position. The company's strategic share buyback and a global distribution agreement with Gaming Corps AB further enhance its market presence and operational efficiency in regulated iGaming markets globally.
- Delve into the full analysis future growth report here for a deeper understanding of Playtech.
- Our valuation report unveils the possibility Playtech's shares may be trading at a premium.
TBC Bank Group (LSE:TBCG)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: TBC Bank Group PLC operates as a financial services provider offering banking, leasing, insurance, brokerage, and card processing services to both corporate and individual clients in Georgia, Azerbaijan, and Uzbekistan with a market capitalization of approximately £2.60 billion.
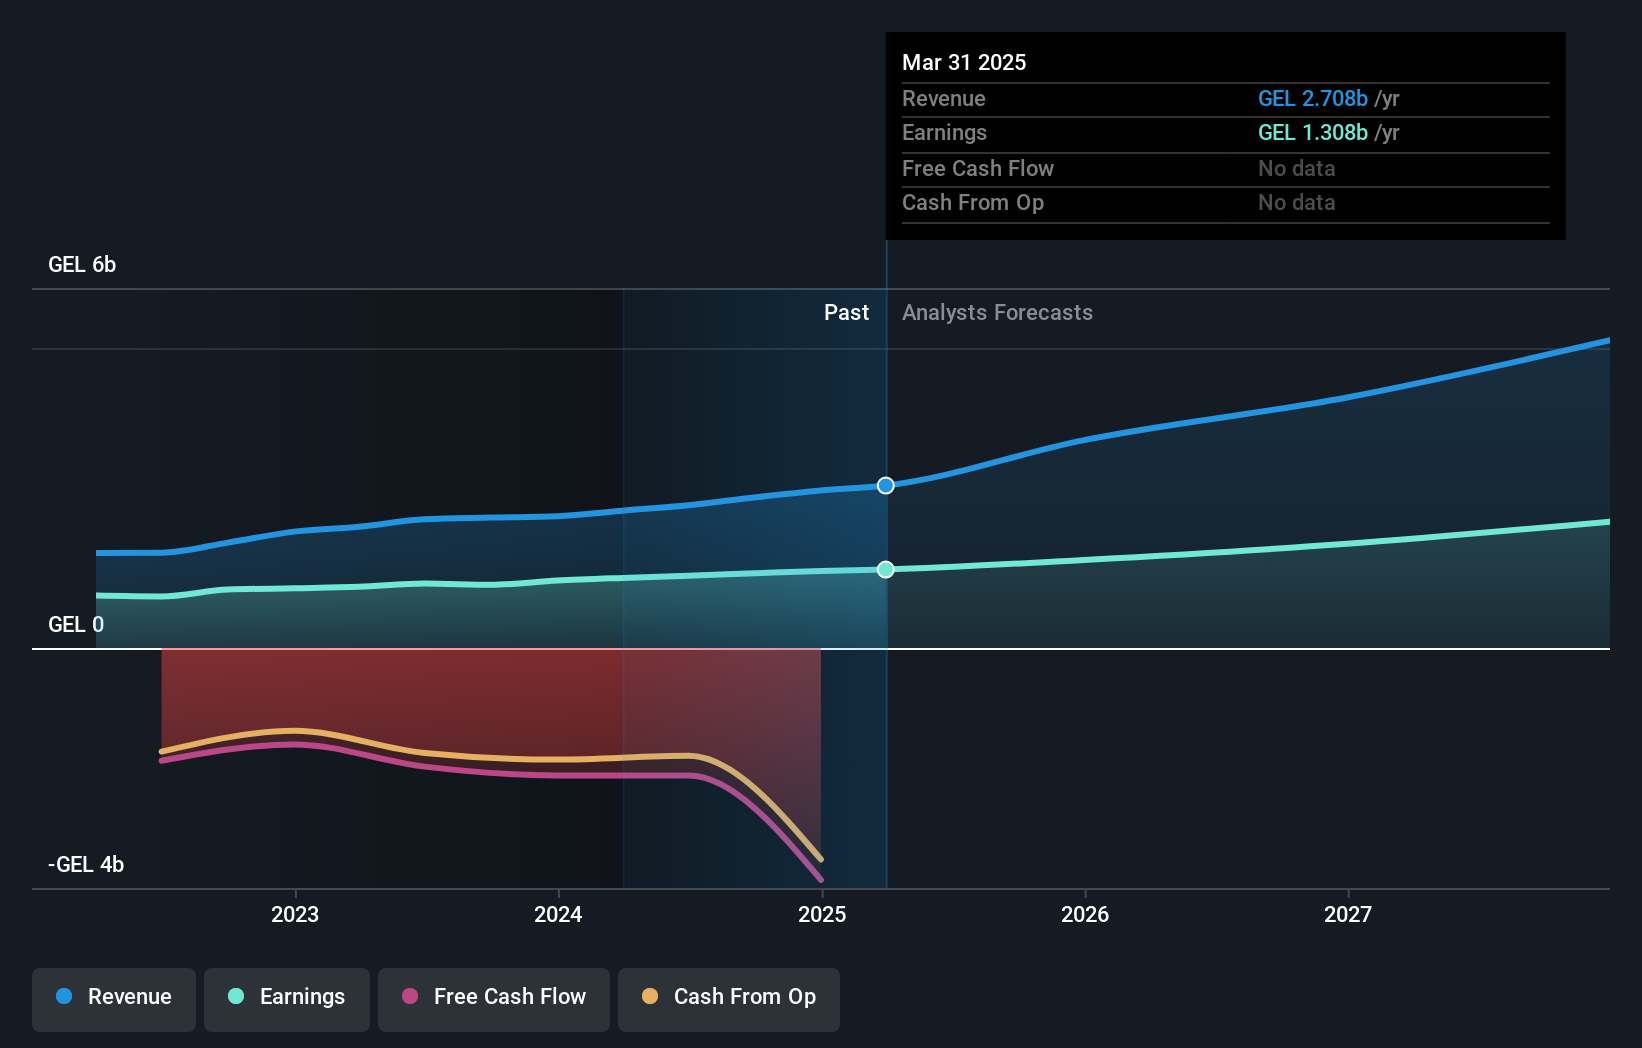
Operations: The company's revenue is primarily derived from Georgian Financial Services, contributing GEL 2.67 billion, and Uzbekistan Operations, which add GEL 431.62 million.
Insider Ownership: 18.1%
TBC Bank Group demonstrates strong growth potential with its revenue forecasted to grow at 18.6% annually, surpassing the UK market average. Despite a high level of bad loans (3.3%), the company trades at 59.6% below estimated fair value, offering good relative value compared to peers. Recent earnings reports show net income increasing from GEL 657.41 million to GEL 741.75 million year-over-year, indicating robust financial performance amidst challenging loan conditions.
- Dive into the specifics of TBC Bank Group here with our thorough growth forecast report.
- The analysis detailed in our TBC Bank Group valuation report hints at an deflated share price compared to its estimated value.
Turning Ideas Into Actions
- Delve into our full catalog of 66 Fast Growing UK Companies With High Insider Ownership here.
- Curious About Other Options? This technology could replace computers: discover the 25 stocks are working to make quantum computing a reality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com