


- Williams-Sonoma, through Pottery Barn Kids and Pottery Barn Teen, recently rolled out ten collaboration-led holiday collections with major entertainment and fashion partners, plus new age based digital gift guides aimed at capturing gifting demand across baby, kids, teen, and dorm categories.
- The expanded line up of exclusive licensed products signals a push to deepen holiday engagement, using recognizable franchises and curated online tools to keep customers inside Williams-Sonoma’s ecosystem rather than losing those purchases to generalist retailers.
- Attention now turns to how Williams-Sonoma’s investment narrative may shift as these collaboration-heavy holiday collections test the strength of its digital-first model.
Williams-Sonoma Investment Narrative Recap
To stay comfortable owning Williams-Sonoma, you need to believe its digital-first model, strong brands, and B2B channels can keep pulling in customers even when the housing market stays soft and tariffs or fuel costs squeeze merchandise margins. The short term swing factor is still demand for home furnishings, where weak housing conditions can cap big ticket spending.
The new collaboration heavy holiday launches and age based gift guides matter mainly at the margin. They support seasonal traffic and help keep shoppers inside the Williams-Sonoma ecosystem, but do not change the key risk around prolonged cost pressure or a sluggish housing backdrop that could weigh on comparable sales and profit levels.
The most directly relevant update is the rollout of ten licensed holiday collections at Pottery Barn Kids and Pottery Barn Teen, paired with AI supported, curated digital gift guides. This sits squarely on the core thesis that higher engagement online, through tools like Olive and Otto, can lift conversion and protect margins in a slow category.
Holiday collaborations also intersect with the main risk. If housing related demand stays muted and freight or tariff costs remain elevated, seasonal lifts from Pokémon or Harry Potter bedding will help but not fully offset pressure on larger furniture or decor baskets. The real test is whether this kind of merchandising keeps Williams-Sonoma winning share in a market that is described as flat to down.
Williams-Sonoma Forecasts and What They Assume
Analysts are effectively sketching out a Williams-Sonoma that leans on its digital tools and collaborations to support steady progress rather than a dramatic reset. The revenue line is modeled to rise by 5.4% a year over the next three years, which sets the backdrop for how much earnings and valuation are being asked to carry.
On profits, the consensus expects current earnings of about US$1.2b to move to US$1.3b by 2029, with margins drifting from 14.7% today to 14.0% in three years. That implies an earnings increase of roughly US$100m over the forecast window, even with some margin compression built into the model.
The share count is expected to shrink by 1.34% a year over the next three years, which can support earnings per share even if operating profit grows more slowly. At the same time, the framework uses a discount rate around 8.3% and assumes investors are willing to assign a higher P/E on those 2029 earnings compared with both Williams-Sonoma’s current multiple and the broader US specialty retail group.
Putting the pieces together, the consensus narrative leans on a mix of modest top line expansion, some pressure on profitability, and support from buybacks. It treats the digital ecosystem, B2B growth, and emerging brands as the tools that could help Williams-Sonoma achieve those incremental gains rather than as levers for a step change in performance.
Williams-Sonoma's outlook includes an analyst view that revenues could reach US$9.4b with earnings of US$1.3b by 2029, based on a 5.4% yearly revenue growth assumption and an earnings increase of about US$100m from current earnings of roughly US$1.2b.
Uncover why Williams-Sonoma's fair value is viewed as roughly in line with its current price.
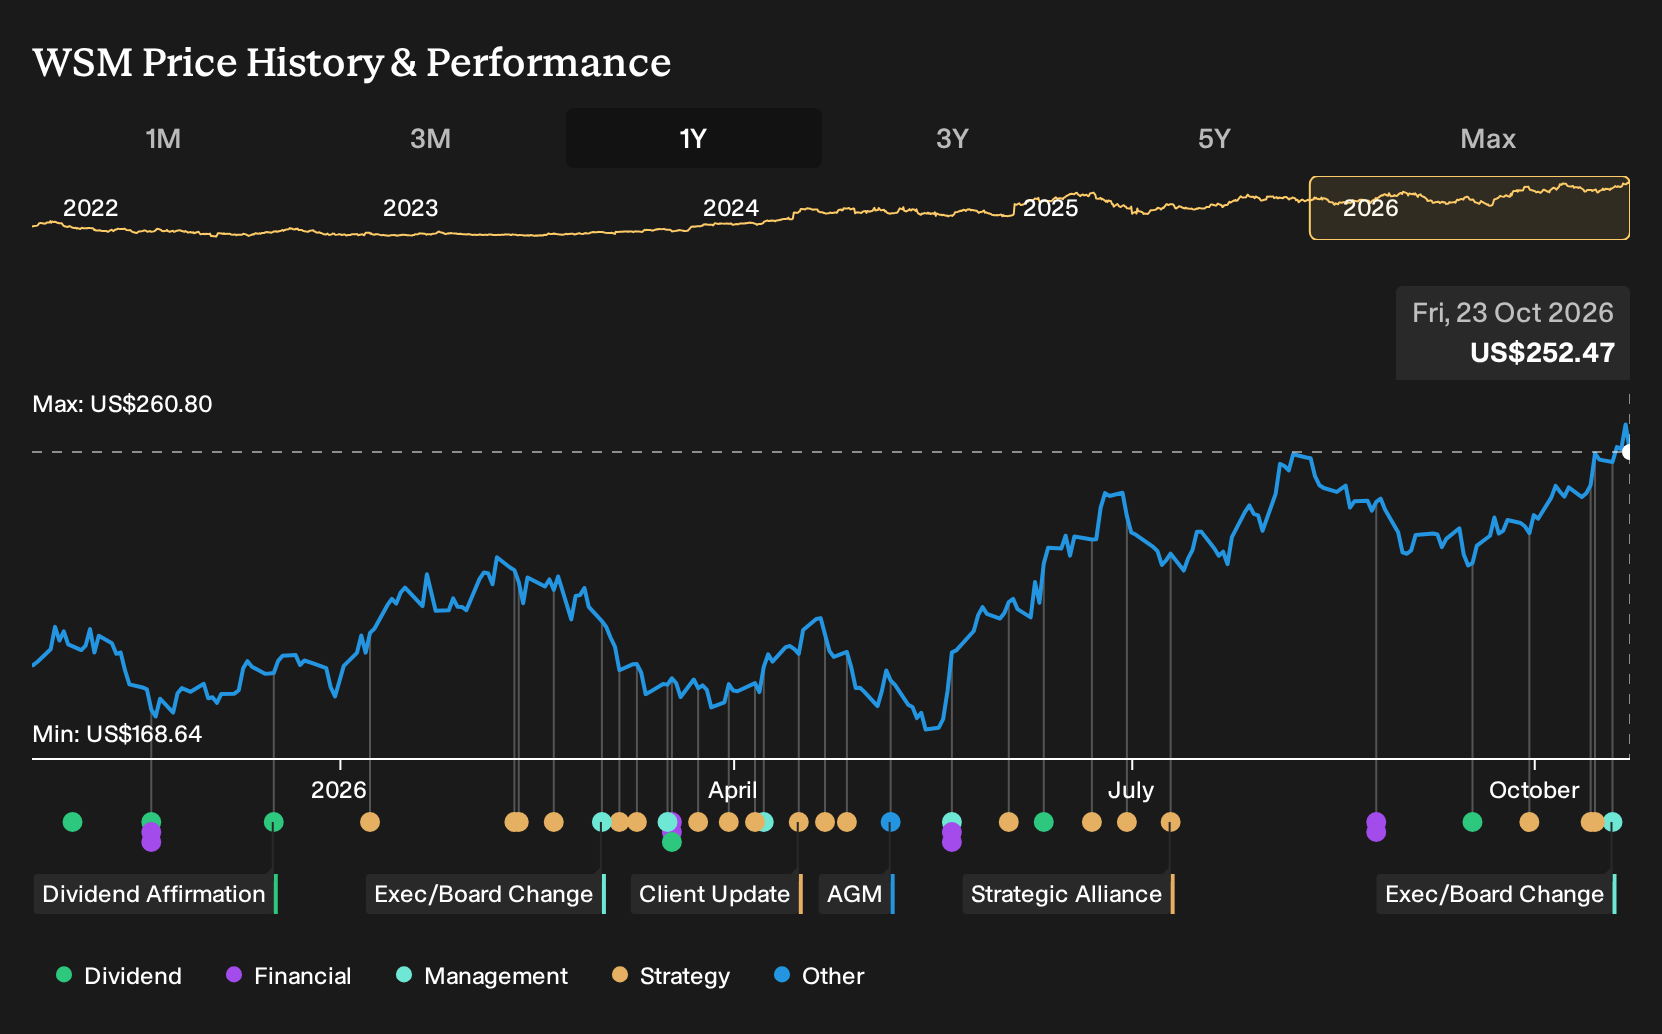
Exploring Other Perspectives
One alternate view puts far more weight on tariff and fuel cost risk. The most bearish analysts were only penciling in revenue of about US$9.3b and earnings near US$1.3b by 2029, using a lower 21.0x P/E. Those forecasts pre date the Williams-Sonoma holiday collaborations, so opinions may shift as new data comes through.
Explore 2 other Williams-Sonoma fair value estimates, including one that suggests it could be worth just $246.35.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Williams-Sonoma research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Williams-Sonoma. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Williams-Sonoma's overall financial health at a glance.
Looking for more investment ideas beyond Williams-Sonoma?
If Williams-Sonoma is on your radar, it can help to line it up against other opportunities that share similar quality traits or risk profiles. The Simply Wall St Screener lets you move from one story to a full watchlist in a few minutes, using pre built filters that focus on fundamentals rather than headlines.
- If capital preservation sits high on your list, start with a basket of companies that score well on stability through the 30 resilient stocks with low risk scores.
- For investors who care most about resilient finances, compare Williams-Sonoma with businesses that show strong balance sheets using this curated list of solid balance sheet and fundamentals (24 results).
- If the goal is to back quality that the market may be overlooking, line up Williams-Sonoma against a focused 21 high quality undiscovered gems and see which stories deserve a deeper look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com