


SECOM at a glance
SECOM (TSE:9735) has drawn fresh attention after a recent uptick, with the stock up about 5.8% over the past month and roughly 2.2% year to date.
Recent trading has leaned in SECOM’s favour, with a 1-day share price return of 0.40% and a 7-day move of 1.87%. This has contributed to a 30-day share price gain of 5.76% and a stronger 22.09% share price return year to date. The 1-year total shareholder return of 32.21% and 5-year total shareholder return of 92.23% indicate that momentum has been building over time, despite some cooling in the 90-day share price performance, which declined 2.14%.
Scan how SECOM compares with other established operators by reviewing a curated 22 resilient stocks with low risk scores that have shown resilience and more measured price swings.
SECOM has the profile of a solid security and services group, and the recent share price climb highlights that appeal. The real tension now is simple: does the current valuation still leave enough on the table for new capital?
Price-to-earnings of 24.2x: Is it justified?
On simple earnings terms, SECOM is not cheap. The stock trades on a P/E of 24.2x, while the broader JP Commercial Services group sits at 13.1x and the directly comparable peer set averages 16.8x.
The P/E ratio compares the current share price with earnings per share. Investors effectively pay 24.2 years of current earnings for each ¥1 invested in SECOM at the last close of ¥6,760. For a diversified security and services group, that kind of multiple usually reflects a willingness to pay up for quality, stability or relatively steady earnings rather than fast expansion.
SECOM carries some of those traits. Earnings have grown 5% per year over the past 5 years, earnings over the past year rose 4.1%, and the group reports high quality earnings. Forecasts point to annual profit growth of 6.8% and revenue growth of 4% each year, which are both below the wider JP market expectations and below the Commercial Services industry earnings growth of 9.4% over the past year. That combination suggests the current P/E of 24.2x builds in a full price for consistency, not rapid acceleration, while the estimated fair P/E of 24x implies the market may already be close to the level valuation models indicate it could move towards.
Compared with industry and peer benchmarks, the gap is clear. SECOM trades on a P/E that is nearly double the JP Commercial Services average of 13.1x and materially above the 16.8x peer group level, while only slightly above the estimated fair ratio of 24x. That points to a valuation where the premium is meaningful against competitors, yet only marginal relative to what the fair ratio suggests.
Explore the SWS fair ratio for SECOM.
Result: Price-to-earnings of 24.2x (OVERVALUED)
Still, a premium P/E for SECOM could come under pressure if revenue growth near 4% or profit expansion around 6.8% fall short of market expectations or sector peers.
Find out about the key risks to this SECOM narrative.
Another view on SECOM’s value
The P/E screen flags SECOM as expensive, yet our DCF model paints a softer picture. On that framework, the shares at ¥6,760 sit below an estimated future cash flow value of about ¥7,261, which implies a discount rather than a premium. So which yardstick do you trust more when those signals clash?
Look into how the SWS DCF model arrives at its fair value.
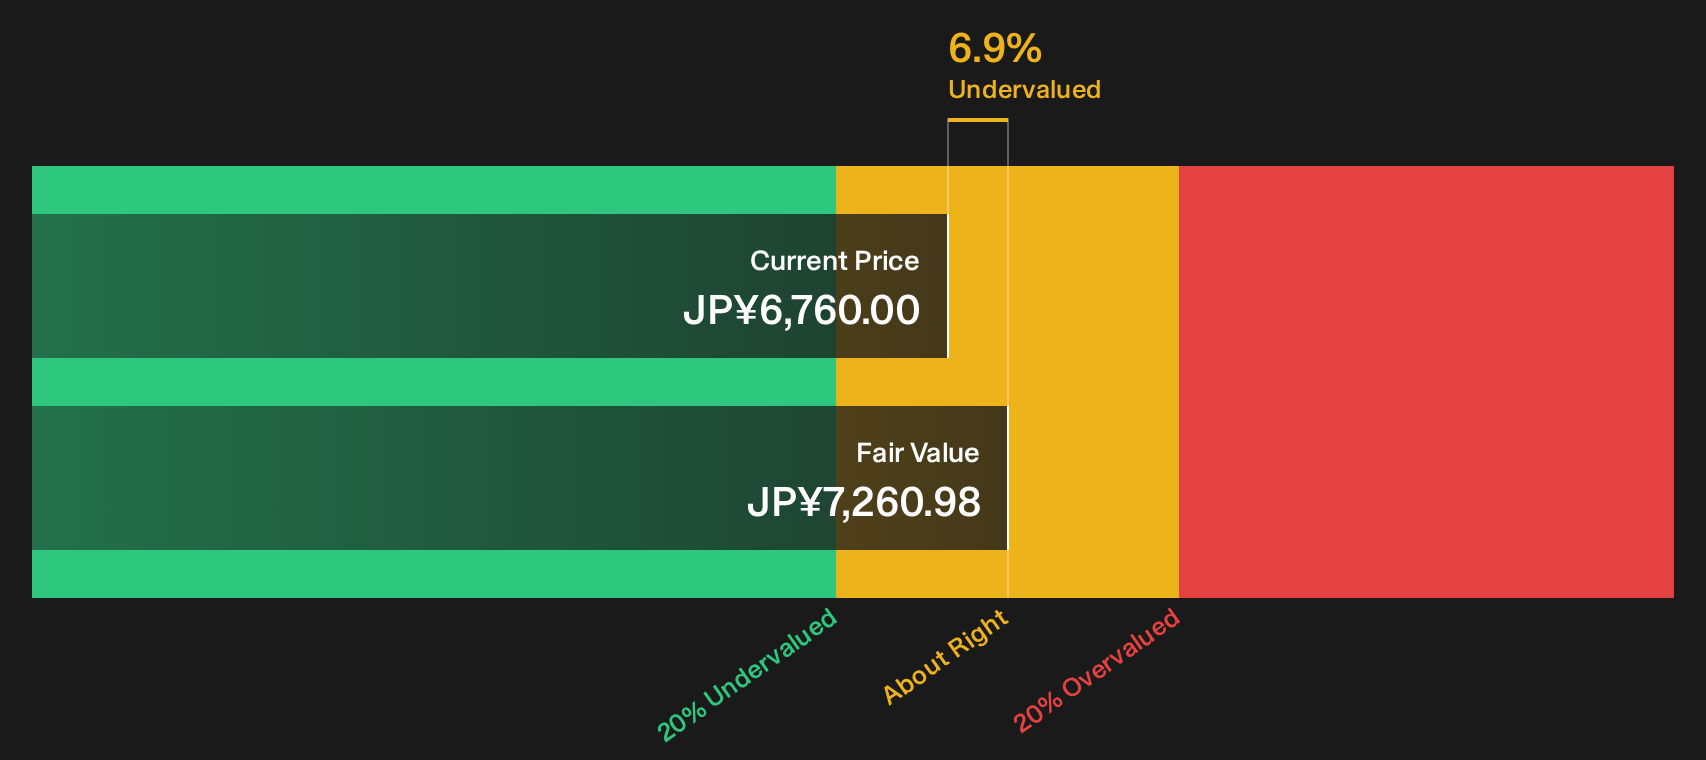
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SECOM for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
SECOM’s mixed valuation signals can feel confusing, so it helps to look directly at the underlying data and decide what stacks up for you. If you want a quick summary of why some investors are optimistic, take a closer look at the 3 key rewards.
Looking for more ideas beyond SECOM?
If SECOM has your attention but you want options, you can broaden your watchlist with other angles on quality, value and income that suit your own approach.
- Target robust potential income streams by scanning companies that appear in the 29 dividend fortresses.
- Hunt for quality at a sensible price by reviewing the 72 high quality undiscovered gems before they hit the mainstream radar.
- Prioritise resilience in tougher markets by focusing on businesses screened in the 22 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com