


AGC (TSE:5201) has drawn attention after a stretch of softer share performance. The price has declined over the past week, month, and past 3 months despite positive recent annual revenue and net income growth.
Over the past year AGC’s share price performance has cooled in the short term, with the stock down over the past quarter and month. However, the 1-year total shareholder return of 14.76% still reflects a materially stronger result than the recent pullback implies.
Spot opportunities with a similar risk reward profile by scanning our hand picked list of 14 high quality undervalued stocks alongside AGC.
AGC’s pullback leaves investors weighing a simple trade off. Has most of the easy upside already been captured, or does the current valuation still leave meaningful room ahead?
Most Popular Narrative: 16% Undervalued
AGC last closed at ¥5,447, while the most followed narrative pegs fair value at ¥6,516. That gap frames the recent pullback as a potential valuation reset rather than a verdict on the underlying business.
The company is benefiting from a medium-term demand recovery in architectural glass, supported by increasing requirements for energy-efficient renovations in Japan and a rebound in Asian markets, which is driving higher shipment volumes and improved pricing, positively impacting revenue and operating profit.
AGC is advancing product mix upgrades in automotive and electronics (including smart technologies and value-added glass), leveraging R&D investments and pricing policies that are already yielding better margins and enhancing both gross and net margins over the current cycles.
See why 4 investors see AGC as 16% undervalued.
Result: Fair Value of ¥6,516 (UNDERVALUED)
Still, if demand in Asia for architectural glass or PVC stays weak and Life Science losses persist longer than expected, the bullish AGC narrative could unravel quickly.
Find out about the key risks to this AGC narrative.
Another View: What AGC’s P/E Is Telling You
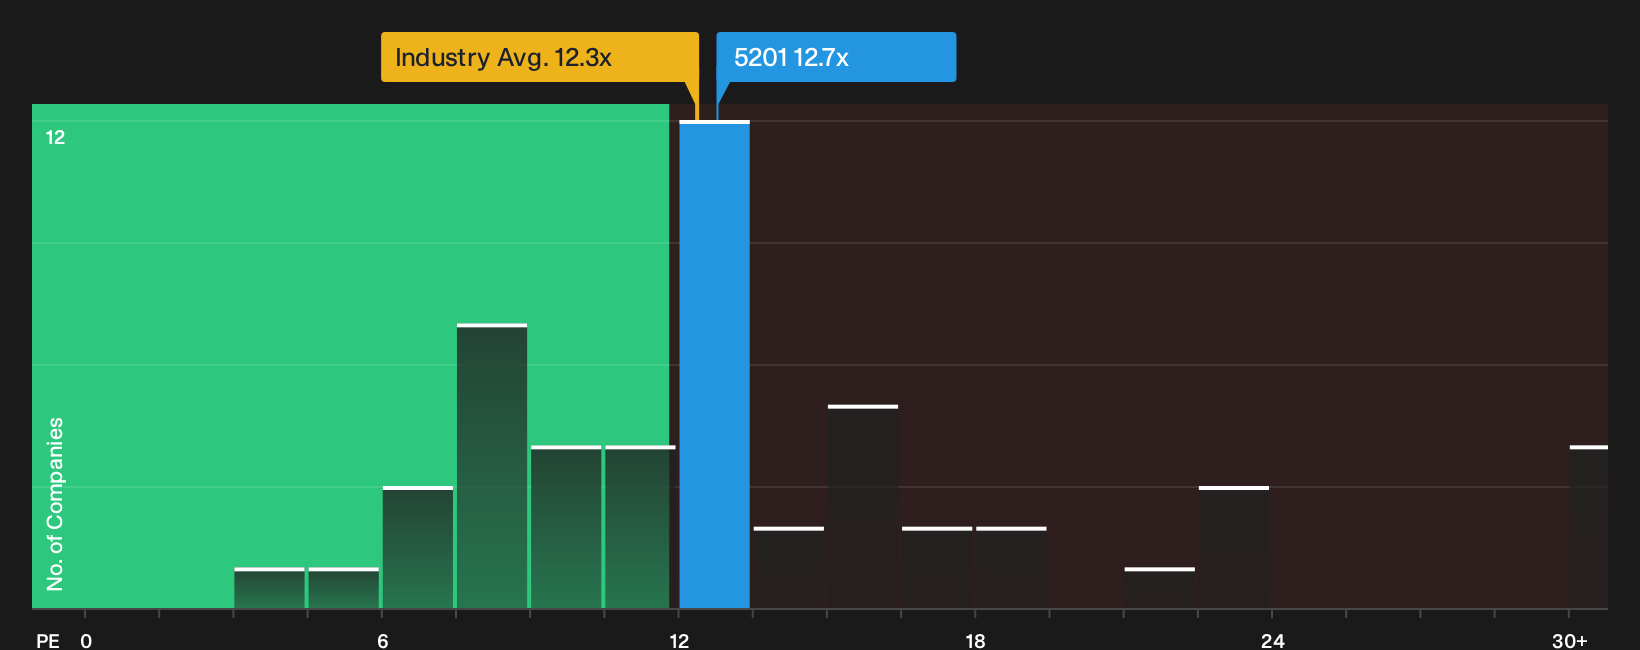
AGC looks cheap on the narrative fair value at ¥6,516, yet the current P/E of 12.7x is only slightly higher than the JP Building industry on 12.3x. The fair ratio sits at 18.7x. That gap hints at upside if sentiment improves, but it also raises a question: what if the market never pays that higher multiple again?
See what the numbers say about this price in our valuation breakdown, starting with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages in the recent AGC share performance make the picture tricky, so move quickly, analyze the data carefully, and pressure test both sides of the argument with 3 key rewards and 1 important warning sign.
Looking for more AGC sized investment ideas?
If AGC has you thinking harder about valuation, do not stop there. Put that curiosity to work across other opportunities and let the data do the heavy lifting.
- Target potential bargains early by scanning a focused pool of companies through the 14 high quality undervalued stocks.
- Prioritize resilience and support your peace of mind by filtering for balance sheets that look robust using the list of solid balance sheet and fundamentals (23 results).
- Hunt for less crowded opportunities by reviewing a curated stream of under-the-radar candidates with the 72 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com