


UDR (UDR) has just raised its earnings guidance for the third quarter and full year 2026, a move that puts fresh attention on how the apartment REIT’s outlook lines up with its current valuation.
The guidance hike and new Apollo joint venture arrive after a mixed run for UDR’s equity. The 7 day share price return of 5.91% comes after a 90 day decline of 8.10%, while the 3 year total shareholder return of 28.55% contrasts with a 5 year total shareholder return that is down 20.57%.
Spot opportunities similar to UDR’s latest guidance reset by scanning a curated 29 high quality undervalued stocks that combines income potential with balance sheet strength.Bulls point to UDR’s upgraded earnings outlook and Apollo partnership, while bears highlight uneven multi year returns and profit pressure. Which story does the current valuation actually echo as you line up the numbers?
Most Popular Narrative: 11% Undervalued
UDR last closed at $35.84, while the most followed narrative pegs fair value closer to $40.45 using a 7.41% discount rate. That gap puts the guidance raise and capital recycling plan under a brighter spotlight.
Ongoing capital recycling from roughly US$650 million of older, lower rent properties sold or under contract at mid 5% cap rates into share repurchases at an implied mid 6% cap rate and future higher growth assets can shift UDR’s mix toward properties with stronger rent potential and support earnings per share.
See why 8 investors see UDR as 11% undervalued.
Result: Fair Value of $40.45 (UNDERVALUED)
Still, UDR’s narrative can unravel if Sunbelt supply continues to pressure rents or if legal and regulatory actions cap pricing power and raise costs.
Find out about the key risks to this UDR narrative.
Another View: UDR Looks Expensive On Earnings
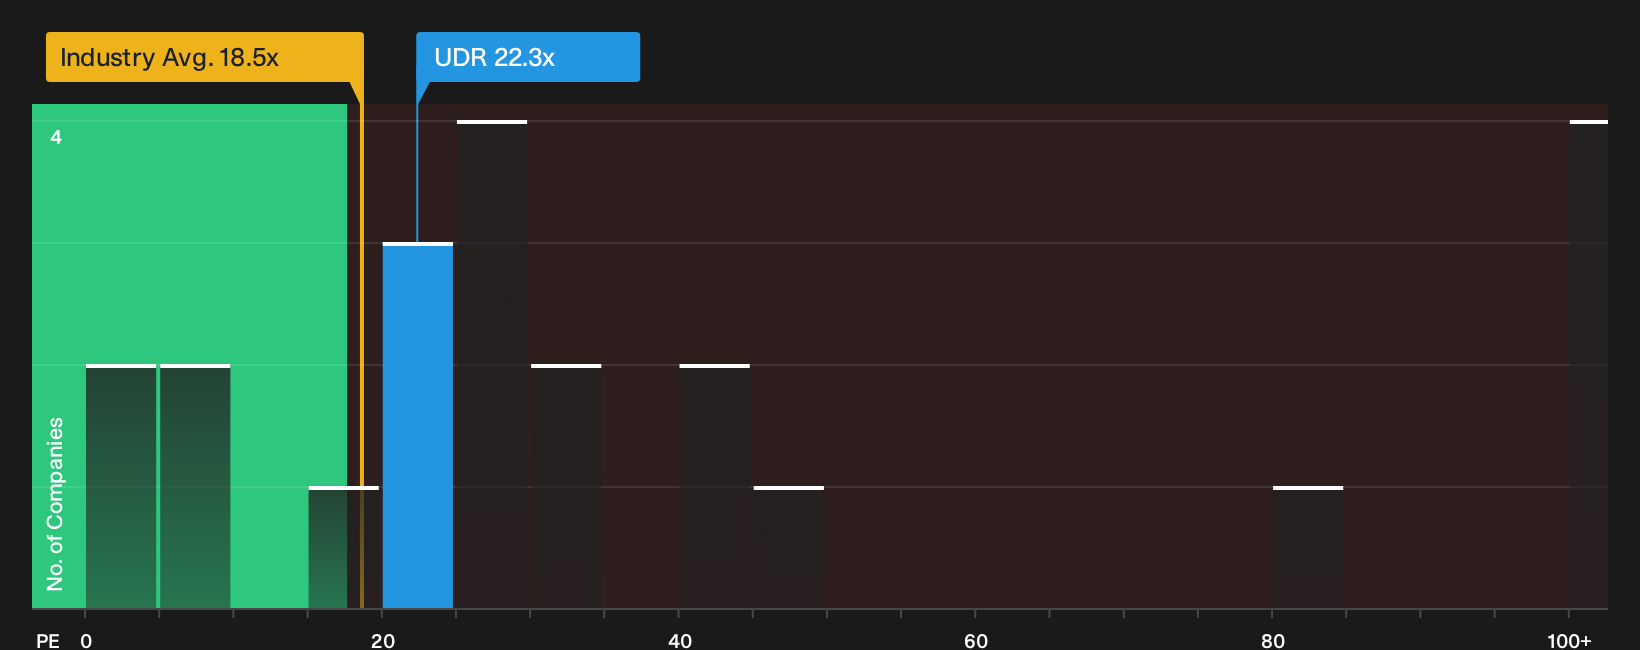
Looking at UDR through a simple P/E lens changes the picture. The stock trades on roughly 22.3x earnings, above the global residential REIT group at 18.5x and ahead of its own fair ratio of 16.5x, which points to higher valuation risk if sentiment cools.
For investors who prefer to focus on earnings multiples rather than cash flow forecasts, this kind of gap between the current P/E, peers, and the fair ratio raises a blunt question. Is UDR priced for a smoother road than its guidance and risk profile suggest, or is the market already braced for some bumps, with you deciding which scenario feels more realistic as you weigh the trade off in your own portfolio?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the data can be useful if you are willing to interrogate them rather than accept the headline story. Act quickly, analyze both the upside and downside signals, and ground your view in the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond UDR?
Do not stop your research with UDR. Broaden your watchlist with focused stock ideas that match different goals, risk levels, and income needs using the Simply Wall St Screener.
- Target consistent cash generation by reviewing a 5 dividend fortresses that can help you hunt for income opportunities with yields that may complement a REIT like UDR.
- Reduce portfolio stress by scanning a 30 resilient stocks with low risk scores that highlights companies with steadier risk profiles than many headline grabbing tickers.
- Spot potential early movers by checking a 21 high quality undiscovered gems before they show up on every analyst radar and crowd into valuations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com