


Champion Homes (SKY) recently rebranded from Skyline Champion Corporation, putting fresh attention on a business rooted in factory-built housing while the share price has declined over the past month and the past 3 months.
Over the past year, momentum in Champion Homes has cooled, with the share price down 10% over the past month and 7% year to date. Even so, the 1-year total shareholder return of 4.28% and 3-year total shareholder return of 33.63% point to a stronger longer-term story than the recent pullback suggests.
Compare Champion Homes to a curated group of factory-built and housing-related businesses by scanning our 28 high quality undervalued stocks. These companies already have solid balance sheets and cash flows screened for you.
Champion Homes now trades at a double discount, roughly 18% below one valuation estimate and about 23% under analyst targets after a weak stretch. Is that caution earned, or is the market overshooting?
Most Popular Narrative: 24% Undervalued
Against the latest close at $78.92, the most followed narrative for Champion Homes points to a fair value of $103.50 when its future cash flows are discounted at 8.28%. This represents a material gap that hinges on policy support and captive retail growth playing out as expected.
Increasing national focus on housing affordability and supportive policy momentum, now reinforced by the 21st Century ROAD to Housing Act becoming law in July 2026 and modernizing rules for HUD-code homes, is expected to drive structural demand for manufactured housing and support Champion Homes volumes and revenue over time.
See why 5 investors see Champion Homes as 24% undervalued.
Result: Fair Value of $103.50 (UNDERVALUED)
Still, the bullish narrative around Champion Homes meets two clear stress points: sustained input cost pressure that squeezes gross margin and a customer tilt toward lower priced models.
Find out about the key risks to this Champion Homes narrative.
Another View: What Champion Homes Looks Like On P/E
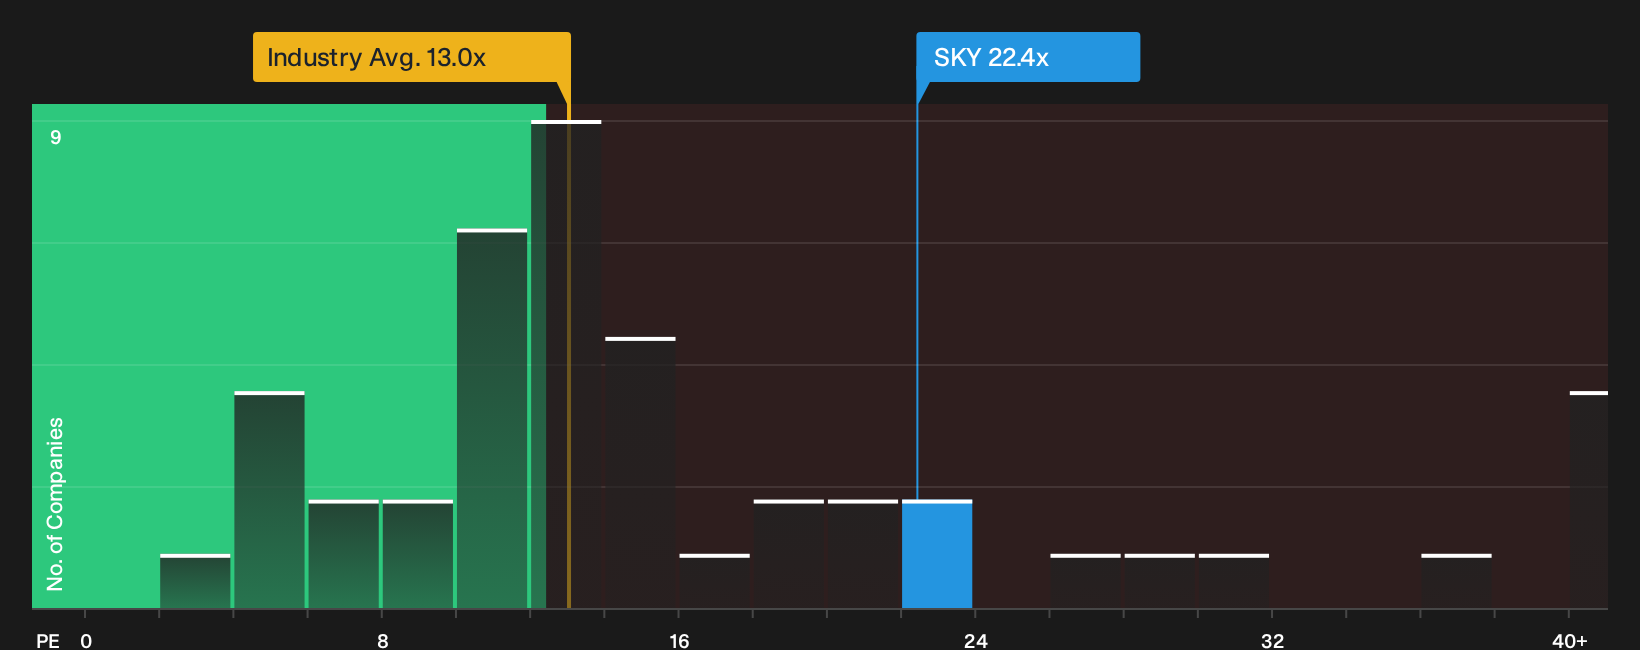
On price, the story tilts the other way. Champion Homes trades on a P/E of 22.4x while the US Consumer Durables industry sits at 13x and the peer group at 16.9x, compared with a fair ratio of 17.9x. That premium raises a simple question: Is the extra multiple reward for real business strength or just valuation risk creeping in?
See what the numbers say about this price in our valuation breakdown, then decide which story you find more convincing. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Champion Homes in this piece has been mixed, with both caution and optimism in play, so move quickly and test the numbers yourself against your own expectations. To see the optimistic angles already flagged by the data, review the 3 key rewards.
Looking for more investment ideas beyond Champion Homes?
If Champion Homes has your attention, do not stop here. Line up a few more quality candidates so your next move is intentional rather than reactive.
- Target potential mispricings by scanning a curated pool of financially strong candidates using the 28 high quality undervalued stocks.
- Strengthen portfolio resilience by focusing on companies with robust finances through the list of solid balance sheet and fundamentals (24 results).
- Get early access to potential future leaders by searching for quality businesses flying under most investors' radar with the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com