


- Recent commentary positions Precision Drilling as a leveraged play on North American onshore drilling, with its rig fleet, Alpha digital tools, and automation platforms closely tied to exploration and production customer activity.
- The focus on Alpha digital and robotics offerings highlights how contract renewals and technology adoption could reshape Precision Drilling’s margin profile, while unresolved financial questions may influence how much cash the business can commit to growth projects.
- We will look at how Precision Drilling's investment narrative intersects with its Alpha automation push and the related earnings power debate.
Scan beyond Precision Drilling and line up other rig and energy contractors by drilling exposure, automation focus, and balance-sheet strength with our curated list of solid balance sheet and fundamentals (7 results).
Precision Drilling Investment Narrative Recap
To own Precision Drilling, you need to be comfortable with a rig-heavy business that leans into high spec equipment, Alpha automation and EverGreen solutions to win work in North American basins. The near term upside many shareholders watch is how quickly customers adopt higher tech rigs as contracts roll, because that is where pricing and utilization can shift.
The biggest current risk sits on the other side of that equation. Capital spending for upgrades is sizeable and funded against a still meaningful debt load. If customer funded projects slow or pricing in Canadian rigs stays weak, the recent commentary on leverage to drilling activity does not materially change that near term tension.
With no fresh announcements filed alongside this automation focused news, the most relevant reference point remains Precision Drilling’s existing upgrade and Alpha rig program. That effort already ties directly to the thesis that higher spec rigs and digital tools can support better day rate mixes when customers prioritize efficiency in complex wells.
Look at that program in the context of today’s catalysts and risks. Customer appetite for funded upgrades is central to offsetting the CA$240m capital plan and to supporting returns on the Alpha and EverGreen suites. Execution missteps, slower rig reactivations or weaker demand from private US operators would all make that capex burden feel heavier very quickly.
Precision Drilling's current analyst narrative points to CA$2.1b in revenue and CA$243.3m in earnings by 2029, based on analyst expectations of 4.7% yearly revenue growth and an increase in earnings from CA$1.8m today to that 2029 consensus level.
Uncover how Precision Drilling's fair value indicates a 15% potential upside to its current price that may not last much longer.
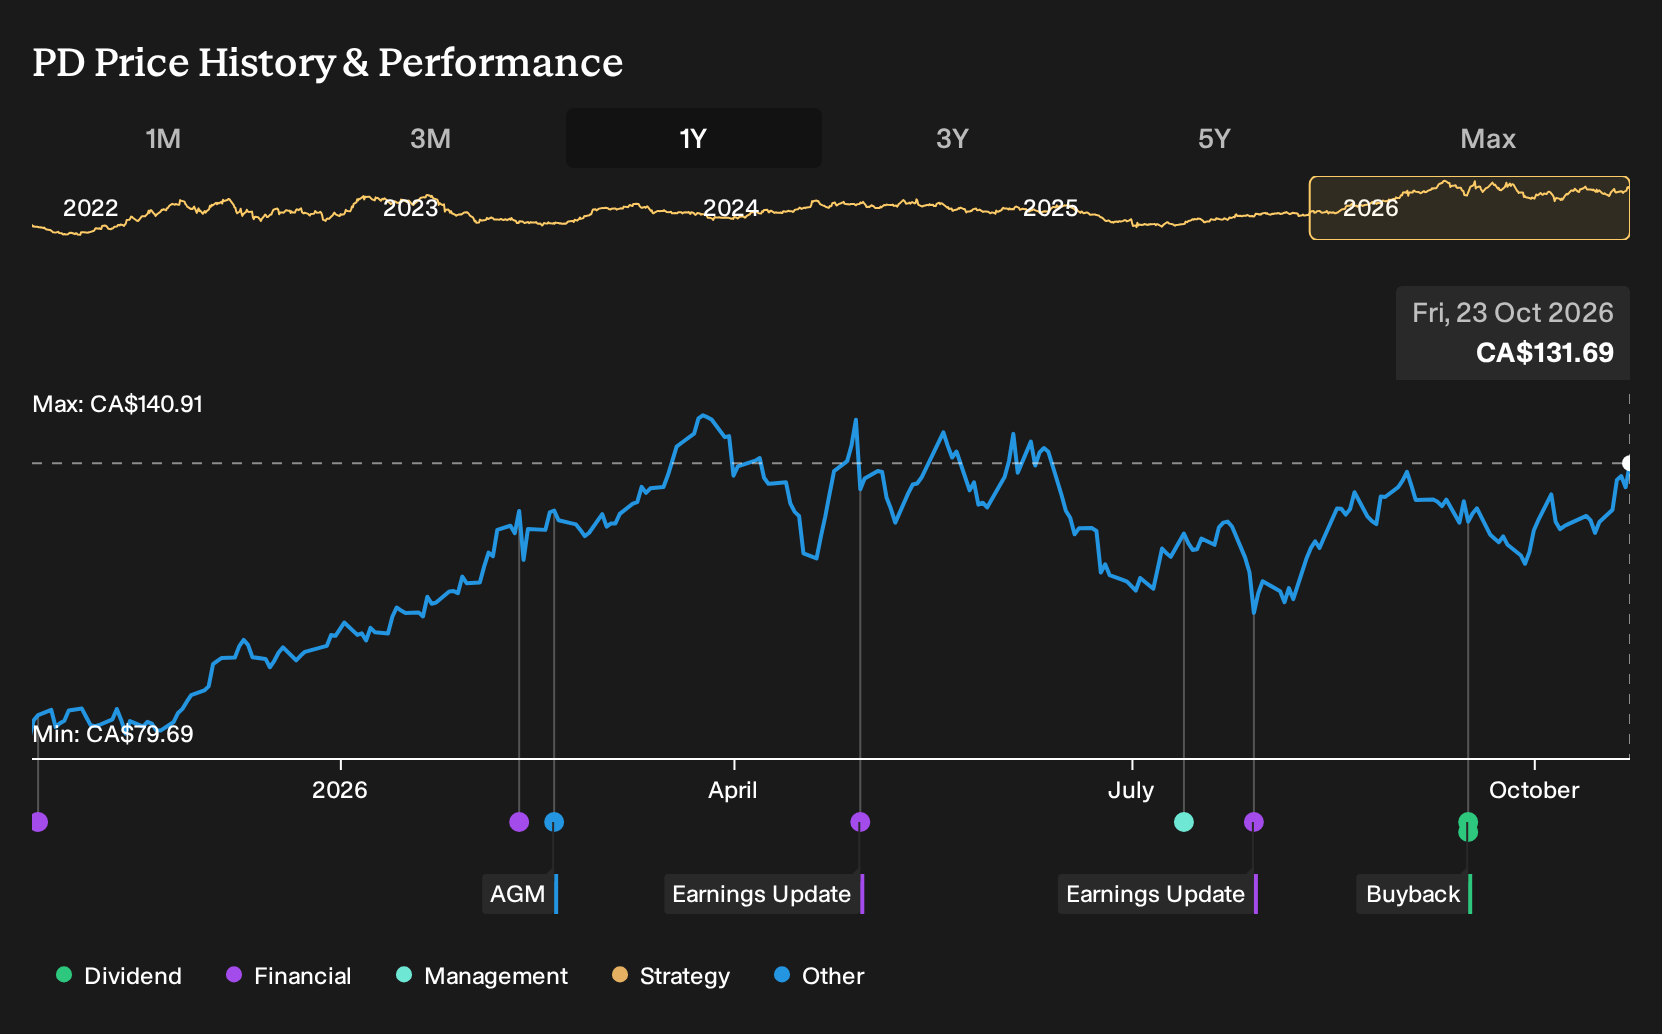
Exploring Other Perspectives
One alternate view on Precision Drilling focuses on the risk that higher upgrade and robotics spending eats into free cash flow, especially with U.S. margins under pressure and a possible Canada Revenue Agency reassessment. Those bearish analysts were only pencilling in CA$2.0b of 2029 revenue and CA$187.8m of earnings before this news, so their story around automation is far more cautious. You can treat this latest development as a fresh data point and decide which narrative feels closer to how you see the next few years playing out.
Explore 3 other Precision Drilling fair value estimates, including one that suggests it could be worth just CA$150.00.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Precision Drilling research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Precision Drilling. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Precision Drilling's overall financial health at a glance.
Looking For More Investment Ideas Beyond Precision Drilling?
If the Precision Drilling story has sharpened your thinking about risk, balance sheets and long term potential, it can help to line it up against a broader watchlist. The Simply Wall St Screener lets you filter for different angles so you can stress test your own approach rather than relying on a single stock.
- For investors who want potential upside without ignoring balance sheets, scan a curated 3 high quality undervalued stocks that pair fundamentals with pricing that still looks reasonable.
- If capital preservation and a smoother ride matter most, filter for companies in the 8 resilient stocks with low risk scores and see which profiles better match your comfort level.
- When you want something less crowded, look toward 9 high quality undiscovered gems that combine quality metrics with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com