


- Recent months brought renewed attacks on Russian refining facilities, raising questions for Oil Refineries about feedstock availability, export flows and operating continuity across key trade routes.
- The fresh disruption risk spotlights how Oil Refineries’ cash generation depends on refining margins and supply logistics rather than short term trading sentiment.
- Next, the focus turns to how Oil Refineries’ investment narrative absorbs renewed refining infrastructure risks linked to Russian facilities under pressure.
What Is Oil Refineries' Investment Narrative?
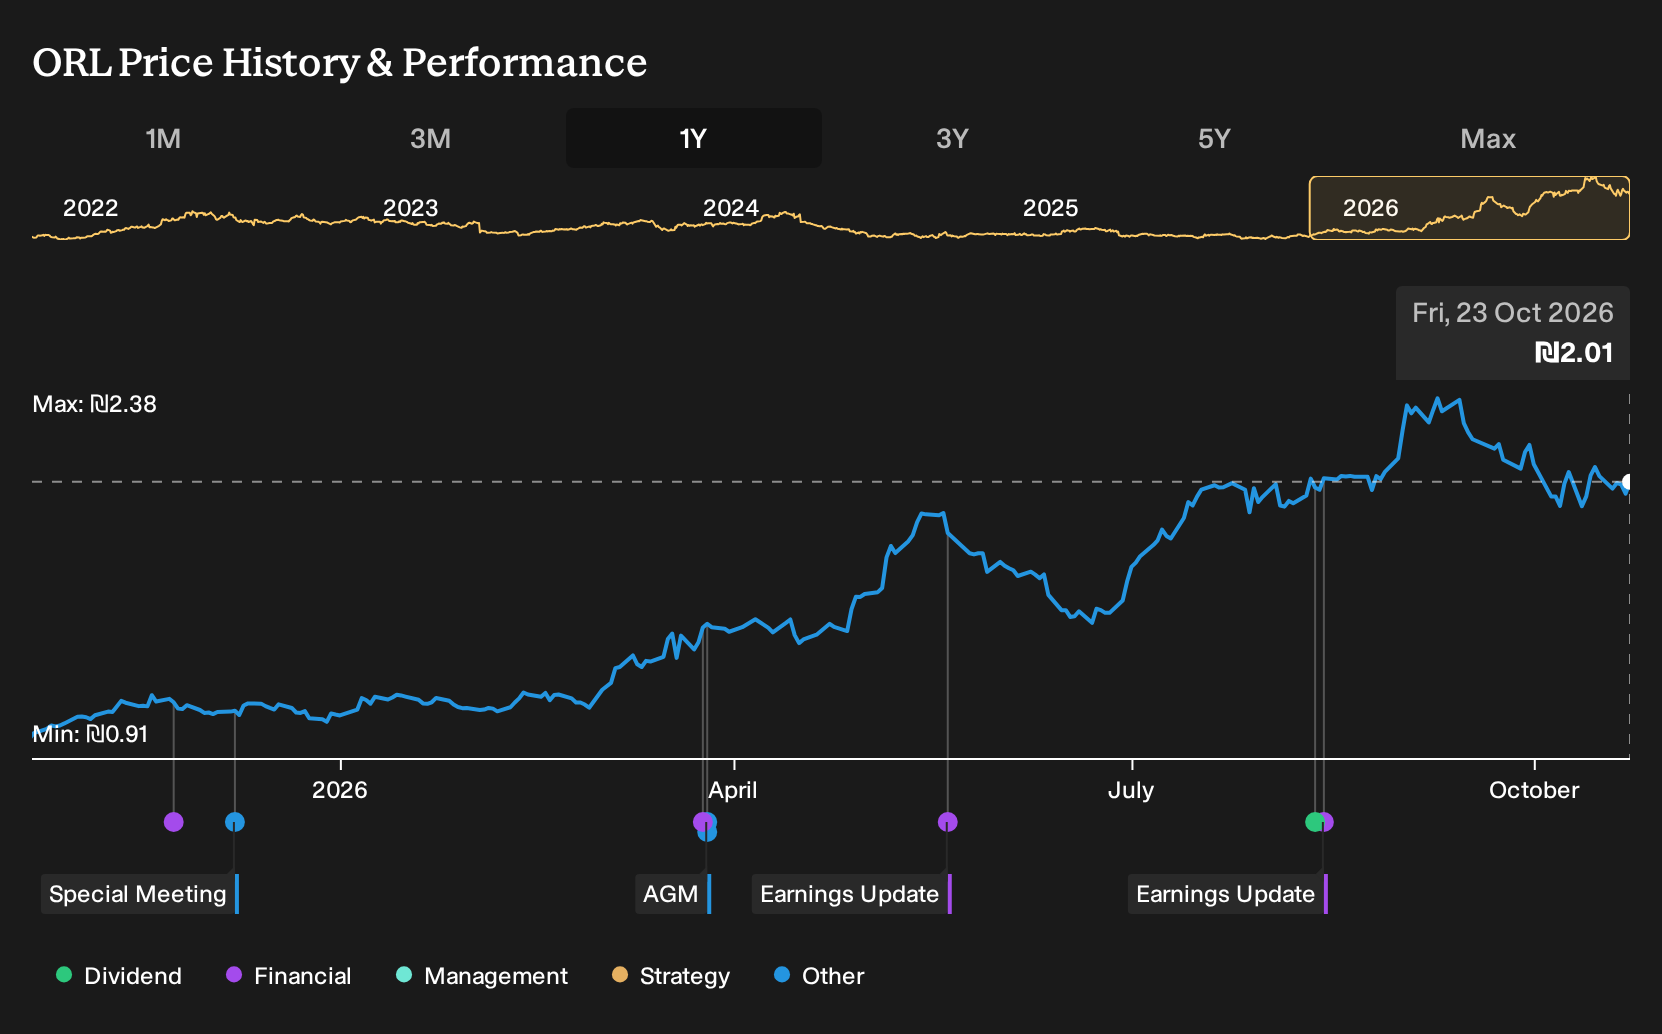
To own Oil Refineries, you have to believe in a very physical story. This is an industrial platform that turns crude into gasoline, diesel, polymers and aromatics, with cash generation hinging on refinery uptime, crack spreads and export logistics more than on short term market mood. Recent attacks on Russian facilities slot directly into that picture. Disruption risk can shift regional product pricing and feedstock flows, which feeds into refining margins and the Discounted Cash Flow work that points to a gap between price and estimated value.
In the short term, the key swing factors remain fairly clear. Refining and polymers are capital intensive, so interest costs that are not well covered by earnings matter, especially after years of declining profits. Management has an experienced team and a recently profitable year to point to. However, volatile trading, one off items in the last 12 months and fresh questions around Russian export routes all color how quickly Oil Refineries can turn estimated future cash flows into cleaner, recurring results.
Even so, there is one structural issue in the Oil Refineries story that could cap the upside if you look closely at...
There's only one way to know the right time to buy, sell or hold Oil Refineries. Head to Simply Wall St's company report for the latest analysis of Oil Refineries's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly 1.10x to 2.92x the current Oil Refineries share price, so private investors are looking at very different upside scenarios. These views were formed before the latest Russian refinery attacks, so treat them as a starting point and seek out more recent perspectives.
Explore another Oil Refineries fair value estimate, including one that suggests as much as 45% upside from the current price!
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Oil Refineries research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Oil Refineries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Oil Refineries' overall financial health at a glance.
Looking For More Investment Ideas Beyond Oil Refineries?
If the Oil Refineries story has you thinking about margin resilience, balance sheets and dividend reliability, it can help to compare similar traits across a wider watchlist using the Simply Wall St screener.
- If capital preservation is front of mind, start with a group of businesses screened for resilience through 223 resilient stocks with low risk scores that may better match your tolerance for volatility.
- If you care most about steady income, focus on companies offering reliable payouts by checking out 230 dividend fortresses that could complement or contrast Oil Refineries' profile.
- If you want stronger fundamentals and cleaner balance sheets, filter for financially robust companies using list of solid balance sheet and fundamentals (207 results) to build a shortlist worth deeper research.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com