


Mirion’s IAEA Partnership Puts Global Cancer Care In Focus
Mirion Technologies (MIR) has expanded its work with the International Atomic Energy Agency’s Rays of Hope initiative, contributing radiation therapy quality management software, hardware and training to help support cancer treatment in underserved regions.
This fresh commitment to the IAEA links Mirion’s medical radiation tools directly to global health programs. It gives investors a concrete example of how the business is embedding its products into international standards and long running clinical workflows.
Despite the positive optics of the IAEA partnership, Mirion Technologies’ recent share price performance has been weak. The stock is at US$14.81 and the 90-day share price return is down 11.79%, contributing to a 1-year total shareholder return that has fallen 39.65%, even though the 3-year total shareholder return remains up 114.33%.
Spot opportunities beyond Mirion Technologies by scanning a curated 16 nuclear energy infrastructure stocks linked to the same nuclear and radiation infrastructure themes driving this latest IAEA partnership.After a sharp slide despite the Mirion Technologies IAEA deal, the real tension is simple. Does that reset leave more upside than downside for new buyers, or is the recent fall just the start of a tougher valuation story?
Most Popular Narrative: 40% Undervalued
Analysts following Mirion Technologies see a fair value of $24.80 per share, which sits well above the last close at $14.81. They link that gap to a detailed set of growth, margin and risk assumptions rather than a simple mood swing in the market.
The accelerating global shift toward expanded nuclear power generation, coupled with rising capital budgets for modernization, life extensions, and increased capacity of the existing reactor fleet, is likely to drive sustained double-digit organic revenue growth and expand Mirion's higher-margin installed base business in coming years.
Strong momentum in advanced nuclear projects including utility-scale new builds and rapid activity in the small modular reactor (SMR) market has materially broadened Mirion's pipeline of large, multi-year opportunities, creating potential for significant step-changes in future order intake, backlog, and top-line revenue.
See why 8 investors see Mirion Technologies as 40% undervalued.
The most followed narrative uses a 9.58% discount rate and ties that $24.80 figure to a forecast that Mirion Technologies could grow revenue by 10.5% a year while lifting profit margins from 2.4% to 15.4% over the next few years.
Those same assumptions feed into an earnings estimate of $213.4 million by around July 2029, with the narrative implying the shares would eventually trade on a P/E of 45.6x those projected profits, compared with a P/E of 147.4x on the latest reported earnings and an estimated fair P/E of 55.7x.
To line up with this view, you would need to be comfortable that Mirion’s exposure to nuclear infrastructure, its software mix shift and its acquisition program can collectively support those earnings targets at the 9.6% discount rate used in the model. You would also need to accept that the consensus fair value still builds in a materially higher multiple than the 29.4x currently applied to the broader US Electronic industry.
Result: Fair Value of $24.80 (UNDERVALUED)
Still, Mirion Technologies leans heavily on nuclear related demand and acquisition driven expansion, so policy reversals or integration setbacks could quickly challenge the upbeat analyst script.
Find out about the key risks to this Mirion Technologies narrative.
Another View: Mirion Technologies Looks Expensive On Earnings
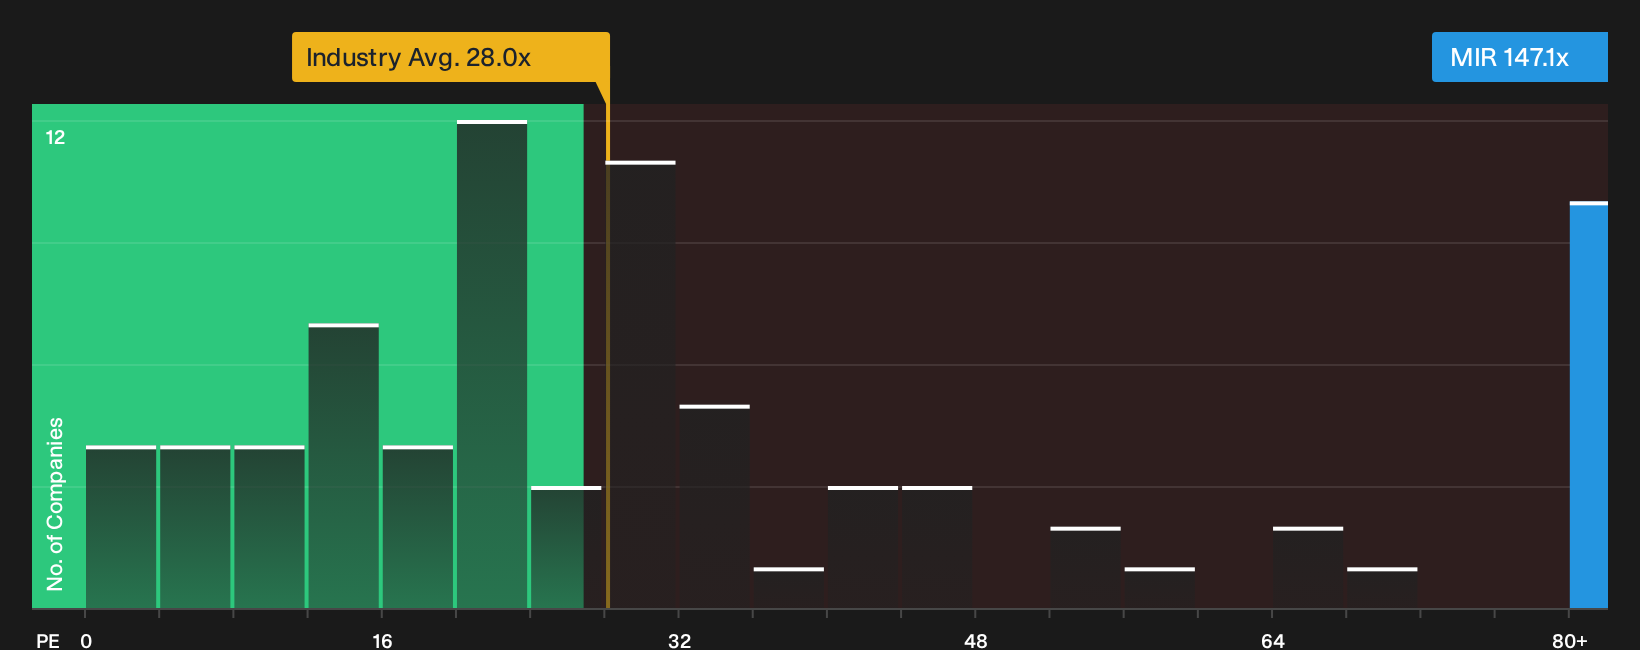
Mirion Technologies screens as undervalued on analyst fair value and DCF style work, yet its current P/E of 147.1x sits far above the Electronic industry at 28x, the peer group at 23x, and even the 55.7x fair ratio that our models suggest the market could move toward.
If the share price ever gravitates closer to that fair ratio or to sector and peer averages, the gap would close through a lower valuation multiple rather than just future profit growth. This raises the question investors need to answer: Is this premium simply early belief in the analyst story, or is it a valuation risk that outweighs the upside narrative?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on Mirion Technologies after all this, or already leaning one way? Act quickly, dig into the data yourself, then weigh up the 4 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Mirion Technologies?
If Mirion Technologies has your attention, do not stop there. Fresh ideas often come from comparing similar opportunities side by side using clear, consistent criteria.
- Target potential mispricings by reviewing a curated 28 high quality undervalued stocks that surfaces opportunities where quality and price may be out of sync.
- Strengthen portfolio resilience by scanning a list of solid balance sheet and fundamentals (24 results) so your watchlist leans toward sturdier financial foundations.
- Get ahead of the crowd by working through a 21 high quality undiscovered gems that highlights lesser known businesses with strong underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com