


- Centene’s Ambetter Health unit recently outlined its 2027 Marketplace line up, adding condition specific Premier plans for diabetes, heart failure, asthma and COPD, along with expanded telehealth access and wellness rewards across more than 3.5 million members in 27 states.
- The upcoming National Performance Based Gold Card Program aims to cut prior authorization friction for over 160,000 high performing providers. This could influence Centene’s operating costs and clinical workflow efficiency as it prepares to report a quarter with an expected 5.8% revenue decline.
- We will now look at how Centene’s chronic condition focused Ambetter Premier plans could reshape the company’s broader investment narrative.
Scan beyond Centene and line up other health insurers focused on chronic care and telehealth through our curated 34 healthcare AI stocks.
Centene Investment Narrative Recap
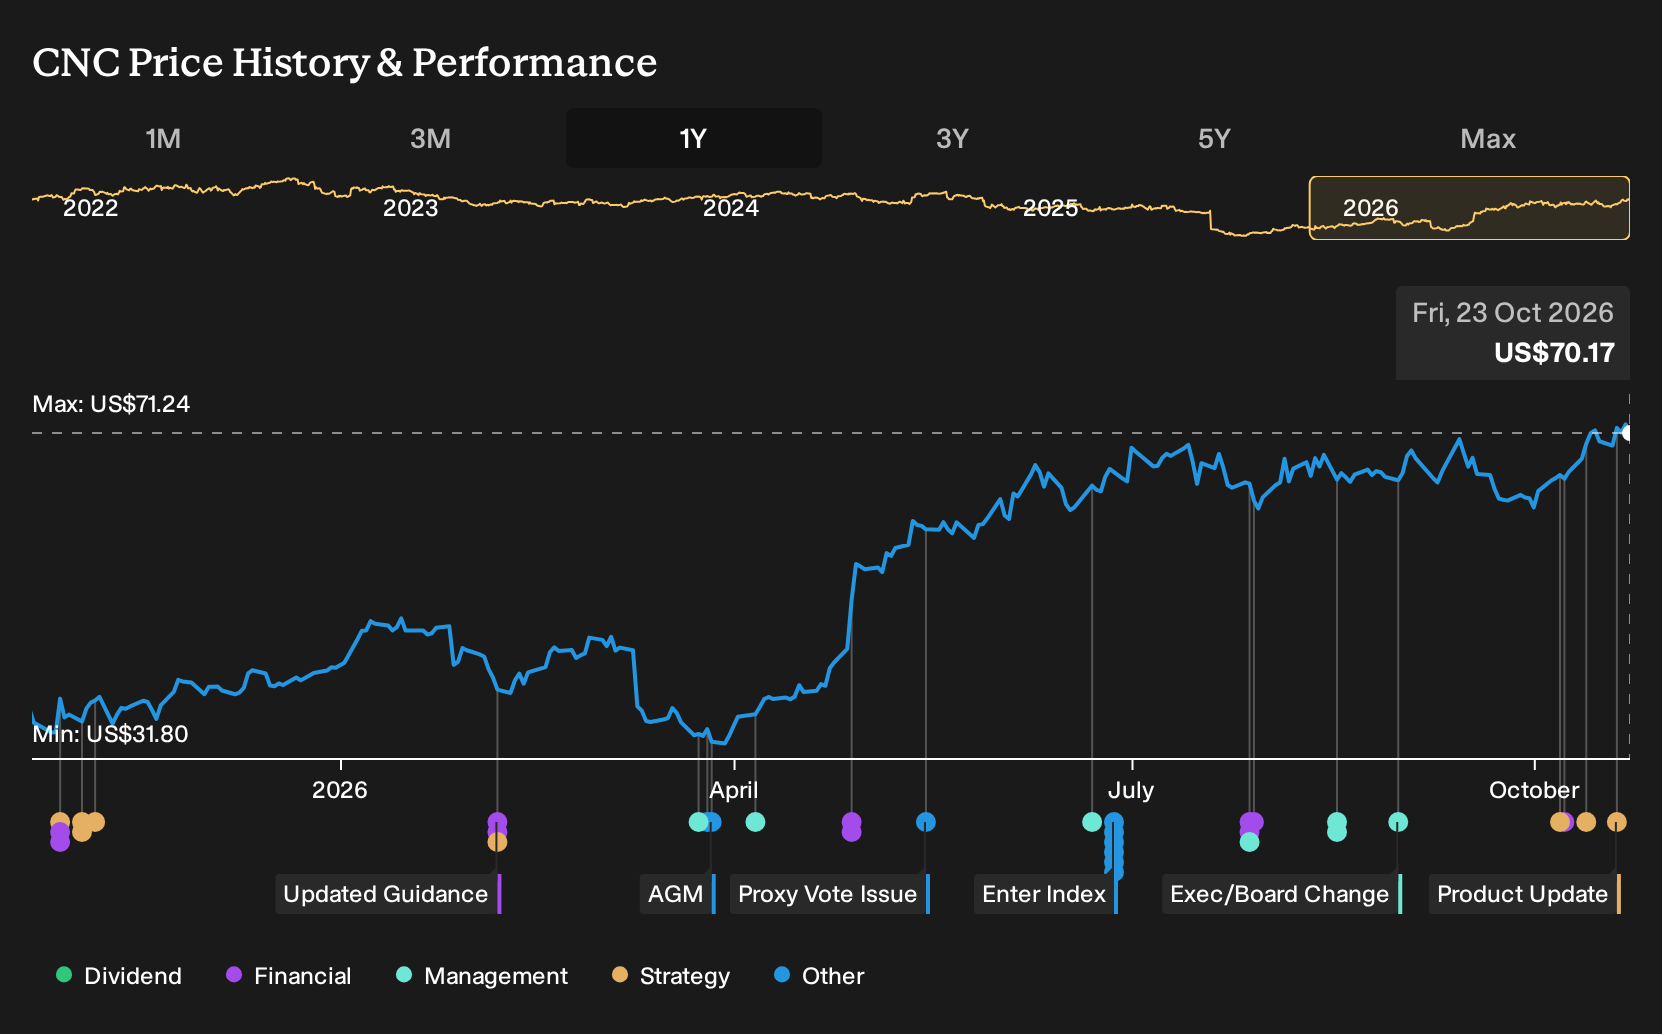
To own Centene, you largely need to believe the margin repair story across Medicaid, Marketplace and Medicare can translate into consistent profitability while policy support for these programs broadly holds. The most immediate swing factor is execution against margin targets as the firm heads into a quarter where revenue is expected to decline 5.8% year on year.
The main risk is that slower Medicaid membership and any pressure on Marketplace premium support offset the benefits of cost work and pricing. The new Ambetter Premier plans and telehealth benefits may not move near term earnings on their own, but they feed into the longer term mix and quality story investors watch closely.
The Ambetter Health Premier expansion looks most relevant for you as a Centene follower. Chronic condition plans with $0 copays on key drugs, specialist visits and supplies speak directly to how the Marketplace book could skew toward members with higher medical needs, where pricing, risk adjustment and care management all matter for margins.
Programs such as virtual 24/7 care, My Health Pays rewards and Walgreens or YMCA partnerships add more levers to influence engagement and potentially medical cost trend. The short term catalyst remains proof that Marketplace and Medicaid margin goals are achievable. The operational risk sits in executing these richer benefits without letting medical costs outpace the company’s rate and cost discipline.
Centene’s Long Range Assumptions Around Ambetter And Chronic Care
Centene’s chronic condition push through Ambetter Premier sits on top of a set of analyst assumptions that are worth having in the back of your mind. The story investors are being asked to underwrite is less about a single product line and more about a gradual reset in profitability across a much larger revenue base.
Analysts are currently modelling Centene’s revenue to rise by 4.5% a year over the next three years, with profit margins shifting from a loss of 2.8% today to a 1.5% profit in roughly three years’ time. Earnings are expected to move from a loss of US$5.1b today to US$3.2b by 2029, with earnings per share at US$6.67 if those forecasts hold.
That swing in profitability implies an earnings change of about US$8.3b from today’s loss to the 2029 profit figure. For an investor watching the Ambetter Premier rollout, this is the context. The richer chronic condition benefits need to fit inside an earnings bridge that already assumes meaningful margin repair across Medicaid, Marketplace and Medicare rather than a new round of cost pressure.
Analysts also plug in a future P/E of 14.1x on those 2029 earnings compared with a loss driven multiple of 6.3x today. They also assume the share count increases by 0.5% a year over the next three years. These inputs sit alongside a discount rate of 7.5% to 7.51% used in one popular model, which is how the various margin and revenue assumptions are pulled into a single valuation framework.
Centene’s narrative projects US$205.7b revenue and US$3.2b earnings by 2029. This requires 4.5% yearly revenue growth and an earnings increase of about US$8.3b from a loss of US$5.1b today.
Uncover why Centene's fair value indicates that Centene is roughly in line with its current price.
Exploring Other Perspectives
Bullish analysts focus on Centene’s ability to turn chronic care focus into higher earnings, not just stable margins. Before this Ambetter Premier news, the most optimistic forecasts already pencilled in revenue of about US$213.9b and earnings of roughly US$4.5b by 2029. You can compare those expectations with your own view and decide whether this latest rollout could shift the story.
Explore 4 other Centene fair value estimates, including one that suggests up to 170% potential increase from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Centene research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Centene. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Centene's overall financial health at a glance.
Looking For More Investment Ideas Beyond Centene?
Centene may be the focus today, but your portfolio probably needs a mix of different businesses and risk profiles to really work for you over time. A quick way to pressure test your ideas is to look across other stocks that match specific qualities using the Simply Wall St Screener.
- If you want potential future upside but still care about underlying quality, scan through a curated set of 21 high quality undiscovered gems that already show strong fundamentals.
- For a focus on financial resilience and balance sheet strength, filter for companies in the list of solid balance sheet and fundamentals (24 results) and see which ones fit your risk tolerance.
- When capital preservation and a smoother ride matter most, narrow your search to a 30 resilient stocks with low risk scores that can help anchor the more volatile parts of your portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com