


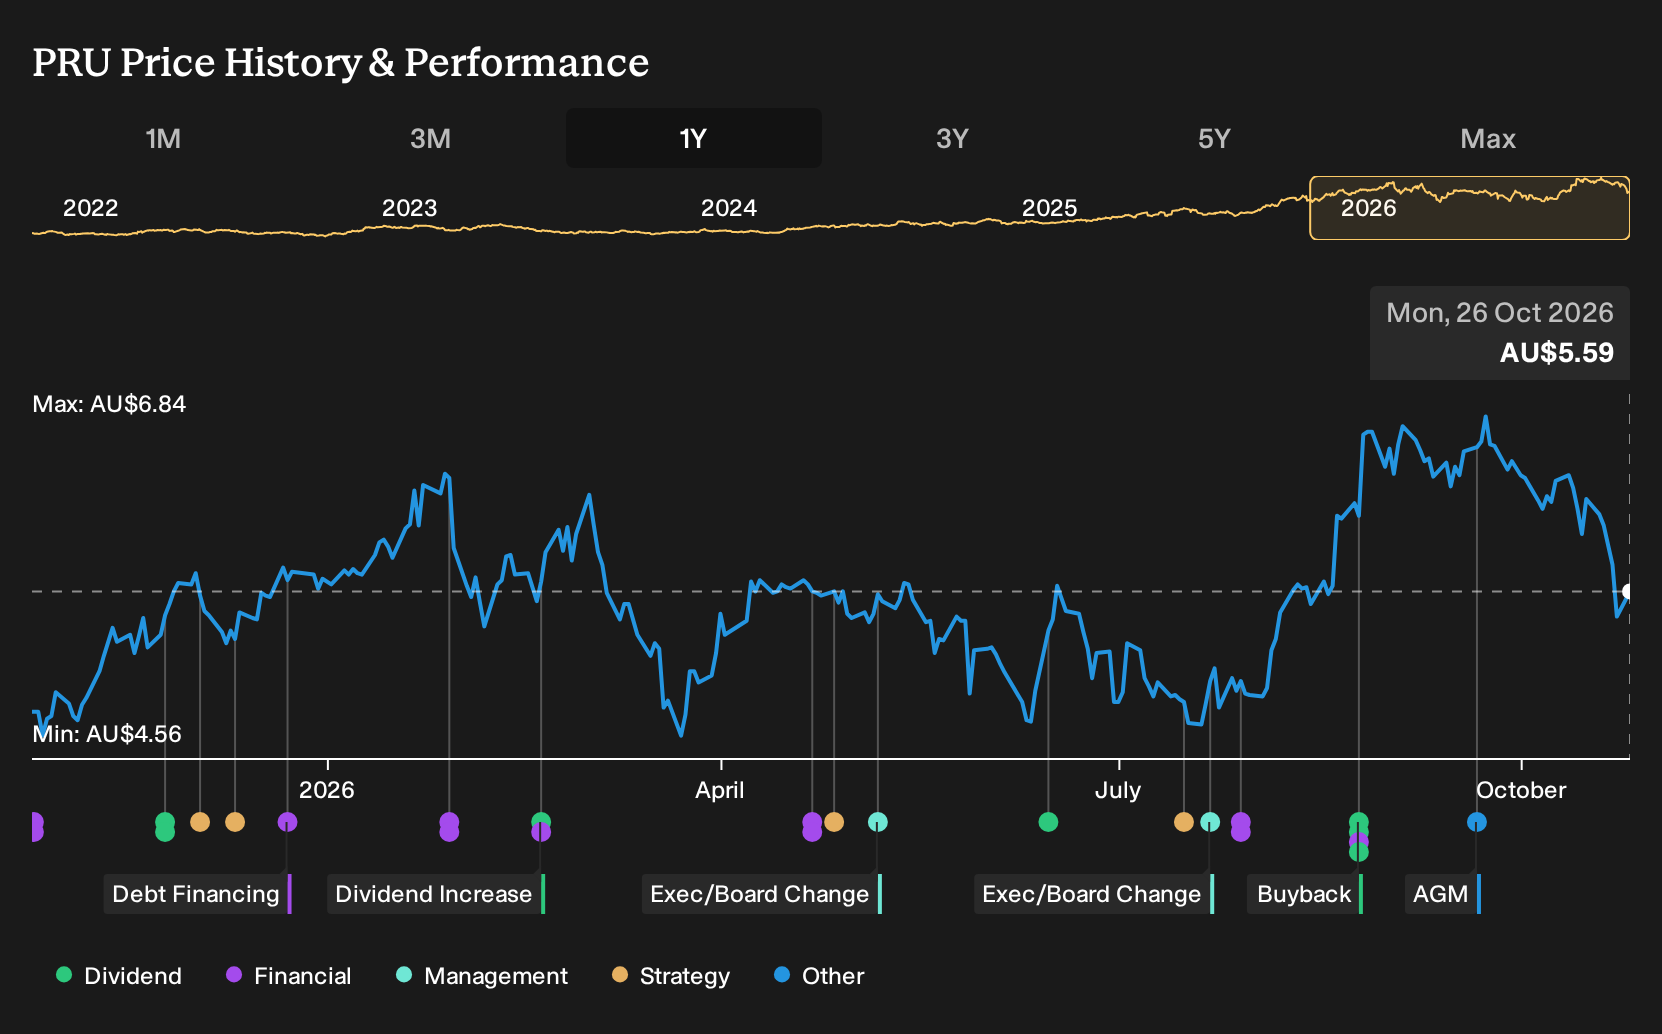
If Perseus Mining was on your watchlist instead of in your portfolio, the result may feel like a missed call. For Perseus Mining shareholders, the return over the past year was 20.8%, including dividends. That move now sits alongside headlines about a larger buyback, strong H2 2026 earnings and rising reserves, but the real question is simpler. Back on 26 October 2025, what conviction around future mine expansion and cost control could have flagged this outcome as plausible?
This theme extends beyond Perseus Mining. See which of 35 elite gold producer stocks may still merit a closer look.
The Two Conflicting Stories Around Perseus Mining
The shares cost A$4.73 at the start of the period, and anyone looking at Perseus Mining then had to choose between two sharply different stories.
The bullish view saw a Fair Value of A$5.8, an implied upside based on assumptions that Nyanzaga and the CMA underground would ramp up faster than consensus and that tight cost control could lift profit margins over time.
The bearish camp put Fair Value at A$2.55, reflecting worries that heavy reliance on high gold prices and exposure to West African and Tanzanian political risk might erode future earnings and cash flow.
What The Results Changed For Perseus Mining
Perseus Mining’s H2 2026 report showed revenue of US$875.447m and net income of US$264.703m, with net margin rising from 28.9% to 30.2%. That outcome lined up more closely with the bullish story that expected stronger profitability from cost control and new projects. Political and gold price risks did not disappear, so the evidence still cut both ways rather than fully settling the argument.
The useful lesson is where to look first. When a thesis leans on better cost discipline and project execution, track net margin and project milestones in later filings, not just headline revenue or the share price.
What Perseus Mining’s Price Now Assumes
Perseus Mining trades at A$5.59 today. The selected Narrative’s Fair Value sits below that level, tying its stance to concerns about gold reliance, higher environmental costs, and geopolitical exposure, even as it accepts that current projects and the balance sheet support ongoing operations and shareholder returns.
At today’s price, you are effectively betting that Perseus Mining can keep cash flows resilient despite those pressures. The key question is how that assumption stacks up against the Narrative’s view that higher compliance costs, political risk, and changing investor preferences could bite into future free cash flow and valuation.
"Rising environmental compliance costs and shifting investor sentiment away from mining could constrain capital access, reduce free cash flow, and pressure long-term valuation. Perseus remains highly exposed to West African and now Tanzanian geopolitical risks, where government stability and regulatory predictability are far from assured; political disruption, rising royalties, or abrupt legal changes could increase costs or halt operations outright, severely jeopardizing sustainable cash flow and earnings."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Perseus Mining And A Different Metal Question
Perseus Mining puts you close to gold. One step away, another miner tackles a different bottleneck in critical materials.
Rare earths support motors, turbines and high end electronics across many applications. This business extracts those elements from ore and refines them into higher value materials.
It is moving further into processing and magnet manufacturing instead of stopping at concentrate. Those magnets are used in electric vehicles, clean energy equipment and defense hardware.
These customers often require reliable supply and strict traceability across complex chains. Government support, long term contracts and recycling projects all shape this operator's evolving role.
The open question is how firmly that position holds as technology and policy keep shifting.
That argument has a Narrative and a number behind it. → See the company one Narrative values 85% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com