


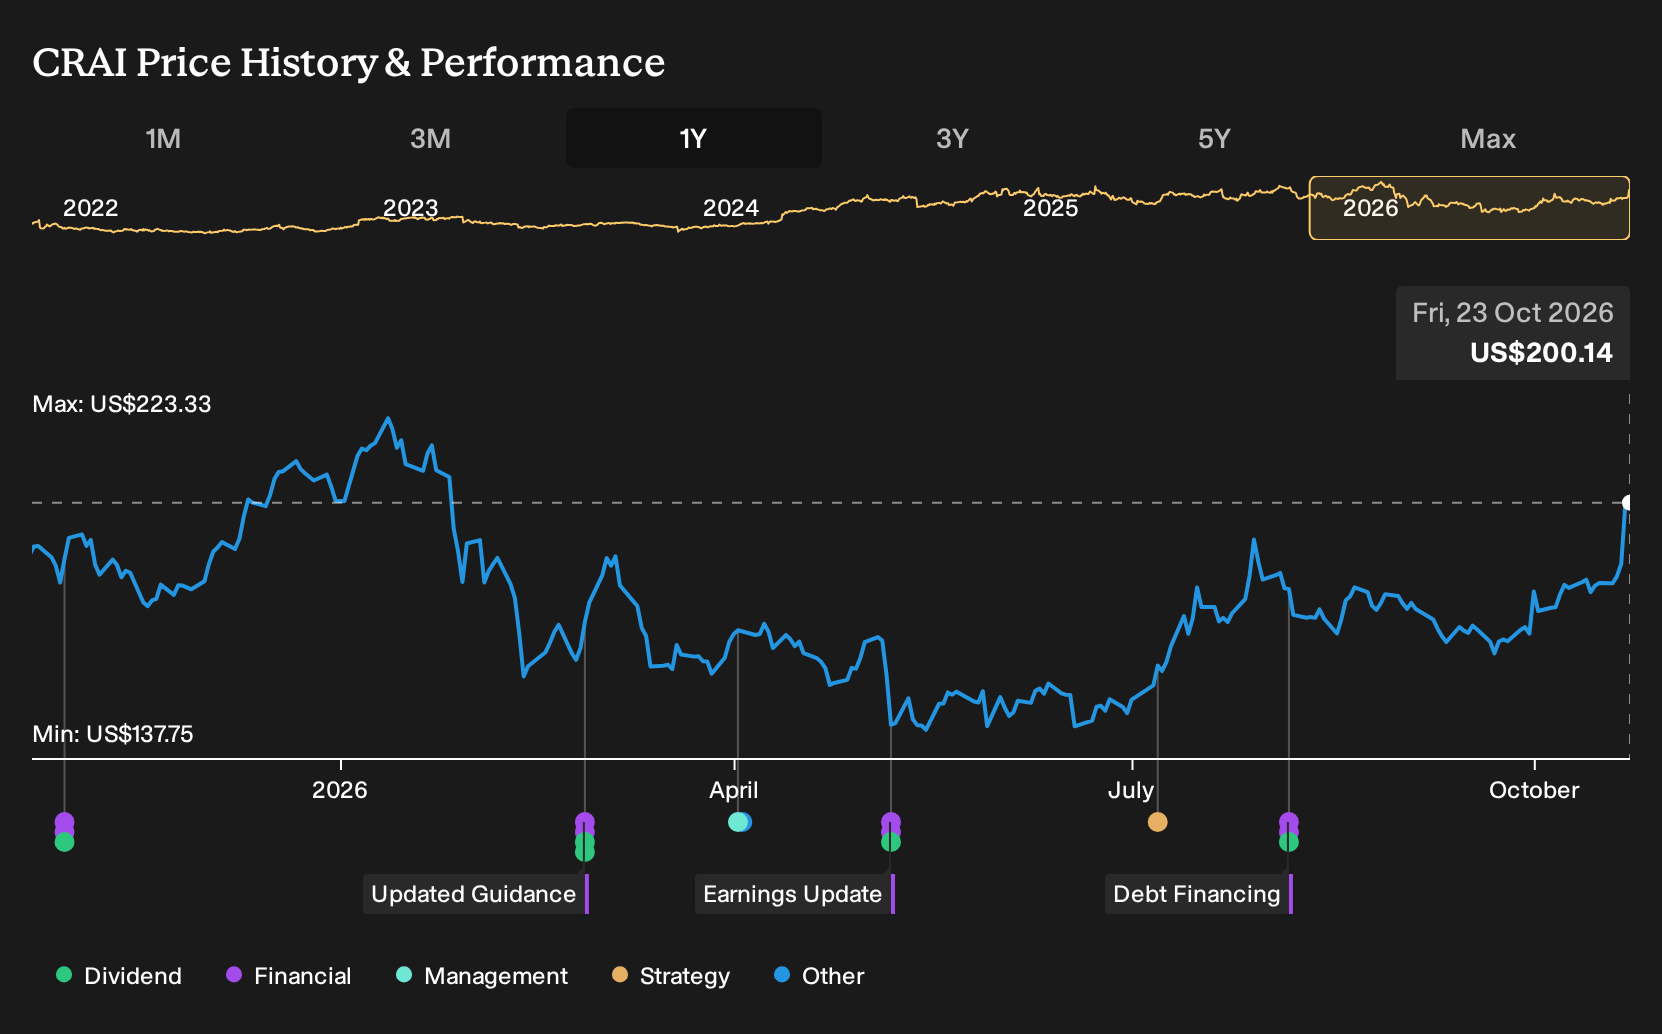
- CRA International recently reported revenue and earnings per share that both moved higher, and management responded by raising its expectations for the business.
- The consulting firm now trades at a premium to the wider Professional Services group. This suggests investors are closely watching how its operating model converts demand into sustainable profitability.
- We will now see how CRA International's raised management expectations could influence the broader investment narrative around its consulting platform.
Scan for other consulting and professional services stocks that appear to be experiencing similar earnings momentum by starting with the hand picked 21 high quality undiscovered gems.
CRA International Investment Narrative Recap
To own CRA International, you need to believe its consulting platform can keep turning complex legal, regulatory, and sector work into steady case flow at attractive billing rates. The raised management expectations after the latest revenue and EPS update support that thesis in the near term. The key short term catalyst remains how quickly recently added experts and international offices translate into higher utilization.
The biggest operational risk is that case volumes in M&A and enforcement cool while CRA International carries a higher fixed cost base and more debt. In that scenario, margins and cash generation could come under pressure, which would matter more to the story than this quarter’s raised outlook.
The most relevant recent development is management lifting its expectations following the revenue and earnings beat. That update indicates the leadership team currently sees enough booked work and visibility to justify a stronger near term view on CRA International operations.
Higher guidance also raises the bar. With the stock trading at a premium to the broader Professional Services group, execution around staffing, pricing, and case mix now has less room for missteps. Any signs that case activity or collections lag those higher expectations could quickly refocus attention on utilization, non cash earnings quality, and debt coverage.
What The CRA International Forecasts Actually Assume
CRA International's current analyst script rests on a specific set of numbers that you can test against your own expectations for the firm.
Forecasts point to 4.3% yearly revenue growth over the next three years, paired with profit margins that analysts see moving from 6.2% today to 8.0% by 2029. On earnings, the consensus view is that profit could reach US$72.1 million by about 2029, compared with US$49.2 million today, with the most optimistic projections going as high as US$80.8 million.
The gap between current and projected profit is sizeable in dollar terms. Moving from US$49.2 million of earnings today to US$72.1 million by the forecast horizon implies an increase of roughly US$22.9 million, before even considering the higher end of the range. That sort of step up is what underpins the higher management outlook and the premium multiple the stock currently commands.
On the top line, analysts who support the raised expectations are effectively underwriting a consulting platform that can compound revenue at a mid single digit clip while lifting margins as new hires and overseas offices mature. That is a very different story from a flat cash flow model, so it is worth checking whether the current mix of antitrust, M&A and sector projects you see in filings and commentary feels consistent with that 4.3% annual revenue pace.
Valuation work in the consensus models ties all of this to a 2029 snapshot that has CRA International generating US$902.9 million of sales and US$72.1 million of earnings, and trading on a P/E of 23.9x versus about 21.9x today and 21.6x for the wider US Professional Services group. That framework also assumes a modest yearly reduction in share count of around 4.35%, helped by buybacks, and uses a discount rate in the high 7% range to pull those future cash flows back to today.
These building blocks matter if you are weighing the newly raised internal outlook against external expectations. The models effectively ask you to be comfortable with mid single digit revenue growth, improved profitability, steady share reduction and a slightly higher future P/E multiple than both the stock's current level and the sector average.
CRA International's narrative projects US$902.9 million revenue and US$72.1 million earnings by 2029. This setup assumes 4.3% yearly revenue growth and an earnings increase of about US$22.9 million from US$49.2 million today.
Uncover how CRA International's fair value indicates a 25% potential upside to its current price before the market closes that valuation gap.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span a wide band, from about US$250.5 to roughly US$797.1, which illustrates the range of views on CRA International. Those retail investors are not factoring in the recent guidance hike, so you may wish to weigh their optimism against current risks related to M&A volumes, senior hiring costs, and rising debt, and then review additional Community viewpoints before forming your own stance.
Explore another CRA International fair value estimate, including one that suggests as much as 298% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CRA International research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for CRA International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CRA International's overall financial health at a glance.
Looking for more investment ideas beyond CRA International?
If the CRA International story has sharpened your thinking, you can use that same lens on a broader watchlist. The Simply Wall St Screener lets you quickly filter for balance sheet strength, valuation, and income potential so you can build a lineup that fits your own approach rather than copying anyone else's playbook.
- For investors who want income that can complement total return, review 5 dividend fortresses and see which companies align with your yield and stability preferences.
- If capital preservation sits high on your priority list, start with a 30 resilient stocks with low risk scores that scores well on resilience and financial reliability.
- When you care most about durable finances backing the equity story, focus on businesses from the list of solid balance sheet and fundamentals (24 results) to spot candidates with robust fundamentals supporting their operations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com