


Earnings event puts Republic Bancorp in focus
Republic Bancorp (RBCA.A) just posted third quarter 2026 earnings, reporting net interest income of US$85.67 million and net income of US$31.07 million. The results kept the spotlight on its regional banking model.
The announcement on 23 October also detailed nine month figures, with net interest income of US$257.83 million and net income of US$106.51 million, while the share price reaction stayed relatively muted.
Recent trading shows that Republic Bancorp’s share price has dipped 3.12% over the past month and 8.98% over the last quarter, even as the year-to-date share price return sits at 34.69% and the 3-year total shareholder return reaches 127.44%. This suggests that long-term momentum remains firm while near-term sentiment cools after the earnings release and ongoing caution around regional banks.
Seize this moment of mixed sentiment around Republic Bancorp to size up other financially resilient banks through our curated list of solid balance sheet and fundamentals (24 results).Bulls see Republic Bancorp as a solid regional bank whose earnings and net interest margin conflict with the recent share price dip. Bears point to regional bank risk and product mix. Which story do the current valuation markers echo?
Preferred P/E of 13.9x: Is it justified?
Valuation markers on Republic Bancorp are mixed. The shares closed at $91.60, trade at a P/E of 13.9x, and are flagged as trading 36.1% below an estimated fair value, which points to a gap between price and some valuation models.
The P/E ratio measures how much investors are currently paying for each dollar of earnings. For a regional bank like Republic Bancorp, it helps you compare what the market is willing to pay for its profit stream versus both its peers and what regression based models suggest could be a more neutral level.
On one side, Republic Bancorp is described as good value when stacked against a peer average P/E of 20.9x, which indicates the stock is priced lower than similar banks relative to earnings. On the other side, the same 13.9x multiple is labelled expensive compared with the broader US Banks industry average of 11.5x. A fair P/E derived from the SWS fair ratio framework sits at 11x, a level the market could move towards if sentiment cools further.
Explore the SWS fair ratio for Republic Bancorp.
Result: Price-to-Earnings of 13.9x (OVERVALUED)
Still, Republic Bancorp’s exposure to regional banking sentiment and its reliance on fee driven segments such as tax refund and payment solutions could unsettle that valuation story.
Find out about the key risks to this Republic Bancorp narrative.
Another view on Republic Bancorp’s value
The P/E discussion paints Republic Bancorp as slightly rich on earnings multiples, yet the SWS DCF model points the other way. With the stock at $91.60 and an estimated future cash flow value of $143.25, this framework suggests the shares may be undervalued. Which lens do you trust when the signals split?
Look into how the SWS DCF model arrives at its fair value.
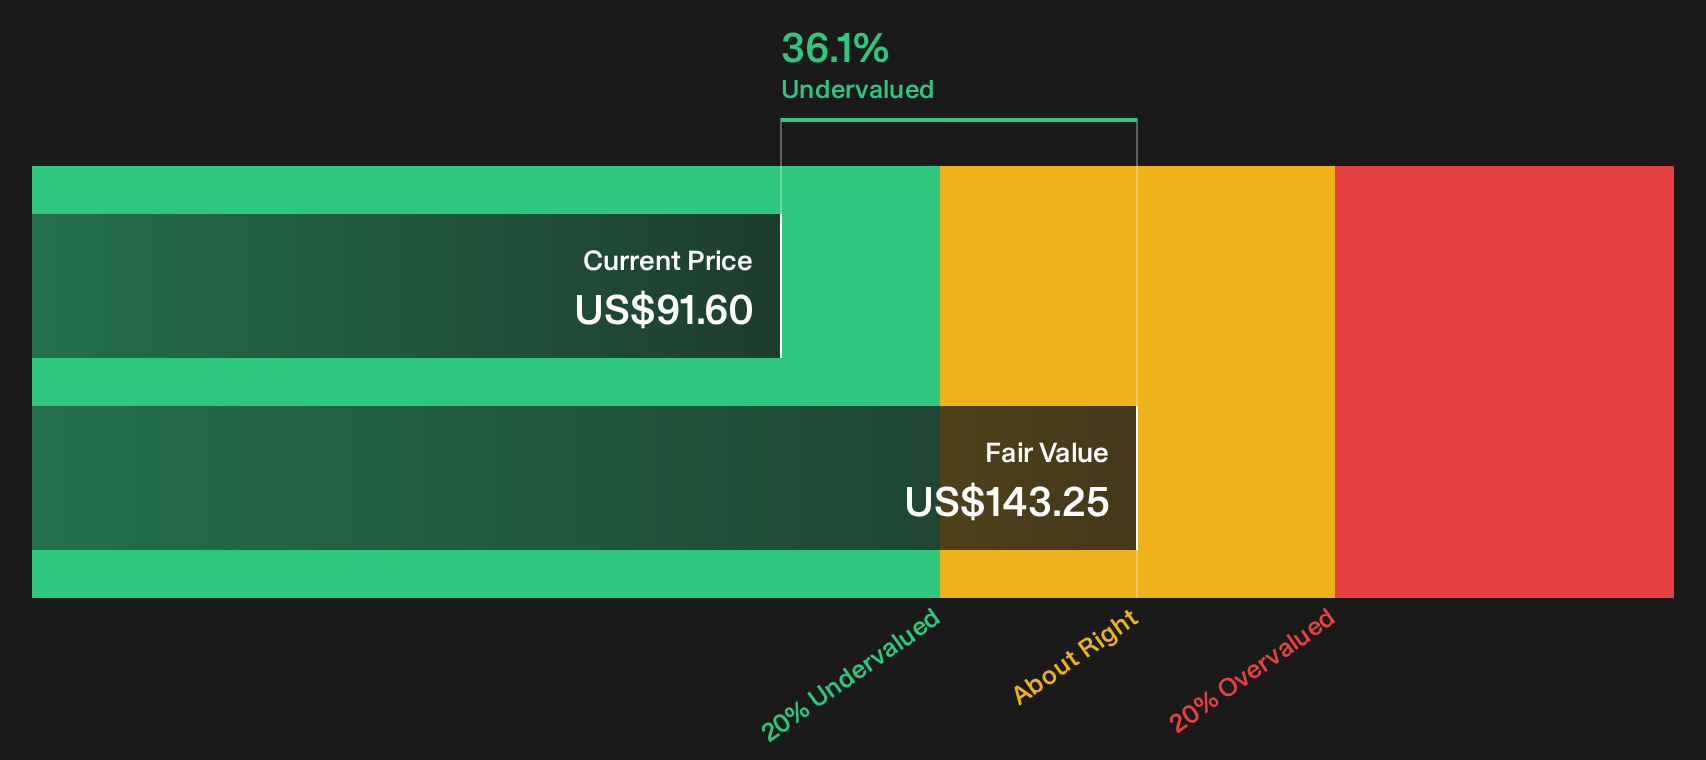
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Republic Bancorp for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment on Republic Bancorp split between value signals and risk checks, this is a good time to examine the full picture yourself and act promptly while others hesitate. To see which positive factors are attracting attention right now, review the 4 key rewards
Looking for more investment ideas beyond Republic Bancorp?
If you stop with Republic Bancorp, you might miss out on other opportunities that fit your style, risk comfort, and income goals just as well.
- Target potential mispricing by scanning a curated set of companies screened as higher quality and priced for value through the 28 high quality undervalued stocks.
- Lock in income-focused candidates by reviewing a focused group of higher yielding payers via the 5 dividend fortresses.
- Prioritize resilience by checking a carefully filtered 30 resilient stocks with low risk scores that highlights stocks with more robust risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com