


MIT Federal Credit Union partnership expansion puts Upstart in focus
MIT Federal Credit Union is expanding its relationship with Upstart Holdings (UPST) into indirect auto lending, adding a secured product that broadens both partners' reach across member borrowing needs.
This fresh step builds on their 2024 personal lending tie-up and gives investors another concrete data point on how Upstart is pursuing growth across different lending segments.
Recent trading in Upstart Holdings has been choppy. The share price is US$23.78 after a 7 day share price return of 2.28%. However, the year-to-date share price return is down 48.12%, and the 1 year total shareholder return has declined 54.91%. Short-term momentum has picked up, while longer-term performance remains under pressure.
Scan how Upstart Holdings compares to other lenders leaning into AI driven credit models with our curated list of 39 profitable AI stocks that aren't just burning cash.
With Upstart Holdings now partnering on both personal and secured auto loans, the share price slide and recent bounce raise a sharper issue: Does the current valuation still skew the risk reward toward buyers?
Most Popular Narrative: 38% Undervalued
Analysts following Upstart Holdings see a fair value of $38.38 against the last close at $23.78, which points to a sizeable gap that the market has not closed. That gap hinges on whether the current lending partners, product mix, and funding model can support the growth and margin profile baked into their forecasts.
Upstart's HELOC product growth, driven by conversion improvements, cross-selling, and state expansion, positions it well for future revenue growth and margins with the potential to leverage its strong relationships with banks and credit unions for cost-effective funding.
Increased automation and personalization in servicing operations have reduced costs and improved borrower outcomes, which will likely improve net margins through operational efficiencies and lower default rates.
See why 143 investors see Upstart Holdings as 38% undervalued.
Result: Fair Value of $38.38 (UNDERVALUED)
Still, the bullish narrative around Upstart Holdings quickly runs into two pressure points: model accuracy during credit stress, and ongoing questions about funding capacity and balance sheet risk.
Find out about the key risks to this Upstart Holdings narrative.
Another View: Upstart Holdings Through The P/E Lens
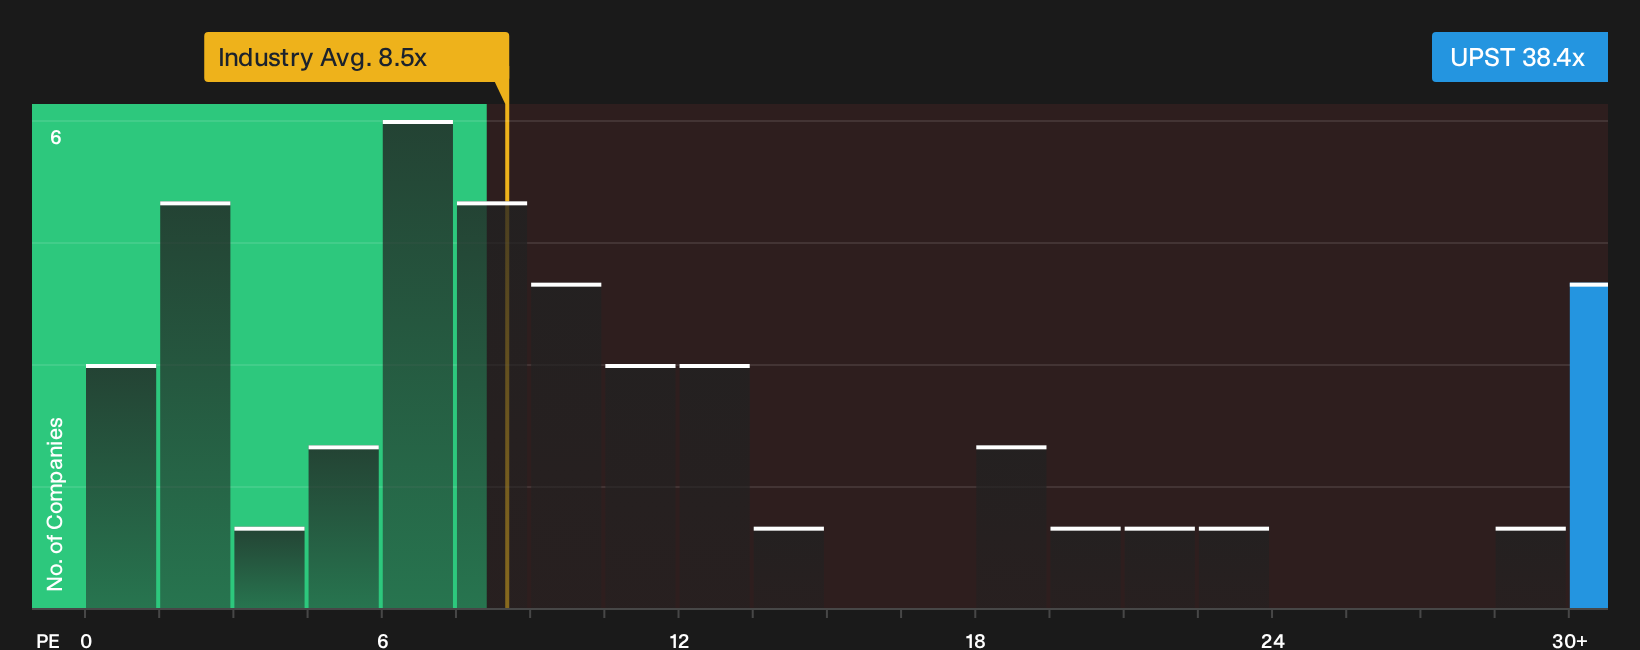
The SWS DCF model points to Upstart Holdings trading well below an estimated future cash flow value of $66.76, which supports an undervalued label. The market is not pricing it that way on earnings. The current P/E of 38.4x is higher than the US Consumer Finance industry at 8.5x, the peer average at 11.8x, and even the 34.8x fair ratio that the market could move toward. That gap raises a simple question for investors: Is this a mispriced opportunity or just a richer risk profile being correctly charged for?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Upstart Holdings can be useful if you use them as a prompt instead of a verdict. Pressure test the numbers and sentiment yourself, then weigh up the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Upstart Holdings?
If Upstart Holdings has your attention, a broader watchlist can sharpen your next move. Use these tools to pressure test where your capital goes next.
- Target resilience by focusing on businesses that pair healthy finances with low-risk profiles through the 30 resilient stocks with low risk scores.
- Spot potential value by scanning companies that combine quality fundamentals with prices that may not fully reflect them using the 28 high quality undervalued stocks.
- Hunt for overlooked opportunities by filtering for fundamentally strong but less followed stocks via the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com