


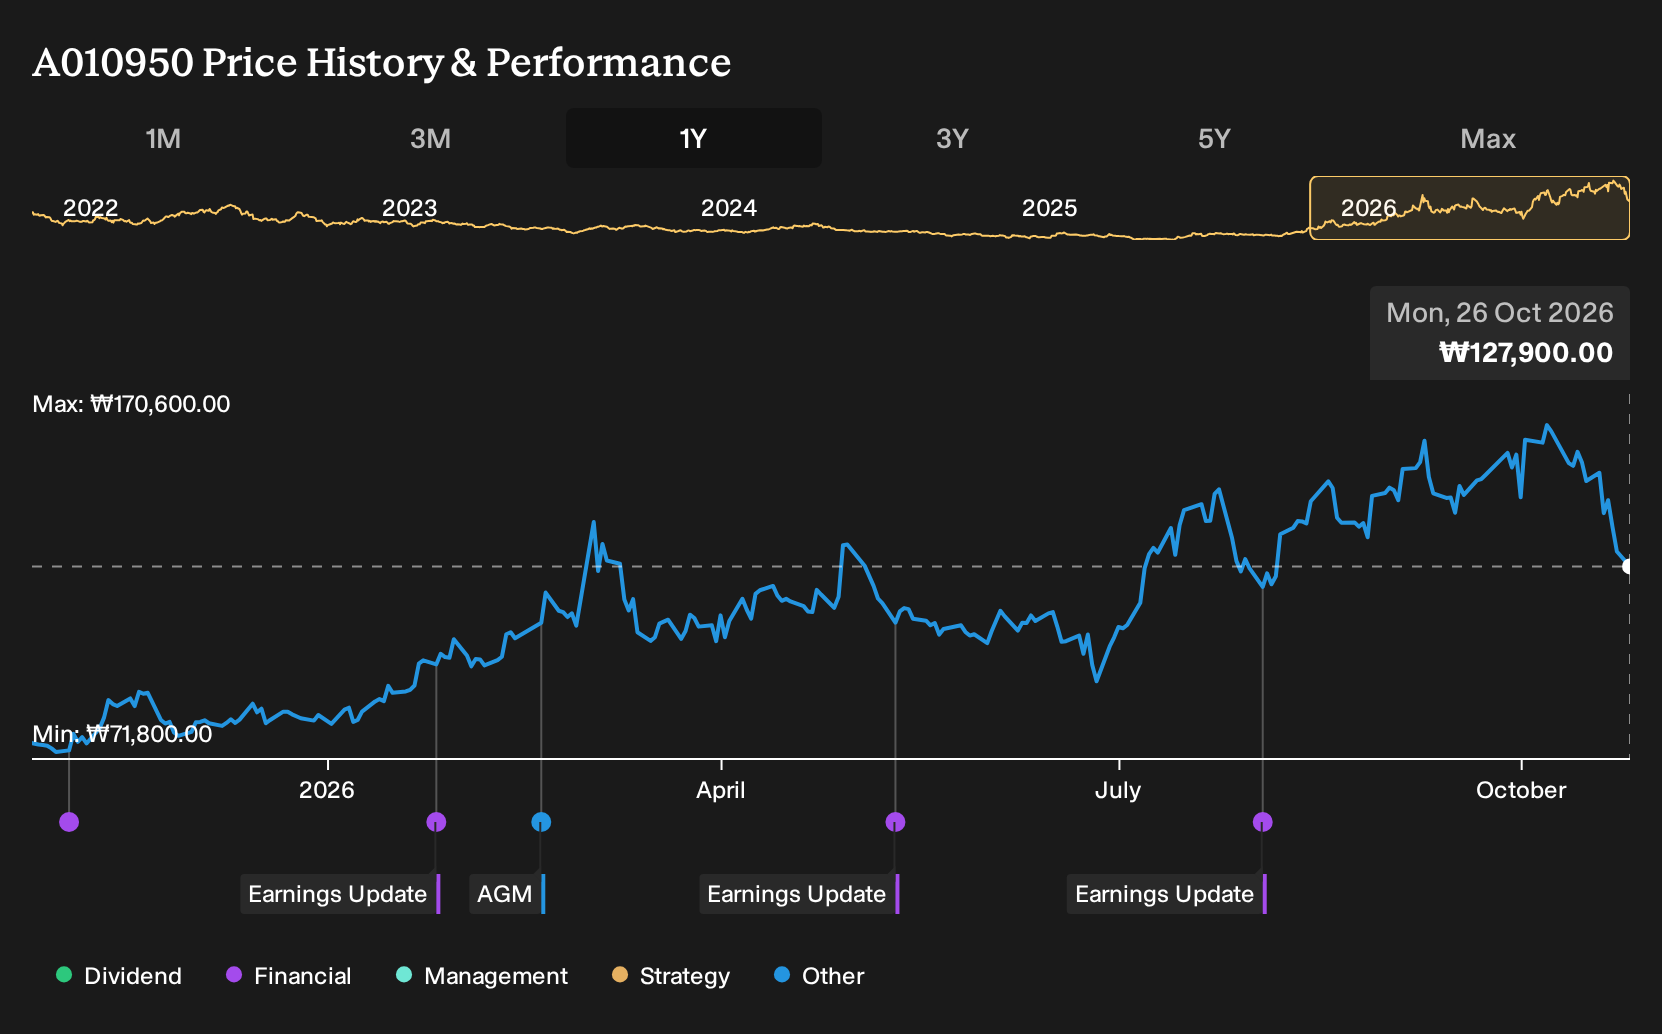
If you only glanced at S-Oil’s headlines a year ago, the debate looked fierce. Bulls pointed to the Shaheen Project and self-power upgrades, while bears warned that rising carbon costs and weaker fossil demand could crush future returns. For S-Oil shareholders, the return over the past year was 74.1%, including dividends. If you had been weighing those June 2025 reports at the outset, what in that split view really mattered most?
S-Oil has already moved. See which of 196 high quality undervalued stocks still trade below our estimates.
The Two S-Oil Stories Investors Had To Price In
The shares cost ₩74,700 at the start of the period, and anyone looking at S-Oil back then had to choose which future sounded more plausible.
The bullish story argued that the Shaheen Project and energy self-sufficiency could lift profitability, so a Fair Value of ₩90,000, the price implied if those upbeat assumptions played out, looked reasonable. That view leaned on expected revenue growth of 3.5% a year and profit margins rising from a loss of 1.3% to 5.2%.
The bearish version focused on rising carbon costs and weaker demand, anchoring to a Fair Value of ₩52,000 based on tougher assumptions. This camp expected revenue to fall 6.3% a year, even if profit margins only moved from a 1.3% loss to a slim 0.5% profit.
What The Results Changed For The S-Oil Debate
The clearest new fact was S-Oil’s swing in profitability. Net income moved from a loss of ₩66,782m in Q2 2025 to a profit of ₩514,584m in Q2 2026, and net margin shifted from -0.8% to 4.5%. That supported the optimistic view on margins, even though revenue only moved from ₩8,048,504m to ₩11,343,488m. As a result, the broader argument still looks only partially settled.
The key lesson is about which promise to test. When a thesis hangs on better profitability, it is important to focus on whether net margin and absolute earnings move together in filings, rather than only watching top-line forecasts or headline projects.
What S-Oil’s 74% Run Still Leaves You Paying For
S-Oil trades at ₩127,900 today, after a 74.1% total return over the past year, and the selected Narrative’s Fair Value sits above that market level.
The Narrative focuses on tight refining and high value Group III lube exposure, along with Shaheen execution and post capex cash generation. It argues that today’s price still does not fully reflect those future cash flow assumptions.
"Analysts expect S-Oil to convert tight global refining and lube markets, the high Group III base oil mix, and improved export economics into stronger through-cycle earnings that support the view that the business is undervalued. The main requirement is successful Shaheen execution, with mechanical completion, commissioning, and early 2027 commercial operation translating into the cost competitive, integrated petrochemical platform management describes, while the balance sheet stays within the targeted net debt-to-equity range."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
How Could You Get There Earlier?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 43% below our estimate - develops lifestyle-focused sports apparel lines from an earlier underwear core.
- Company 2 - 31% below our estimate - grows store and online electronics sales as technology upgrades and footprints deepen.
- Company 3 - 18% below our estimate - increases supplement output while adding distributors targeting wellness-oriented retail channels.
Those are three of them. See the full list of 207 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com