


Recent sanctions concerns around Polar Train LNG projects have pushed Capital Clean Energy Carriers (CCEC) into the spotlight, just as its board affirmed a US$0.15 per share cash dividend for the third quarter of 2026.
The dividend call lands after a choppy stretch for Capital Clean Energy Carriers, with the share price at US$20.27 and a 7 day share price return of 3.21%, following a 30 day decline of 6.80% that mirrors a softer 90 day slide of 10.55% as sanctions headlines and LNG trade questions reshaped risk expectations.
Scan beyond Capital Clean Energy Carriers to see how other LNG exposed transport stocks with resilient metrics are lining up in the list of solid balance sheet and fundamentals (24 results) list.
After a sharp three month slide followed by a short bounce and a fresh US$0.15 dividend, Capital Clean Energy Carriers now presents a clearer question: does this mix of income and LNG risk still reward new buyers on the numbers ahead?
Most Popular Narrative: 22% Undervalued
Against a last close of $20.27, the most followed narrative for Capital Clean Energy Carriers points to a fair value of $25.83. The debate now centers on whether its contracted fleet and LNG exposure justify that gap.
The build out of CCEC’s gas focused fleet, including new LNG, LPG and LCO₂ carriers that increased total assets to about US$4.7b and fixed assets to about US$4.3b by mid 2026, adds contracted days backed by a charter backlog of roughly US$2.8b to US$2.9b. This can support future revenue and cash flow that investors may not fully price in today.
See why 1 investors see Capital Clean Energy Carriers as 22% undervalued.
Result: Fair Value of $25.83 (UNDERVALUED)
Still, that bullish fair value story for Capital Clean Energy Carriers leans heavily on a large charter backlog and a vessel build program that both rely on steady funding and manageable interest costs. If leverage climbs faster than expected or floating rate debt bites harder into earnings, the narrative could shift quickly.
Find out about the key risks to this Capital Clean Energy Carriers narrative.
Another View: SWS DCF Model Puts A Brake On The Bull Case
The first narrative tags Capital Clean Energy Carriers as undervalued at a fair value of $25.83. The SWS DCF model tells a cooler story. On a future cash flow value of $18.38, the shares at $20.27 screen as overvalued instead. Which lens do you trust when cash flows and contracts pull in different directions?
Look into how the SWS DCF model arrives at its fair value.
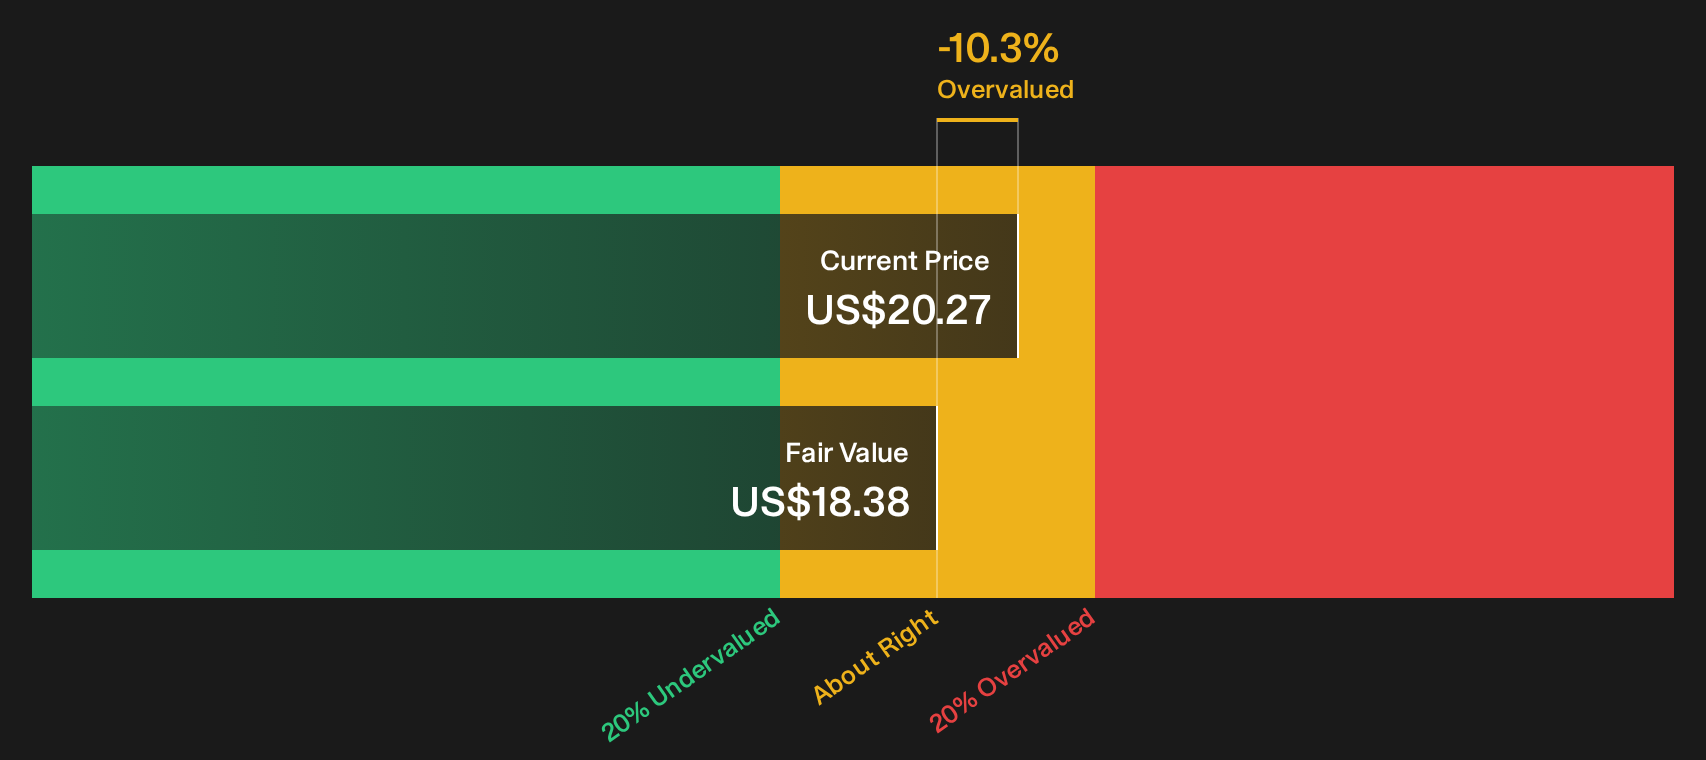
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Capital Clean Energy Carriers for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Capital Clean Energy Carriers, from dividend income to LNG exposure and valuation splits, mean you need to move quickly and test the data yourself. Weigh the upside potential against the pressure points by checking the 4 key rewards and 3 important warning signs
Looking for more investment ideas beyond Capital Clean Energy Carriers?
If Capital Clean Energy Carriers has your attention, do not stop here. Use the broader market to spot fresh setups and keep your watchlist working hard.
- Target income resilience by reviewing companies with robust payouts in the 5 dividend fortresses that might complement a position in energy shipping.
- Tilt your portfolio toward quality by checking the 30 resilient stocks with low risk scores that screens for businesses with steadier risk profiles and fewer financial red flags.
- Hunt for future market leaders early through the 21 high quality undiscovered gems before attention and liquidity push valuations higher.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com