


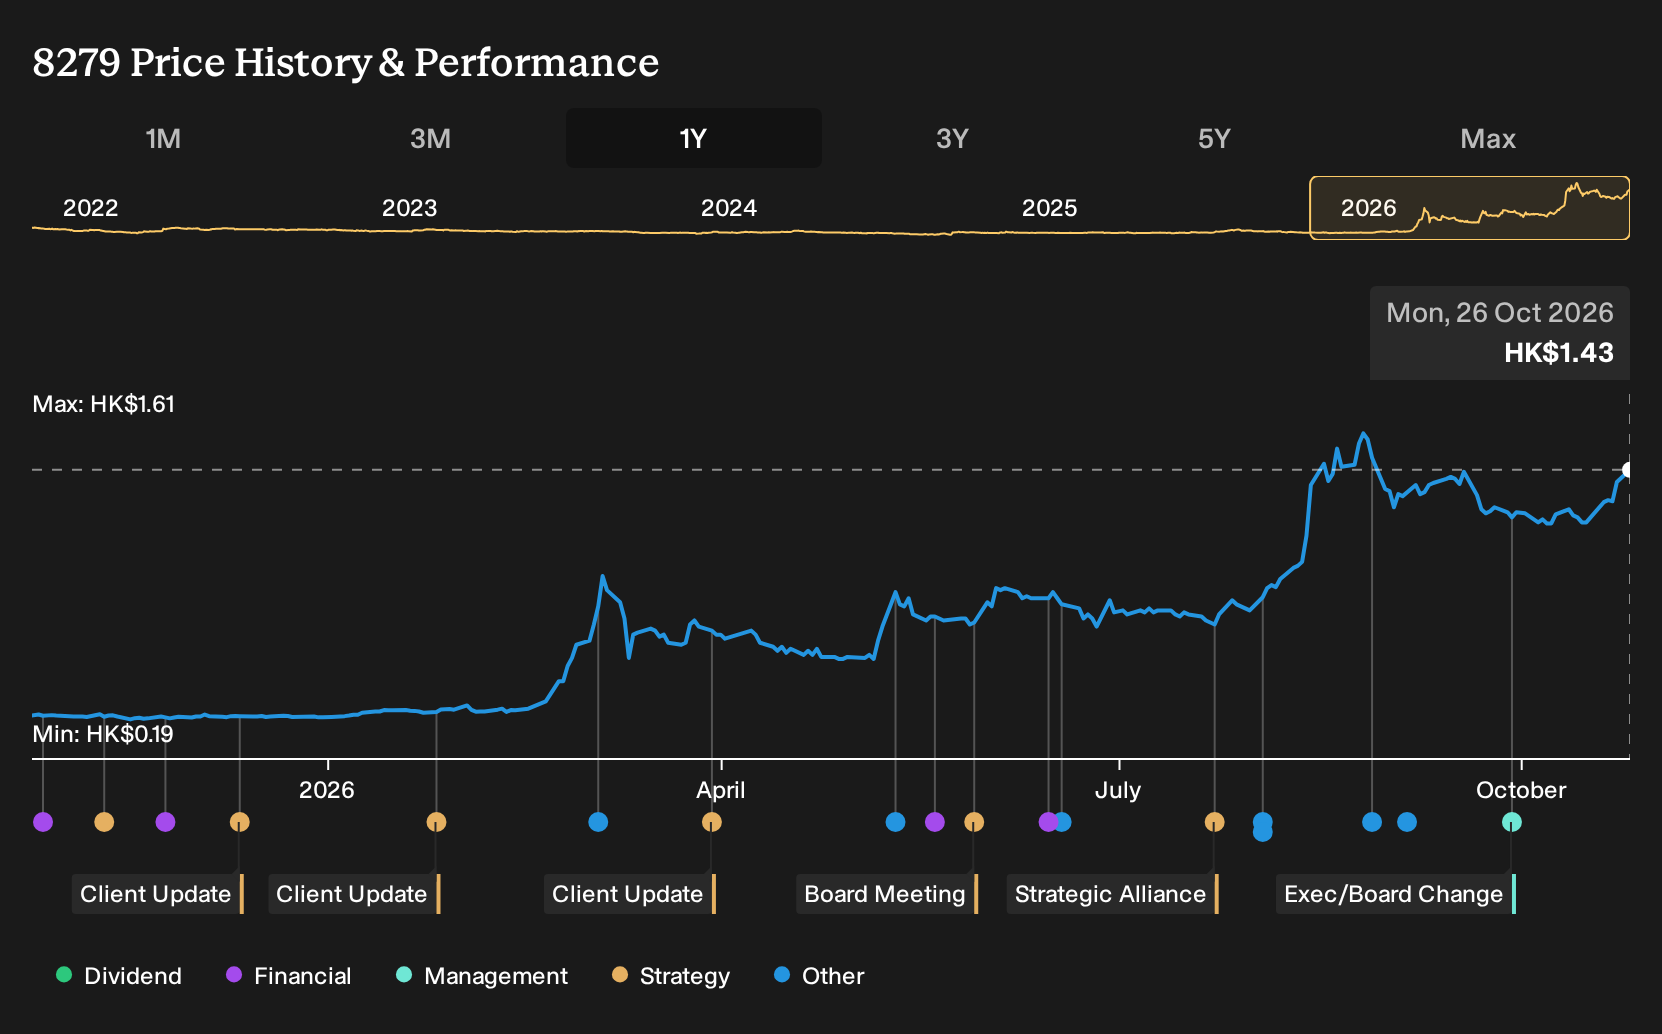
- AGTech Holdings is drawing interest after its share price moved sharply this year, with the stock now trading at a P/S ratio well above the industry average despite current sales levels.
- The unusually high P/S premium puts a spotlight on the quality of AGTech Holdings' revenue base and whether its business model can support such optimistic expectations.
- We will now explore how AGTech Holdings' investment narrative is affected by this stretched price to sales multiple and investor optimism.
Compare AGTech Holdings' sharp rerating with other potential high-premium stories by scanning a curated set of 610 high quality undiscovered gems that may not yet be priced for perfection.
What Is AGTech Holdings' Investment Narrative?
To own AGTech Holdings at this valuation, you effectively have to believe its mix of digital payments, full scale banking services and lottery hardware can turn a HK$760.5m top line into durable profitability. The group still reports a loss of HK$39.7m, and return on equity is negative, so the story hangs on execution, operating efficiency and the ability to monetise its Macau and Mainland China footprint without needing heavy new capital.
The recent surge in AGTech Holdings' share price does not change those fundamentals, but it does compress the margin for error on near term catalysts. Volatile trading over the past three months, a P/S multiple of 21.9x versus sector averages, higher risk funding that leans on external borrowing and CEO pay rising while the business is unprofitable all mean sentiment is now a key driver as much as operations.
That said, alongside the optimism around payments and banking scale up, there is a less comfortable angle that centers on ...
There's only one way to know the right time to buy, sell or hold AGTech Holdings. Head to Simply Wall St's company report for the latest analysis of AGTech Holdings's Fair Value.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your AGTech Holdings research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for AGTech Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AGTech Holdings' overall financial health at a glance.
Looking For More Ideas Beyond AGTech Holdings?
If AGTech Holdings has prompted you to reassess what you want from a position in your portfolio, it can be useful to line it up against a wider pool of opportunities using the Simply Wall St Screener.
- If resilience matters most to you, scan for companies with steadier profiles and lower risk scores through the 223 resilient stocks with low risk scores.
- For investors focused on stronger balance sheets and fundamentals, compare AGTech Holdings with a list of solid balance sheet and fundamentals (207 results) that already clear higher financial quality bars.
- If you are hunting for mispriced potential, broaden your watchlist with a 610 high quality undiscovered gems that may not yet be in the spotlight.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com