


Seagate Technology Holdings has delivered very strong share-price gains over the past few years, helped by rising interest in high-capacity storage for AI and cloud workloads. This raises a straightforward question for anyone looking at the stock today: Is the current valuation still grounded in the earnings the business is producing and expected to generate?
- The share price has risen about 8.8x over the past 3 years, which puts a lot of focus on whether Seagate's earnings profile can support that kind of re-rating.
- Recent news around demand for hard disk drives in data centers and the rollout of Seagate's HAMR based Mozaic drives points to expectations for higher capacity shipments and potentially stronger earnings power over time, which can feed directly into what investors are willing to pay per dollar of profit.
- There is a second opinion on Seagate Technology Holdings worth weighing. See what analysts think Seagate Technology Holdings's shares could be worth.
The issue now is whether Seagate's current share price is appropriately aligned with its earnings when judged against the Fair Ratio benchmark.
To see whether Seagate Technology Holdings' AI storage story and earnings test applies elsewhere in your portfolio, compare it with other 55 AI infrastructure stocks
Does Seagate Technology Holdings Look Undervalued on Earnings?
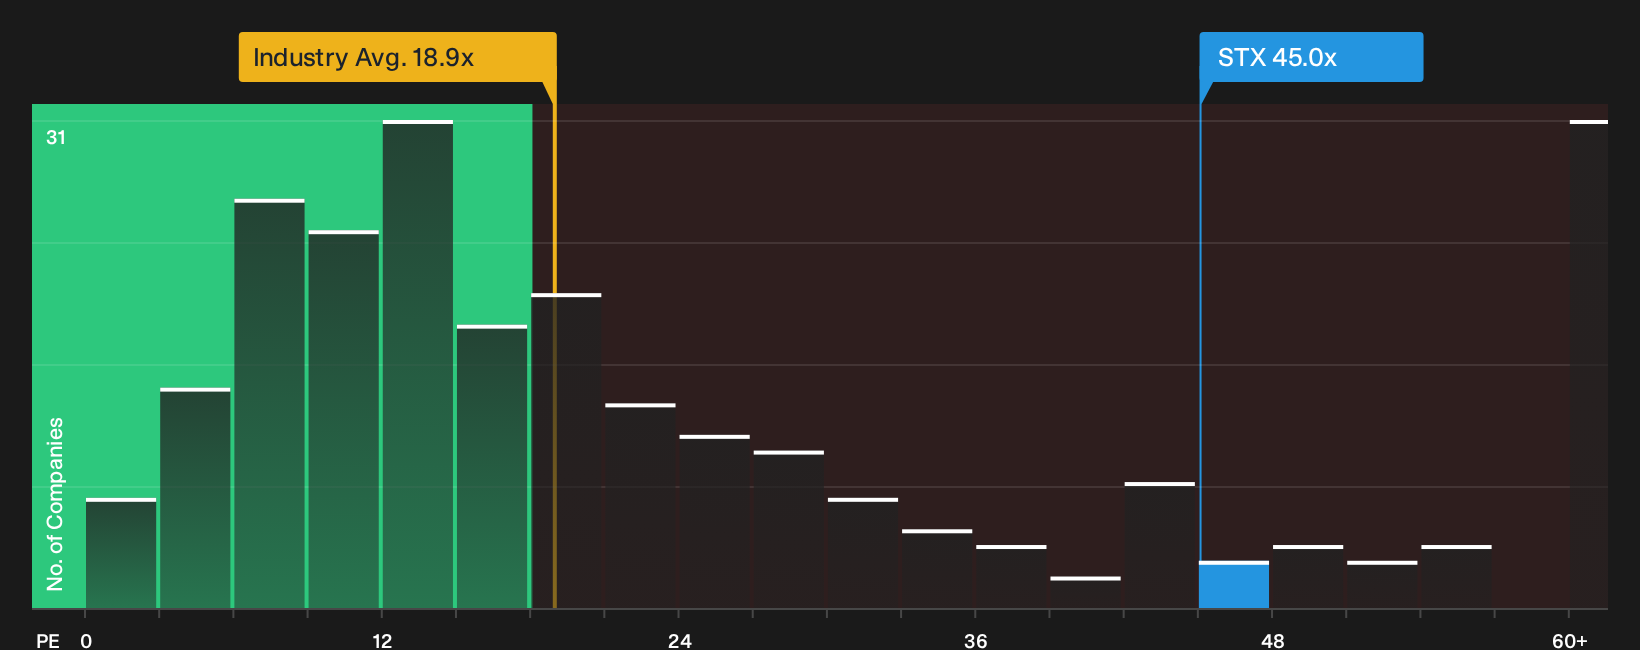
The P/E ratio is a useful lens for Seagate Technology Holdings because earnings tend to matter more than sales or book value for mature hardware suppliers. Seagate trades on a P/E of 45.0x, which is more than double both the Tech sector average of 18.9x and the peer group on 20.6x, so the market is clearly putting a rich price on each dollar of reported profit.
That premium screens as undervalued against a Fair Ratio that blends Seagate's growth profile, margins, size and risk into a tailored benchmark, since the current P/E sits below what that framework implies investors might typically pay. Because recent enthusiasm around Mozaic HAMR drives and stronger AI storage demand has already pushed expectations higher, this gap suggests the stock still prices in less earnings strength than the model would point to if those fundamentals fully flowed through. Explore the numbers behind Seagate Technology Holdings's P/E valuation.
The Seagate Technology Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Seagate Technology Holdings link the valuation puzzle above with explicit scenarios that spell out which earnings, growth and margin paths would need to play out for the current share price to look meaningfully high or low. Each narrative anchors its figure to a clear view on how Seagate Technology Holdings' growth, profitability and risk profile might evolve, giving you something concrete to revisit as fresh information comes through.
One of the top community narratives on Seagate Technology Holdings: 46% undervalued
HAMR increases the number of terabytes on each platter, which cuts components and labour per exabyte shipped and reshapes Seagate’s cost curve...
Discover why this Narrative puts Seagate Technology Holdings at 46% undervalued.
Seagate Technology Holdings: What Do The Risk Checks Reveal?
Valuation only tells part of the story for Seagate Technology Holdings, since our broader review has also surfaced potential concerns that could matter just as much to your thesis. Take a closer look at 2 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com