


BioNTech has seen its share price retreat sharply in recent years, and that pullback raises a straightforward question for investors who care about fundamentals. Is the current market value of the stock really aligned with the revenue the business is generating today and what that sales base can realistically support over time?
- The share price is down 67.6% over the past 5 years. This puts the spotlight on whether earlier expectations for BioNTech’s sales are now being reset enough, or not at all, in the valuation.
- Fresh trial results across lung and breast cancer programs, including both encouraging data and a setback in head and neck cancer, can shift how investors think about the company’s future product mix and the level of sales that might eventually need to justify today’s market price.
- There is a second opinion on BioNTech worth weighing. See what analysts think BioNTech's shares could be worth.
The issue now is whether the current BioNTech share price can be squared with the revenue base investors are effectively paying for at today’s P/S multiple.
If you are weighing whether BioNTech’s recent trial headlines justify its current P/S level, it can help to compare that sales story with companies in the same valuation bucket through 28 high quality undervalued stocks
Has BioNTech Run Too Far on Sales?
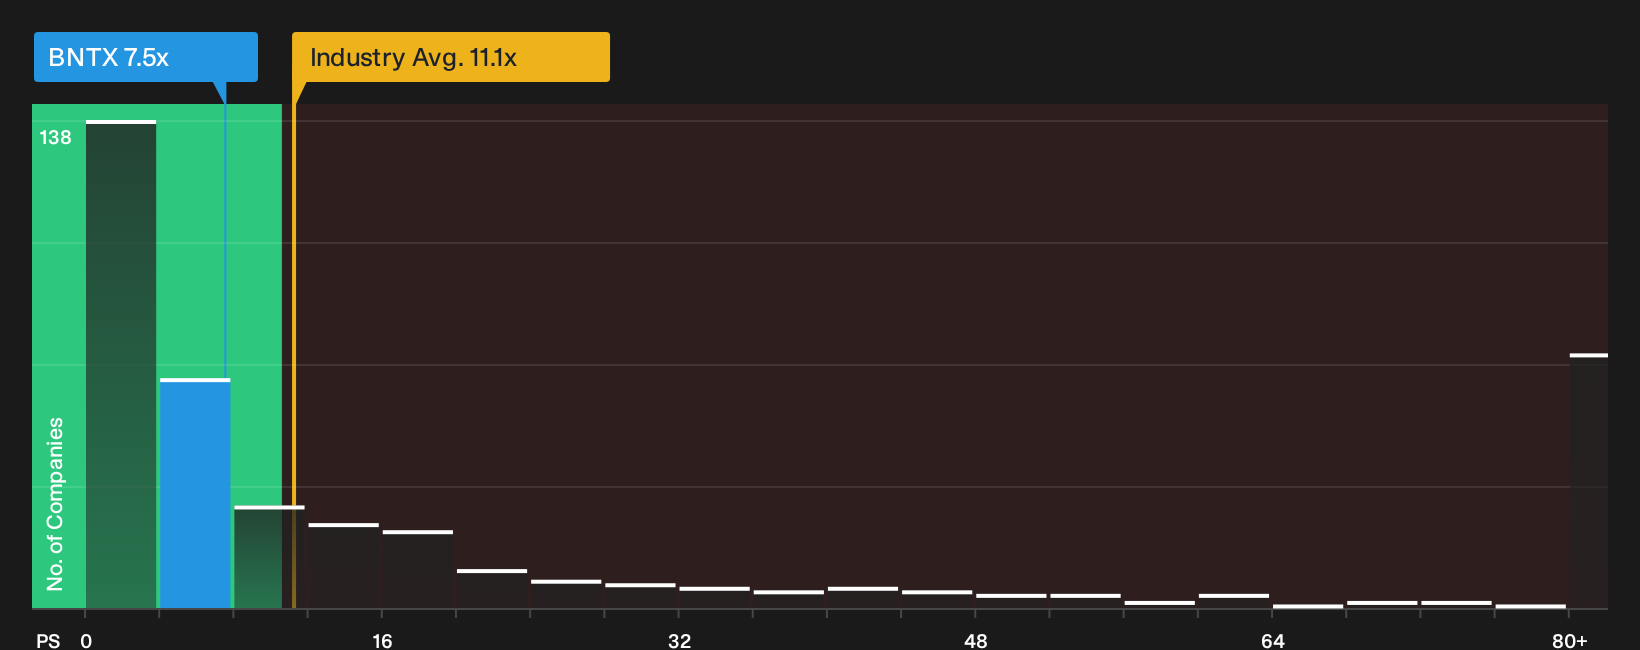
P/S is a useful lens for BioNTech because the business is still heavily defined by its revenue base rather than consistent earnings. The current P/S multiple sits around 7.5x, which is above the peer group average of roughly 5.6x yet below the broader biotech sector at about 11.1x. That puts the stock in an awkward middle ground where investors are paying more than similar companies but not a clear premium to the whole industry.
The fair multiple implied by BioNTech’s own profile is lower than where the shares trade today, which points to the stock looking overvalued on this measure. Because the recent lung and breast cancer trial updates highlight both promising data and ongoing clinical risk, the market is effectively pricing a relatively rich sales tag while the future mix of that revenue stream is still being worked out. If you want to see how large that gap is, and how it compares across similar biotechs, it is worth checking the detailed multiple workup through. Explore the numbers behind BioNTech's P/S valuation.
The BioNTech Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where BioNTech's valuation puzzle leaves off by spelling out which paths for growth, profitability and earnings would need to play out for the shares to be worth meaningfully more or less than today. Each scenario links its number to a specific view on how BioNTech's growth, margins and risks might evolve, giving you a concrete reference point you can return to as fresh trial data and financial updates arrive on the Community page.
Community views on BioNTech are split between those who see an oncology backed reset and those who think vaccine erosion and execution risk still weigh too heavily.
Bull case: 25% undervalued
"Expansion of BioNTech’s late stage oncology pipeline, including pumitamig, gotistobart and multiple ADCs such as T PAM and elfetabart drozuntecan, increases the chance of future product approvals that could add new revenue streams…"
Discover why this Narrative puts BioNTech at 25% undervalued.
Bear case: 13% overvalued
"Although BioNTech is reallocating capital from COVID-19 towards oncology, the termination of the autogene cevumeran adjuvant colorectal cancer Phase II study after a numerical imbalance in deaths shows that clinical risk in mRNA cancer vaccines could still lead to further trial cancellations…"
Explore why this Narrative puts BioNTech at 13% overvalued.
BioNTech’s price is only one piece of the decision
Before acting on any view of BioNTech’s valuation, it is worth asking who is steering the business, how their incentives are structured, and whether that pay is aligned with your expectations as a shareholder. See who runs BioNTech and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com