


Equifax (EFX) reported higher third quarter revenue and earnings compared with a year ago, while at the same time trimming full year 2026 sales guidance because of continued weakness in the U.S. mortgage market.
The recent third quarter update and reduced 2026 outlook landed against a mixed share price backdrop for Equifax, with the stock rallying sharply in the last month, including a 30 day share price return of 23.1%, yet still sitting lower year to date. Over a longer horizon, total shareholder returns show a small gain of 14.0% over three years but a decline of 19.5% over the last 12 months, which points to momentum only starting to rebuild as investors weigh new product launches and earnings progress against weaker U.S. mortgage activity.
Spot opportunities around Equifax by scanning a curated 28 high quality undervalued stocks that currently combine earnings power with balance sheet strength.Equifax is delivering higher earnings while trimming guidance, which puts the spotlight firmly on the price investors now pay for that mix of progress and caution. Is the recent share price rebound already generous?
Most Popular Narrative: 6.5% Undervalued
Against Equifax's last close of $182.36, the most followed narrative pegs fair value at about $195.10, suggesting the recent rebound still prices the stock below that framework while markets wrestle with slower mortgage activity and tighter guidance.
Global cloud migration and proprietary AI platforms are now being used to double Equifax’s AI related productivity target to US$150m of run rate savings for 2026 to 2028. This directly supports EBITDA margin expansion above the 50 basis point long term leverage framework and adds to earnings capacity.
See why 30 investors see Equifax as 7% undervalued.
Result: Fair Value of $195.10 (UNDERVALUED)
Still, mortgage policy changes and ongoing litigation costs could chip away at Equifax’s earnings profile and challenge the idea that the stock is simply mispriced.
Find out about the key risks to this Equifax narrative.
Another View: What Equifax’s Valuation Signals
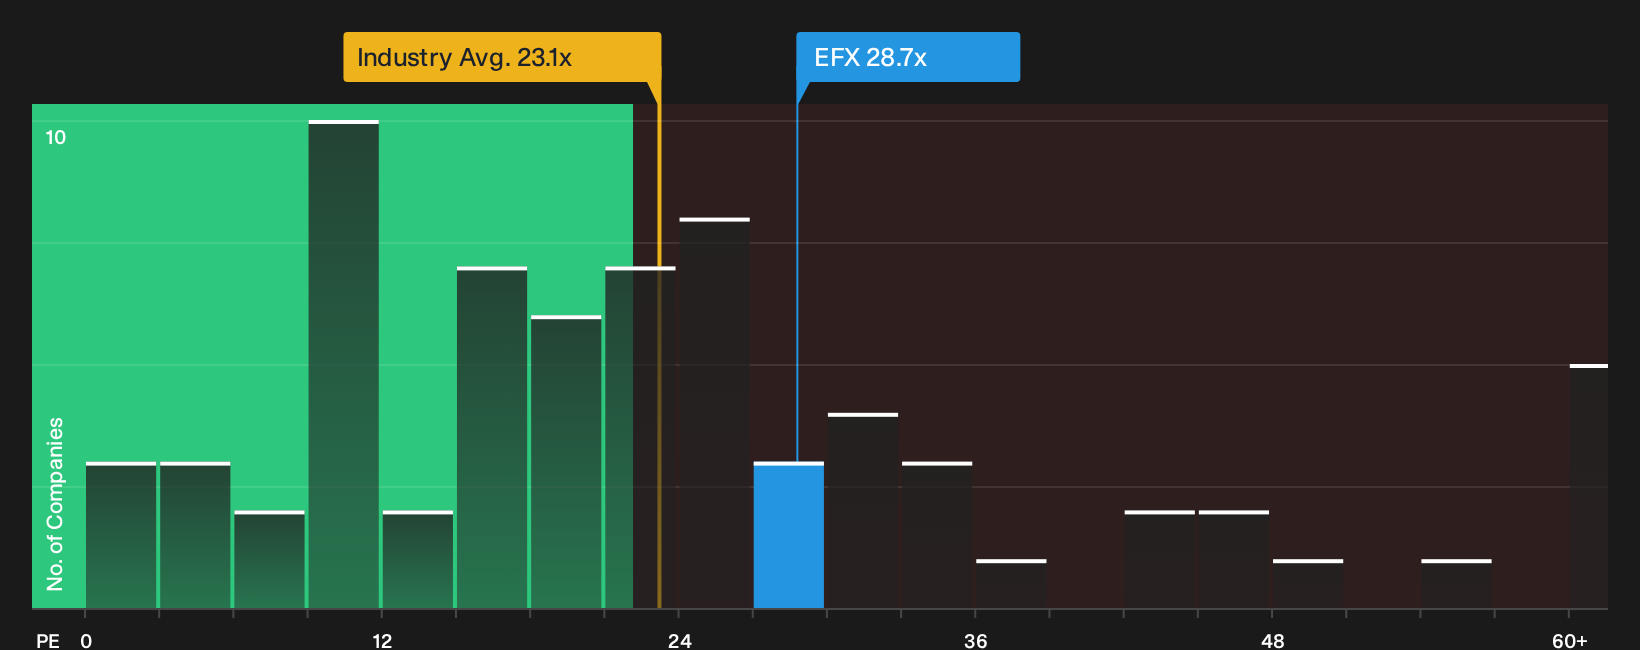
On price alone, Equifax tells a different story. The shares trade on a P/E of 28.7x, which is higher than the fair ratio estimate of 26.1x, above the US Professional Services sector at 23.1x, and above peer averages at 27.4x. That richer multiple suggests less room for error if growth or margins disappoint. Is this a quality premium or a valuation stretch investors need to factor in?
To see how that compares to a fuller valuation breakdown, including where the fair ratio could move over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Equifax is clearly split, with both pressure points and bright spots in view, so move quickly through the data and decide where you stand. To see the full balance of potential upsides and the key issues investors are worried about, review the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Equifax?
Do not stop with Equifax. Broaden your watchlist with fresh ideas that match different goals, whether you care most about price, resilience, or income strength.
- Target potential mispricings by scanning a 28 high quality undervalued stocks that focuses on companies combining strong fundamentals with room in their valuation.
- Strengthen portfolio resilience by using a list of solid balance sheet and fundamentals (24 results) to focus on businesses with sturdier finances and fewer funding pressure points.
- Turn your attention to income by reviewing a 5 dividend fortresses built around yields above 5% that still aim to keep stability in view.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com