


Sunrun has seen a sharp reset in its share price over recent years, and even with a recent bounce, the stock is still carrying deep long term losses. That kind of performance puts the focus squarely on one issue for investors: whether the current US$7.58 price is properly supported by the company’s earnings profile.
- Over the past 5 years, Sunrun’s share price has fallen 87%, which raises a basic question about how much of the business’s earnings power the market is now pricing in.
- Recent commentary from management has highlighted strong revenue growth and new monetization opportunities from the existing customer network, which can shape expectations for future profitability and the timing of any earnings improvement.
- There is a second opinion on Sunrun worth weighing. See what analysts think Sunrun's shares could be worth.
For investors, the debate is whether Sunrun’s current valuation is justified by what its earnings already show today rather than what the share price used to imply.
If you want to stress test the same earnings question that hangs over Sunrun against a broader set of opportunities, scan through the 28 high quality undervalued stocks
Is Sunrun a Bargain on Earnings?
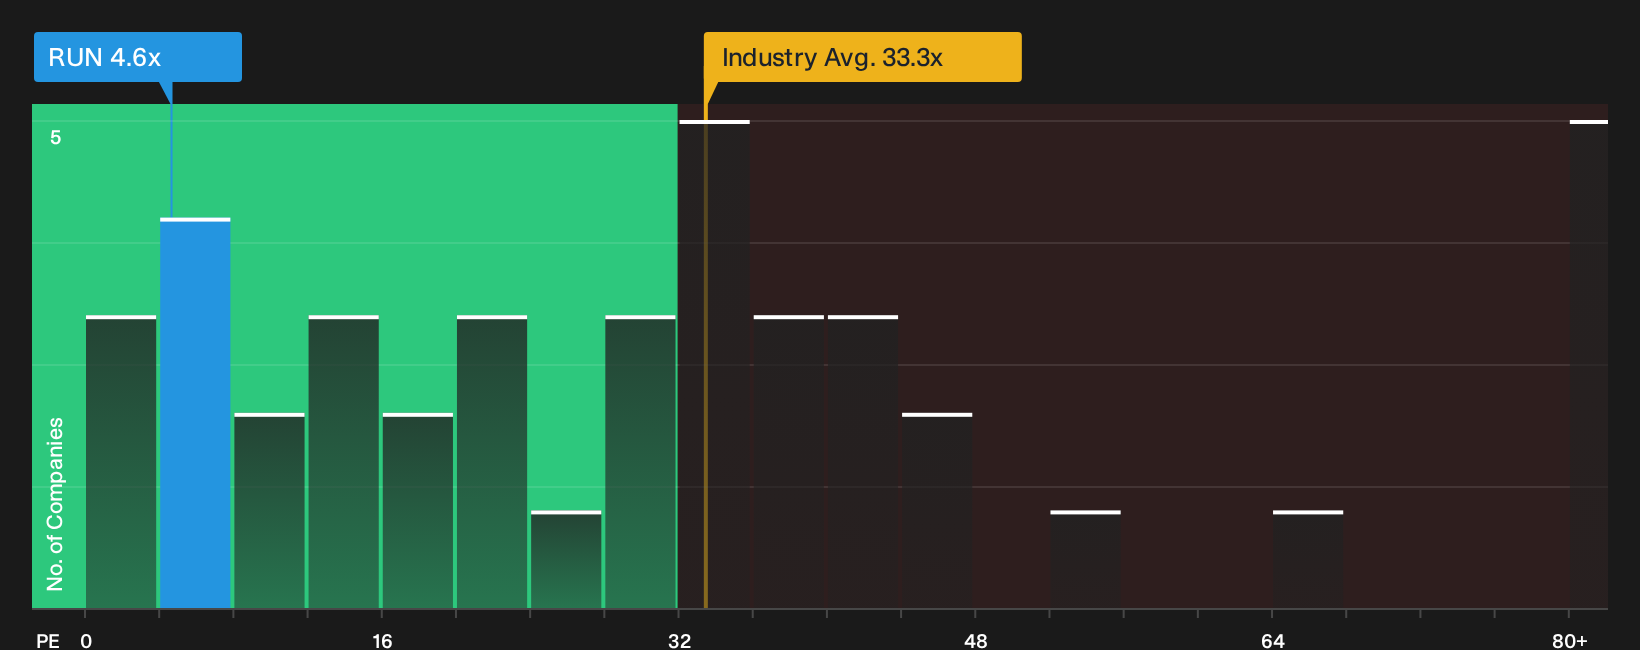
The P/E lens suits Sunrun because management and investors are heavily focused on when the business can translate its existing revenue base into consistent earnings. On this metric, the stock trades on a P/E of 4.6x, which is far below the Electrical industry average of 33.3x and well under the peer group on roughly 39.9x. Compared with a tailored fair multiple that reflects Sunrun’s own growth profile, margins, scale and risk, the current ratio appears undervalued rather than richly priced.
Because the latest quarter showed strong top line progress and better than expected earnings, the gap between Sunrun’s 4.6x P/E and broader sector valuations suggests the market is still applying a heavy discount despite those results. For you as a shareholder or potential buyer, the key question is whether that low earnings multiple reflects genuine long term risk or a valuation that has been pushed too far to the downside. Explore the numbers behind Sunrun's P/E valuation.
The Sunrun Narrative: What Would Justify Today's Price?
Sunrun’s Simply Wall St Narratives pick up where the valuation question leaves off by spelling out what assumptions on future growth, margins and earnings would need to hold for the current P/E to look cheap or stretched. Each scenario ties a fair value to a clear story about Sunrun's potential catalysts and key risks, so you can track which version of events appears closer to reality over time on the Community page.
Sunrun’s community views split between those who see a macro pressured financing story with upside optionality and those who focus on structural headwinds and a tighter ceiling on earnings power.
Bull case: 60% undervalued
"This perspective reframes Sunrun less as an energy company and more as a capital allocator operating within the energy transition..."
Discover why this Narrative puts Sunrun at 60% undervalued.
Bear case: 8% overvalued
"With falling net metering benefits, rising grid interconnection fees, and the growing commoditization of solar hardware, Sunrun will find it increasingly difficult to sustain pricing power..."
Explore why this Narrative puts Sunrun at 8% overvalued.
For Sunrun, the share price is only one piece of the real decision
Before making any call on Sunrun, it helps to ask who is actually steering the business, how their incentives are structured, and whether those rewards align with your own goals. See who runs Sunrun and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com