


Why Advance Auto Parts Is Back in Focus
Advance Auto Parts (AAP) is back on investors’ radars after years of share price pressure, as the stock now trades on a premium P/E multiple despite that longer term decline.
This disconnect between the five year share price slide and a richer earnings multiple has turned a routine valuation check into a fresh debate over whether today’s market price fairly reflects the retailer’s profit profile.
Over the past few weeks, Advance Auto Parts has seen momentum pick up, with a 7 day share price return of 7.37% and a 30 day gain of 12.44% pushing the stock to $46.92. This comes even though the 1 year total shareholder return is still down 14.94% and the 5 year total shareholder return has fallen 76.46%.
Compare this rebound in Advance Auto Parts with other potential valuation resets by scanning our hand picked 28 high quality undervalued stocks, which share a mix of earnings power and balance sheet strength.
Advance Auto Parts has already bounced off the lows, yet the five-year record and a richer P/E still pull in opposite directions. Is the meaningful upside now ahead of you, or already in the rear view mirror as you assess valuation next?
Most Popular Narrative: 6% Undervalued
Advance Auto Parts last closed at $46.92, which sits below the most followed fair value estimate of $49.95 that is based on a 12.54% discount rate. That gap has put fresh attention on whether the margin story backing that valuation still holds up.
The company is still working through a multi year plan to lift adjusted operating margin toward 7%, with recent guidance pointing to further margin expansion in 2027 that, if delivered, would continue to support net margins and earnings.
See why 12 investors see Advance Auto Parts as 6% undervalued.
Result: Fair Value of $49.95 (UNDERVALUED)
Still, the narrative around Advance Auto Parts hinges on execution, with weaker DIY trends and recent earnings disappointments both capable of undermining the margin recovery story.
Find out about the key risks to this Advance Auto Parts narrative.
Another View: What The P/E Says About Advance Auto Parts
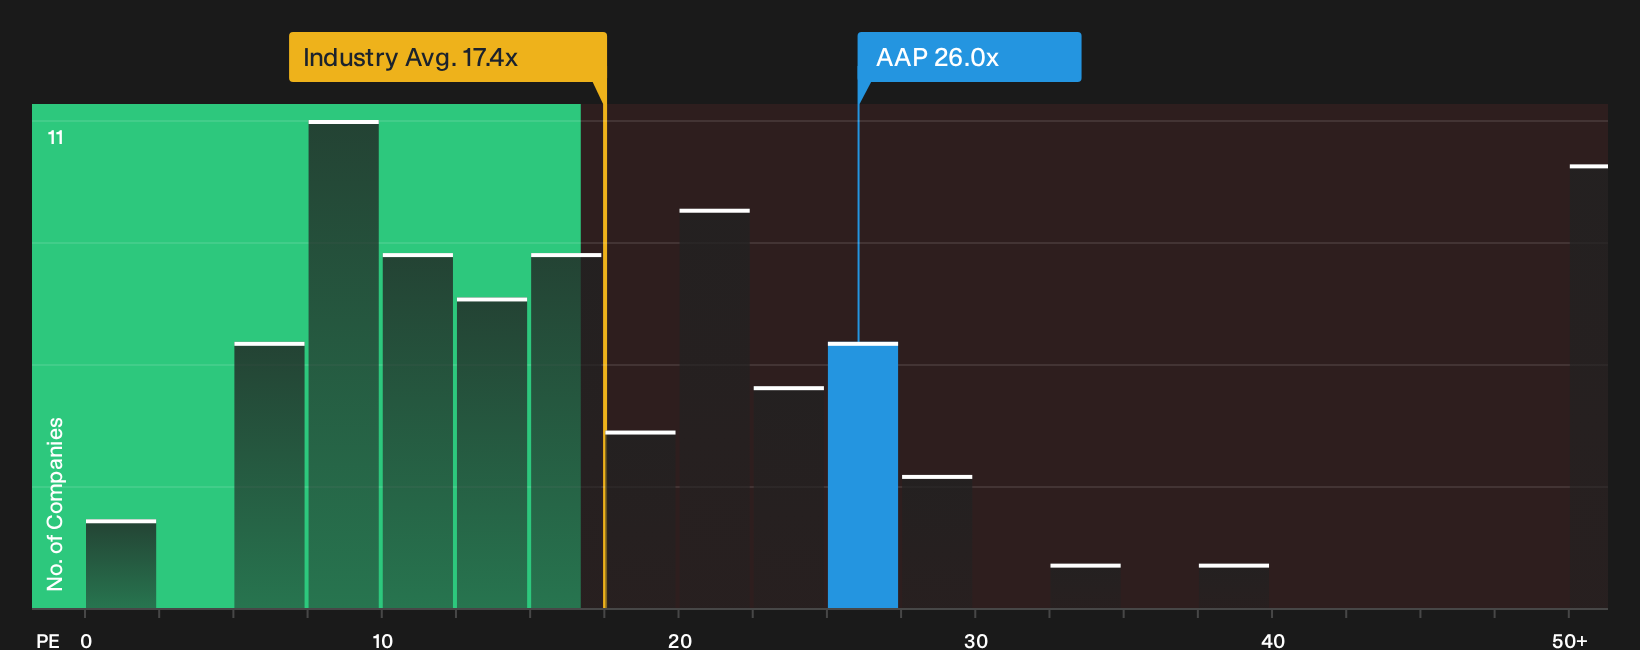
Advance Auto Parts might look modestly undervalued against a $49.95 fair value, yet the current P/E of 26x tells a different story. The ratio sits well above the Specialty Retail industry at 17.4x and also above the 19.3x fair ratio our work points to, which means valuation risk leans toward overpaying if earnings progress stalls.
For readers who lean more on earnings multiples than long term narratives, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Advance Auto Parts can be confusing, especially with both risks and bright spots in play. Consider moving quickly, reviewing the evidence yourself, and weighing the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Advance Auto Parts?
Do not stop at Advance Auto Parts. Put a few minutes into scanning fresh opportunities and you might uncover ideas that fit your goals even better.
- Target cash rich businesses with sturdy finances and upgrade the quality of your watchlist through the list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced opportunities where quality and valuation meet, using the 28 high quality undervalued stocks to spot potential bargains before attention floods in.
- Zero in on resilient companies with steadier profiles by scanning the 30 resilient stocks with low risk scores, so sharp drawdowns do not catch you off guard.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com