


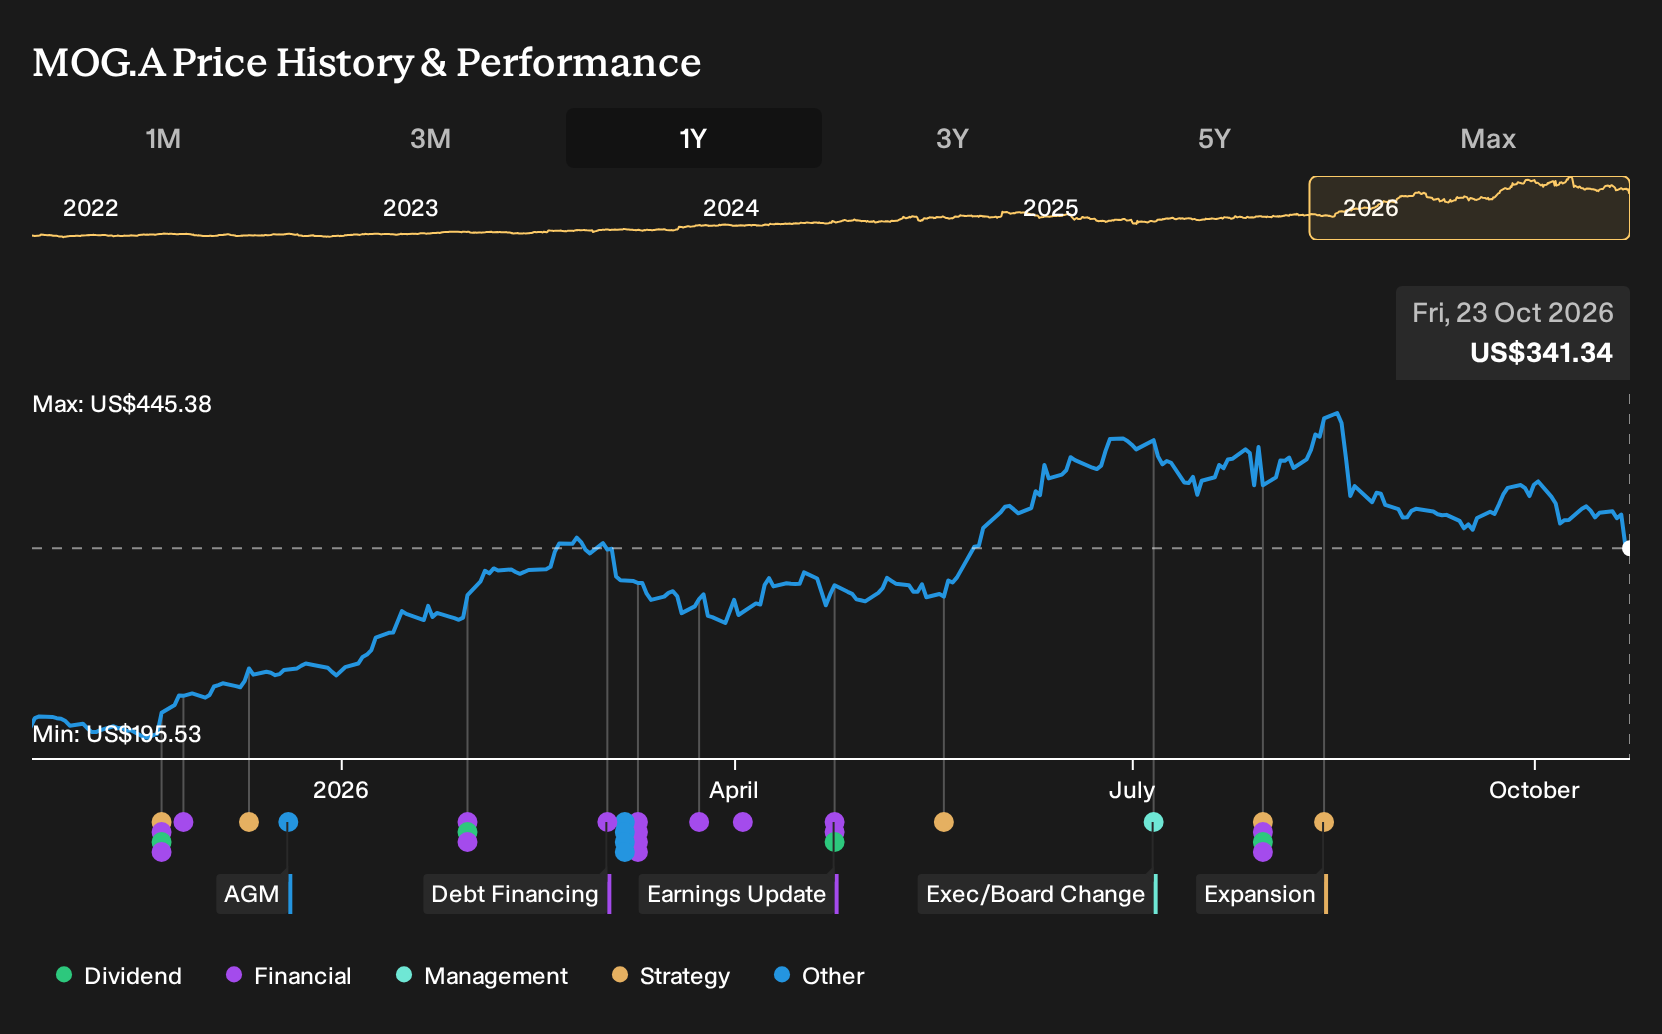
- Moog recently reported quarterly results that beat revenue and EPS forecasts and lifted full year guidance, with management pointing to stronger operating performance across the business.
- A key driver of the higher profit outlook is rapid growth in missile program activity, supported by new multi year agreements that management indicates are not yet fully visible in the reported backlog.
- We will now look at how Moog's investment narrative could be affected by stronger missile program earnings momentum and raised guidance.
Compare Moog's missile fueled momentum with other defense focused opportunities by screening for 94 robotics and automation stocks, which could benefit from similar demand trends.
Moog Investment Narrative Recap
Owning Moog means believing the current mix of defense, commercial aerospace, and industrial work can support solid earnings, even as the easy efficiency gains are already taken. The key short term swing factor now is missile program momentum. If those programs keep scaling cleanly into production, the raised guidance looks more like an operational reset than a one off spike. The biggest risk is that higher tariffs and renewed working capital pressure eat into the margin progress that Moog has worked hard to secure. If input costs bite harder or fresh capacity investments run hotter than expected, free cash flow could feel tighter just as investors are paying a premium P/E versus peers. The most relevant recent development is the rapid expansion in missile program activity tied to new multi year agreements that management says are not fully visible in the backlog yet. That matters because it suggests a pipeline of work that could support Moog's higher profit outlook beyond the immediate reporting period. For catalysts, the focus is on execution on these missile contracts and how smoothly Moog converts them into recurring, higher margin earnings while still funding data center cooling and commercial aircraft opportunities. Any sign that tariffs, working capital, or a tougher second phase of efficiency gains start to offset the missile uplift would test how durable this newer, higher earnings run rate really is.Moog's narrative projects US$5.3b revenue and US$428.3m earnings by 2029. This assumes 7.1% yearly revenue growth and an earnings increase of about US$51.2m from US$377.1m today.
Uncover why Moog's fair value indicates a 31% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate storyline for Moog leans heavily on missile demand as a long runway rather than a short boost. The most optimistic analysts were penciling in Moog revenue of about US$5.4b and earnings of US$470.2m by 2029, before this latest guidance lift. You can treat that as one upper bound and compare it with other viewpoints.
Explore 3 other Moog fair value estimates, including one that suggests as much as 41% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research and analysis.
- A great starting point for your Moog research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Moog. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Moog's overall financial health at a glance.
Looking For More Investment Ideas Beyond Moog?
If Moog has sharpened your interest in defense, aerospace, and industrial themes, it can help to compare it with other candidates that match your risk, income, and quality preferences. The Simply Wall St Screener lets you quickly filter for companies with traits that fit how you like to invest, so you are not relying on a single stock to carry your whole thesis.
- For investors who want potential upside without ignoring quality, scan a curated 28 high quality undervalued stocks that pairs fundamental strength with prices below many analyst estimates.
- If capital preservation and balance sheet resilience matter most to you, focus on a list of solid balance sheet and fundamentals (24 results) to find businesses with cleaner debt profiles and sturdier financial footing.
- When you are hunting for future leaders that are not yet widely followed, a hand picked 21 high quality undiscovered gems can surface stocks with strong fundamentals that sit off the usual radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com