


- QUALCOMM (NasdaqGS:QCOM) announced a new round of global workforce reductions as part of an operational overhaul.
- Management framed the layoffs as a step toward reshaping internal culture and simplifying how the business is run.
- The restructuring plan targets broad organisational layers, with cuts spanning multiple regions and corporate functions.
- QUALCOMM's decision to launch global layoffs and pursue cultural change sits alongside wider shifts our research has uncovered. Our analysis turns up 3 other big wins for QUALCOMM as well.
For readers looking to explore other plays tied to the same broad technology buildout story, start with 55 AI infrastructure stocks.
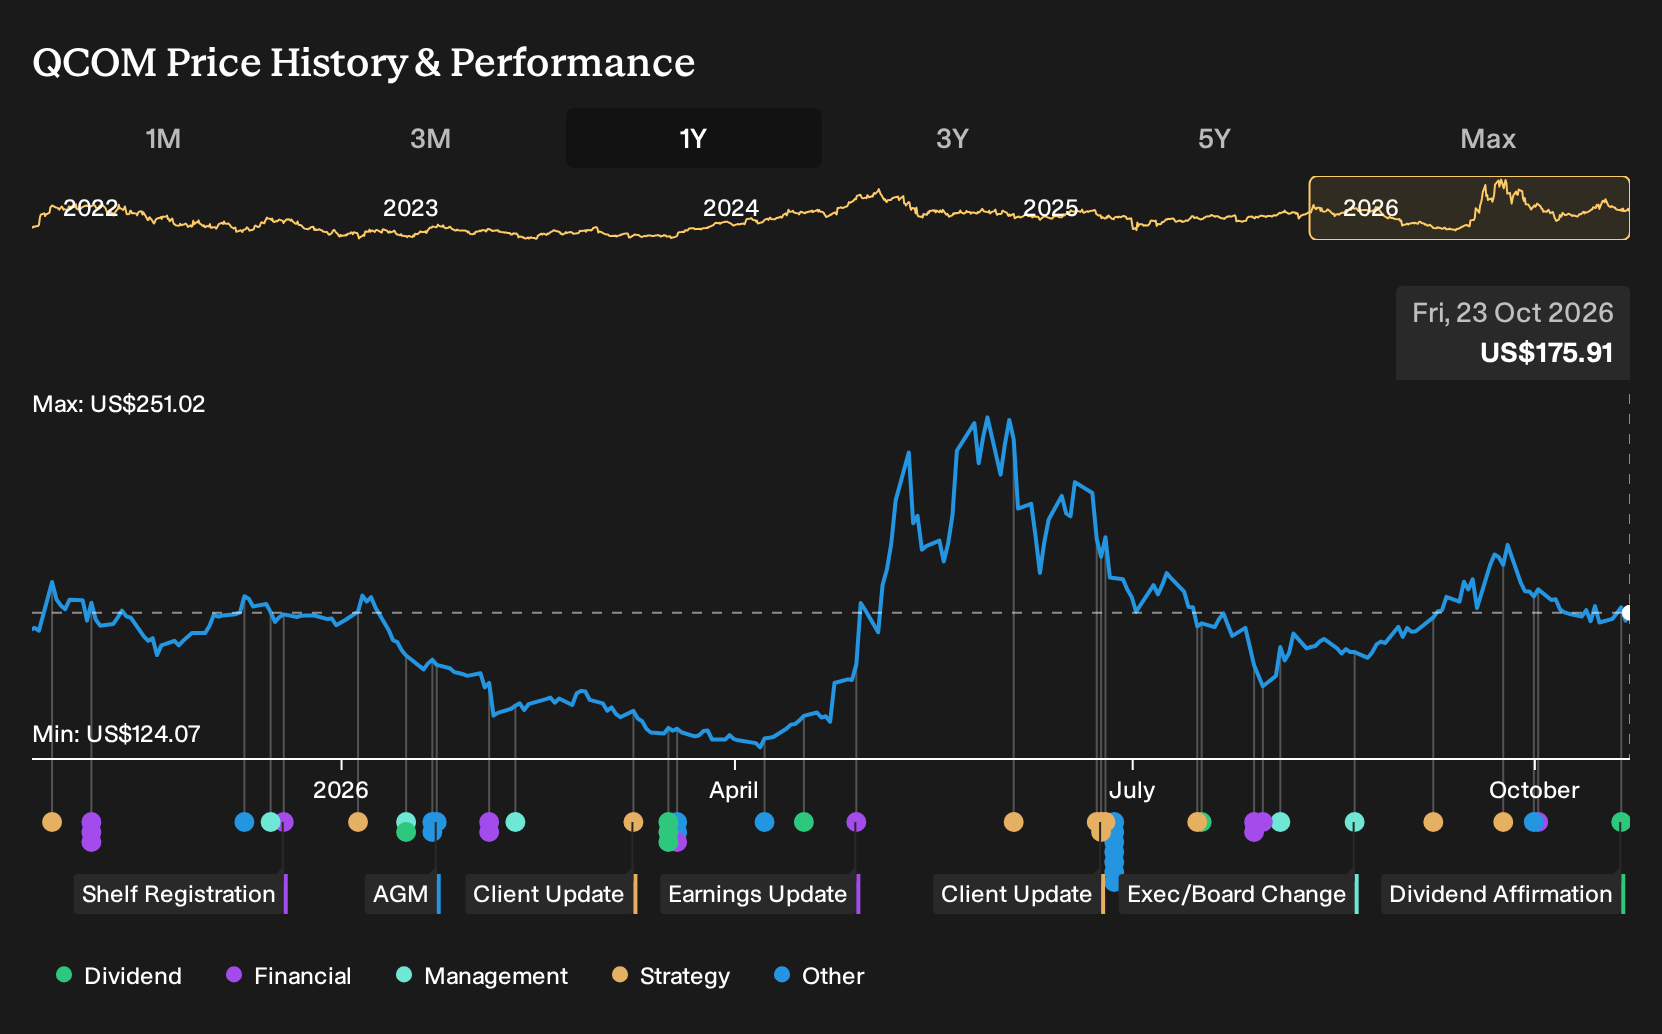
QUALCOMM develops and licenses core wireless technologies used in smartphones and connected devices worldwide, which puts its US headquartered semiconductor operation at the centre of ongoing demand for mobile and data infrastructure. That scale, reflected in a market value of about $187.8b, can shape how workforce and culture shifts ripple through the broader chip sector.
What Qualcomm’s layoffs signal for its AI and non handset pivot
The global workforce cuts point straight at the Narrative’s biggest test for Qualcomm. Management is trying to fix the “transformation friction” that has held back execution on its non handset QCT targets, including data center, automotive and industrial IoT. A leaner structure could help the business pursue the guided US$40b in non handset revenue by fiscal 2029 and manage costs while earnings are forecast to decline by an average 1.2% a year over the next three years. At the same time, aggressive restructuring can unsettle teams working on the AWS custom silicon ramp and the US$65b automotive design pipeline that analysts are watching closely.
See how these catalysts shape QUALCOMM's path to a $194 fair value.
The next proof point to track is how management talks about execution on the AWS custom silicon and High Bandwidth Compute roadmaps in the upcoming quarterly results, including any update on timing for the December 2026 data center contribution and progress against those 2029 non handset revenue goals.
Add QUALCOMM to your Watchlist and get alerts as these catalysts play out.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com