


Teleflex (TFX) just picked up an FDA Breakthrough Device Designation for its Freesolve resorbable magnesium scaffold, putting fresh attention on how this coronary device pipeline could matter for long term shareholders.
The recent FDA news lands after a stretch of improving momentum, with Teleflex posting a 7 day share price return of 5.10% and a 30 day gain of 11.65%. This comes even though the 1 year total shareholder return is 3.97% and the 5 year total shareholder return has declined 60.61%.
Scan beyond Teleflex and spot other cardiology focused device stocks with fresh momentum using our curated list of 34 healthcare AI stocks in this space.
Teleflex has rallied hard in October, yet the shares still trade at a double digit discount to both analyst targets and some intrinsic value estimates. Is that gap signalling opportunity or a warning on fair value?
Most Popular Narrative: 12% Undervalued
Teleflex closed at $136.29 while the most followed narrative pegs fair value closer to $154.73, so the recent rally still sits below that framework and keeps attention on how much of the reset story is already reflected in the price.
The multiyear restructuring program that targets about US$50 million in annual pretax cost savings by mid 2028, combined with plans to offset roughly US$90 million of stranded costs and move steady state adjusted operating margin from about 19% toward roughly 23%, provides a clear path to higher operating margins.
The integration work on the BIOTRONIK Vascular Intervention acquisition, including order to cash and sales channel adjustments that have weighed on current Interventional revenue guidance, still offers upside potential if Teleflex restores growth in these coronary and peripheral products and lifts both segment revenue and overall operating margin.
See why 8 investors see Teleflex as 12% undervalued.
Result: Fair Value of $154.73 (UNDERVALUED)
Still, the Teleflex story can break if the BIOTRONIK integration drags Interventional revenue longer than planned or if stranded cost savings and restructuring fall short.
Find out about the key risks to this Teleflex narrative.
Another Look At Teleflex Valuation
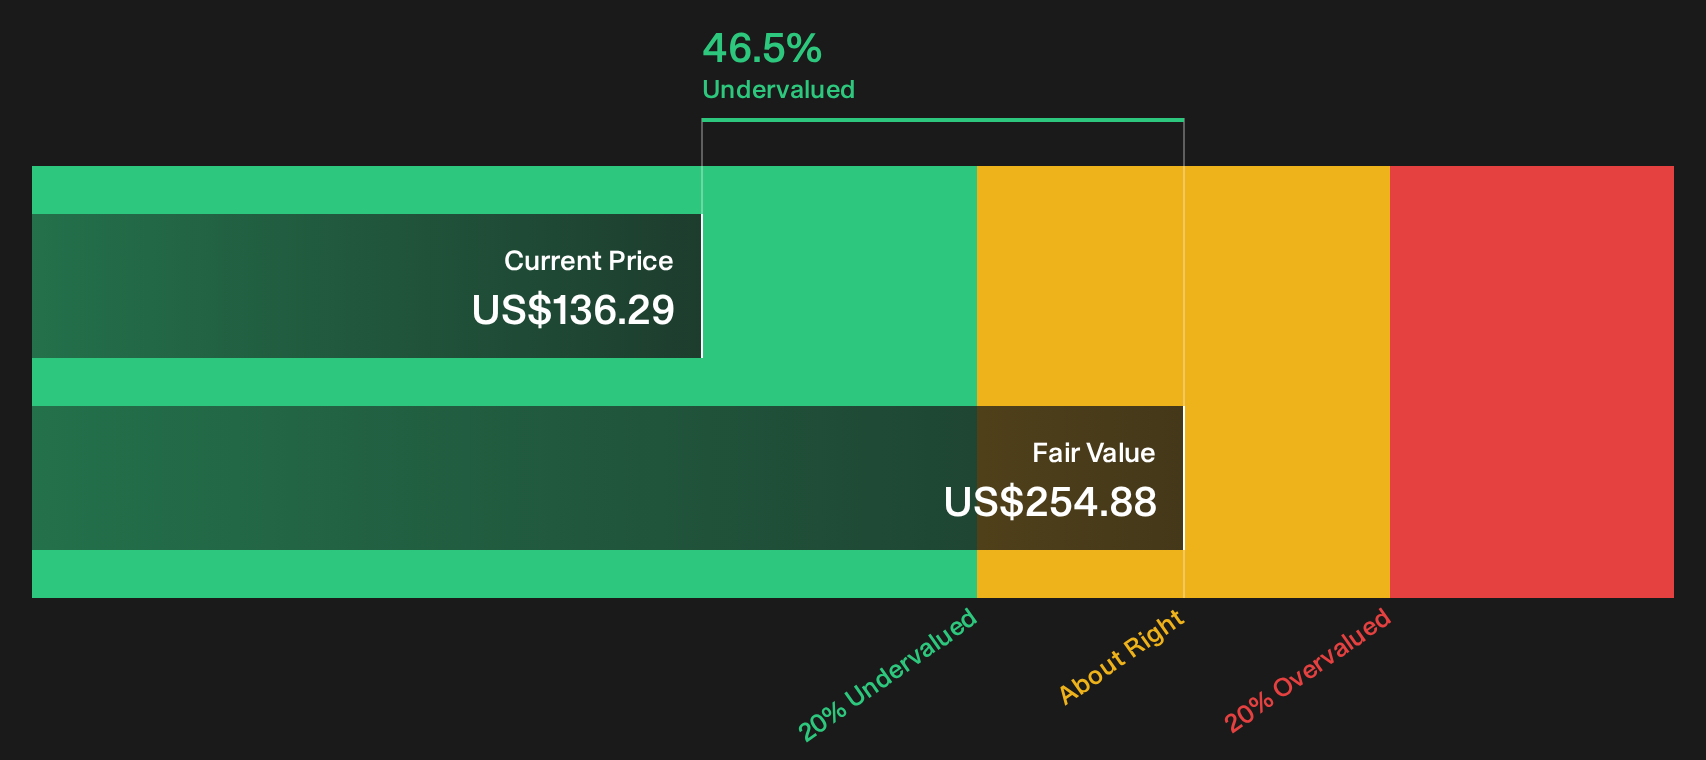
The analyst narrative leans on a fair value of $154.73, yet the SWS DCF model points to a future cash flow value closer to $254.88, which frames Teleflex as deeply undervalued on that lens. Which signal should carry more weight in your own worksheet?
Before leaning on any single approach, it helps to see exactly how that cash flow view is built and stress test the inputs against your own expectations, starting with Look into how the SWS DCF model arrives at its fair value.
Next Steps
The mix of upbeat and cautious signals around Teleflex makes this a judgment call, so move quickly, pull up the full data set, and pressure test the 2 key rewards and 1 important warning sign
Looking for more Teleflex sized investment ideas?
Do not stop at one ticker. Use the broader toolset to hunt for quality, manage risk, and keep your opportunity pipeline full while others stay narrow.
- Target quality at a discount by scanning a curated 28 high quality undervalued stocks that blends strong fundamentals with pricing that still looks reasonable.
- Prioritise resilience by running through a 30 resilient stocks with low risk scores focused on businesses with sturdier balance sheets and more stable risk scores.
- Spot under followed potential by checking a 21 high quality undiscovered gems where robust financials have not yet been fully recognised by the wider market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com