


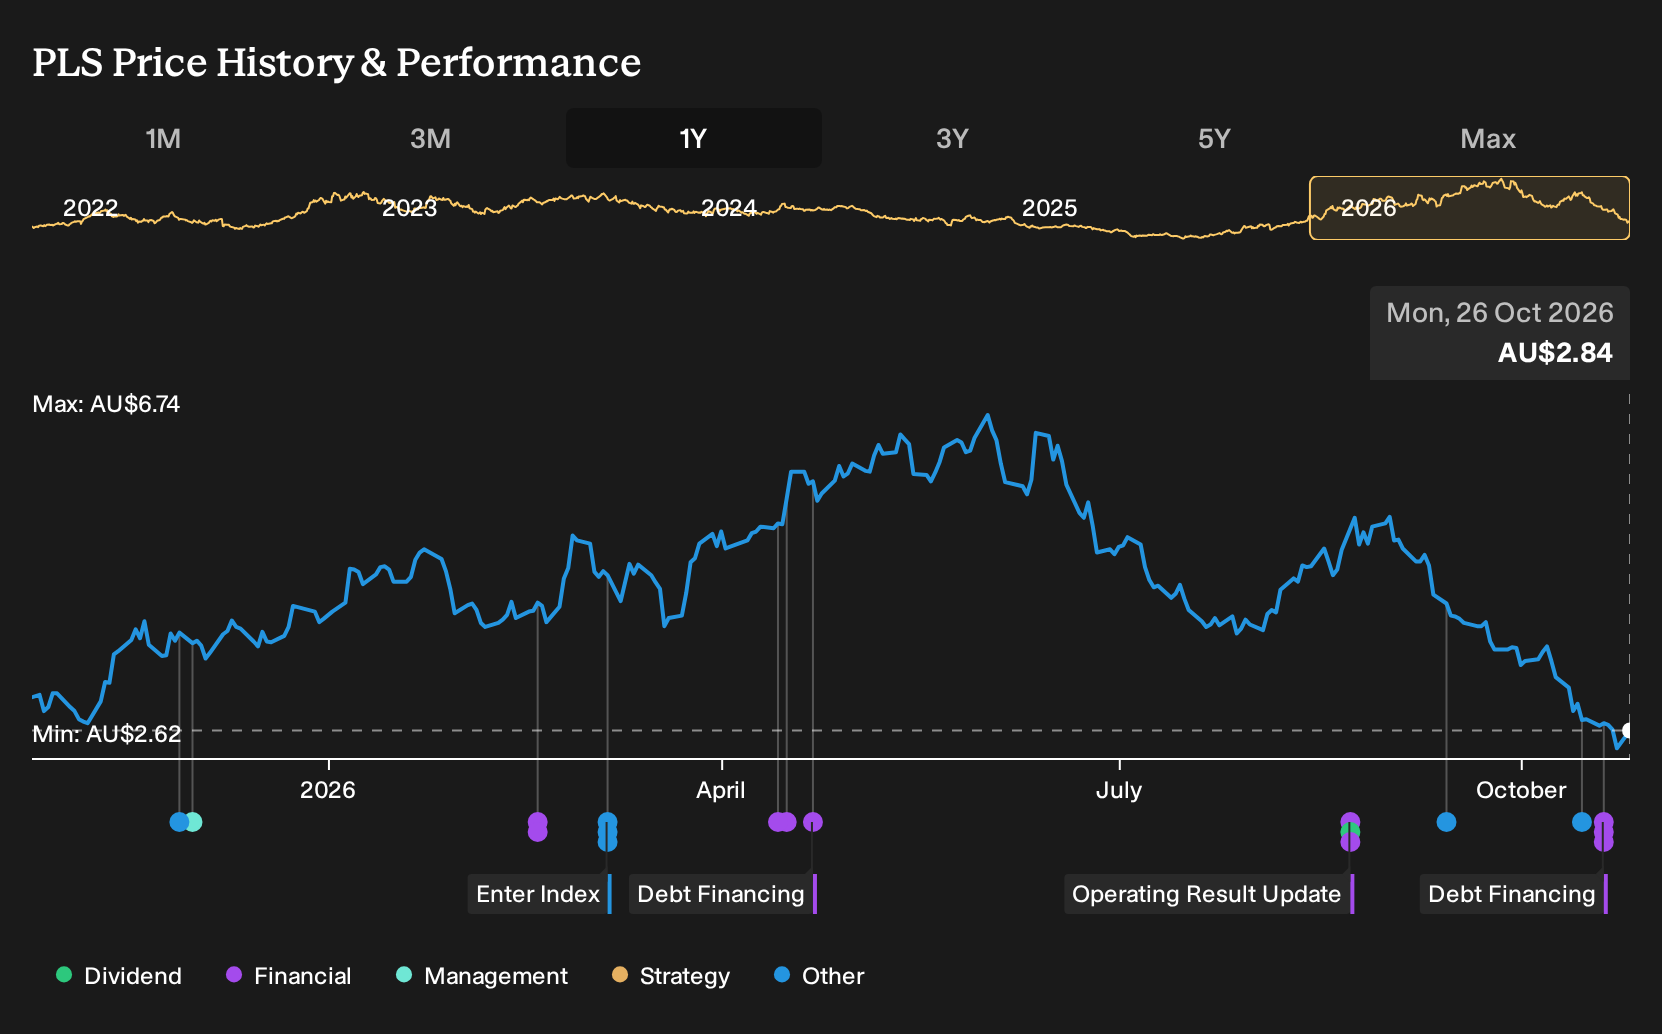
- PLS Group Limited has completed the pricing of US$700 million 8.00% senior unsecured notes due 2032, with interest paid twice yearly and guarantees from certain wholly owned subsidiaries, to fund general corporate purposes including capital expenditure and growth opportunities.
- The fresh US$700 million funding lines up with PLS Group's planned US$1.9b P2000 Pilgangoora expansion and US$600 to US$650 million in infrastructure spending, tightening the link between balance sheet structure and long term production ambitions.
- Attention now turns to how this sizeable 8.00% bond raise shapes PLS Group's investment narrative and risk reward profile for investors.
Scan beyond PLS Group and size up other miners funding growth with fresh capital by reviewing our hand picked 34 best rare earth metal stocks for comparison.
What Is PLS Group's Investment Narrative?
To own PLS Group, you need to buy into a fairly simple idea. This is primarily a lithium producer with a single flagship asset at Pilgangoora, heavy exposure to customer demand from China and a plan to scale output through the P2000 expansion. The thesis hangs on executing that A$1.9b project and A$600 to A$650 million of infrastructure spend without blowing out costs or timelines, while keeping returns on future capital at least in line with the existing business.
The new US$700 million 8.00% notes plug directly into that story. Fresh funding supports near term catalysts around final investment decisions, construction progress and any updates to guidance on capital intensity or production ramp up. It also adds a fixed interest burden that sits against earnings which are forecast to grow but not significantly, in a market where the share price has already fallen 34.1% year to date and 12.6% over 1 year.
Yet there is an awkward tension in the background that could matter a lot if ...
There's only one way to know the right time to buy, sell or hold PLS Group. Head to Simply Wall St's company report for the latest analysis of PLS Group's Fair Value.
Exploring Other Perspectives
Some of the most optimistic analysts focus on revenue potential rather than debt risk. Before this bond was announced, the bullish camp was pencilling in PLS Group revenue of about A$3.2b and earnings of roughly A$1.4b by 2029, and a 16.9x P/E. You should expect those views might shift and compare several angles.
Explore 5 other PLS Group fair value estimates, including one that suggests as much as 318% upside from the current price!
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your PLS Group research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for PLS Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PLS Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond PLS Group?
Once you have a view on PLS Group, it can help to widen the lens and see how other businesses stack up on quality, value and risk using the Simply Wall St screener.
- If you want to focus on value with quality fundamentals, start with a curated set of 2 high quality undervalued stocks that may warrant a closer look.
- If capital preservation and steadier profiles matter more to you, narrow the field to 6 resilient stocks with low risk scores that score well on resilience.
- If you are hunting for potential future leaders before they are widely followed, scan through 15 high quality undiscovered gems that combine solid business traits with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com