


- Accenture is working with TÜV SÜD and NVIDIA to develop a Physical AI Safety Suite that uses digital twins, AI agents and simulations to help industrial clients bring factory and warehouse automation online more quickly while supporting independent certification.
- Alongside new AI focused work with UMass Memorial Health and Workday clients, Accenture is leaning into physical and agentic AI as a core operating focus, tying its consulting revenue more closely to automation, certification and data platform projects.
- We will now look at how Accenture's investment narrative is shaped by its Physical AI Safety Suite push in industrial automation.
Scan how Accenture’s physical and agentic AI push compares with other automation driven opportunities by reviewing the hand picked 55 AI infrastructure stocks shaping tomorrow’s industrial backbone.
Accenture Investment Narrative Recap
To own Accenture, you need to believe its push into AI-heavy services can keep demand for consulting and managed offerings healthy even as some clients delay discretionary work. The Physical AI Safety Suite with TÜV SÜD and NVIDIA fits that story, tying industrial automation, safety and certification into higher value projects that can support earnings quality.
The short term swing factor still looks like enterprise appetite for larger transformation deals, which has already been sensitive to geopolitical and macro caution. The biggest operational risk remains prolonged softness in consulting intensive regions or federal work, where slower decision cycles could offset progress in AI, OT security and mid market expansion.
The TÜV SÜD collaboration is the clearest link between Accenture’s AI narrative and real world automation projects. By leaning on NVIDIA Omniverse, Cosmos and Isaac Sim, this suite positions the consultancy inside factory and warehouse build outs, where clients care about uptime, compliance and safety, not just IT spend. That can support deeper, longer contracts if execution matches the concept.
For catalysts, this matters because it ties directly into Accenture’s broader push toward platform and non-FTE style revenue. If industrial clients start to standardize on the Physical AI Safety Suite to prepare certification packages and scenario tests, it could reinforce demand for adjacent cybersecurity, cloud and data platform work while also concentrating execution risk around complex, safety critical deployments.
Accenture's current analyst narrative points to revenues of US$86.2b and earnings of US$10.2b by 2029. This is built on an assumed 5.1% yearly revenue growth rate and an earnings increase of about US$1.8b from US$8.4b today to the 2029 consensus level.
Uncover how Accenture's fair value indicates a 9% potential downside to its current price, suggesting that the current premium may not persist.
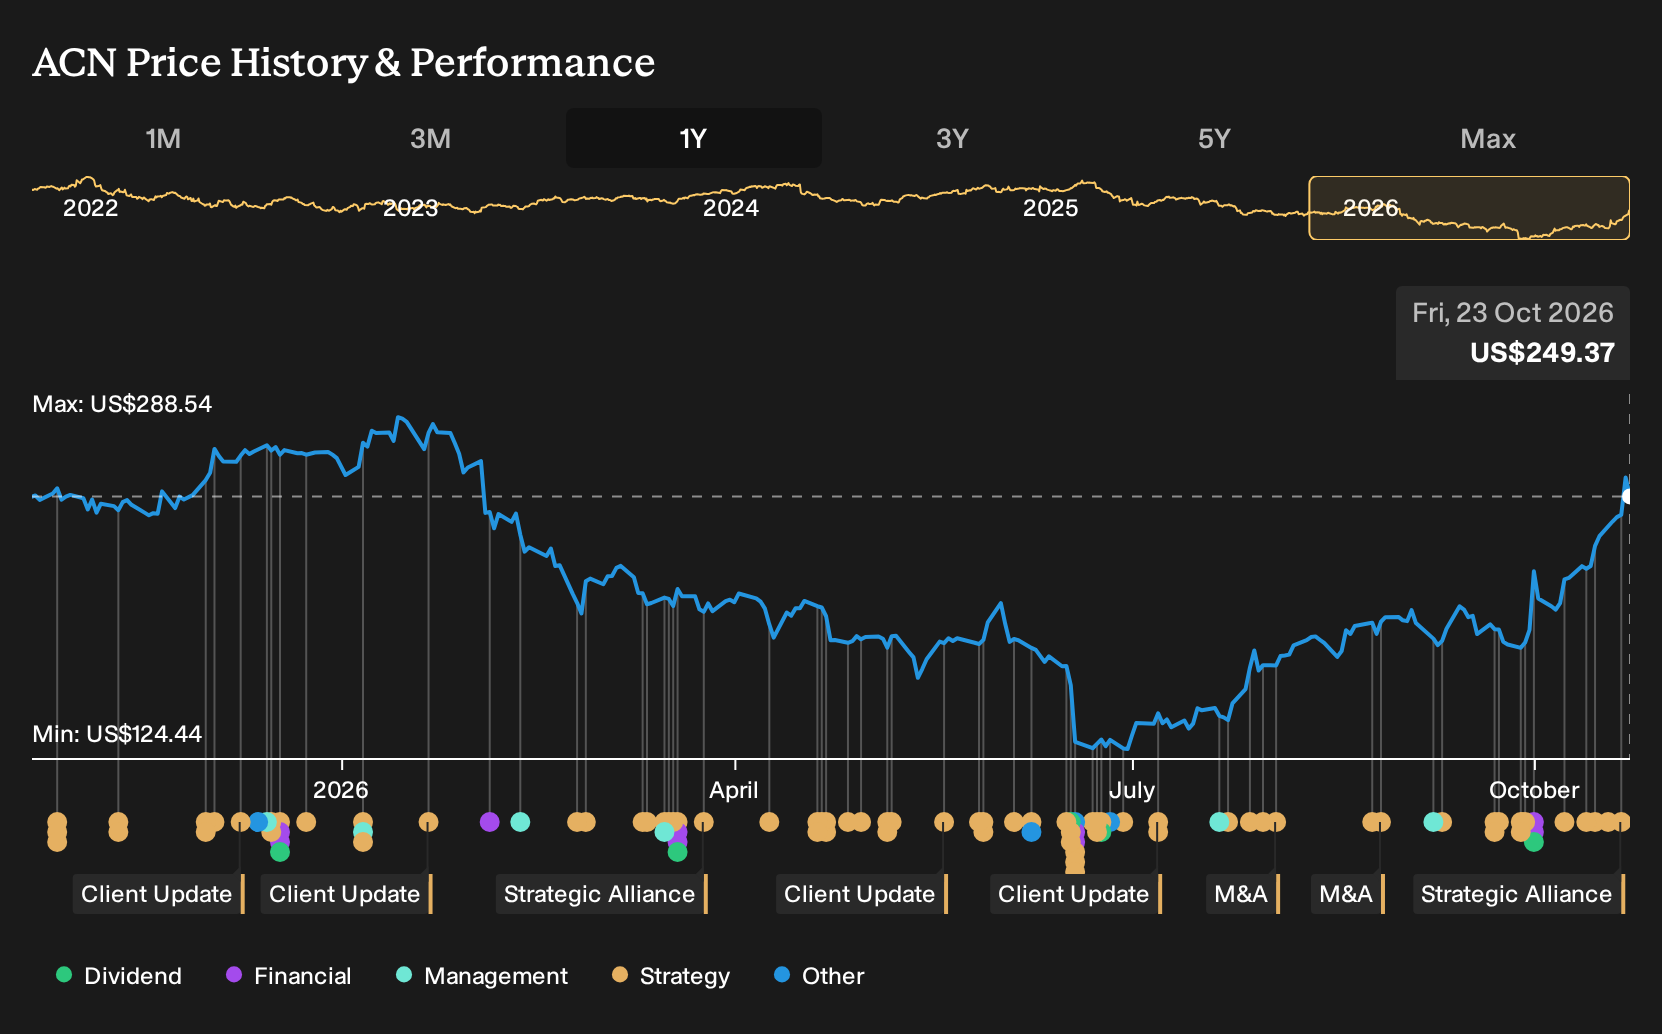
Exploring Other Perspectives
One bullish angle on Accenture is that AI heavy projects could offset automation risks. The most optimistic analysts were already penciling in US$91.4b of revenue and US$10.7b of earnings by 2029 before this Physical AI Safety Suite news. You can treat today’s update as a prompt to compare those views with your own.
Explore 7 other Accenture fair value estimates, including one that suggests potential upside of up to 21% from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Accenture research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Accenture. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Accenture's overall financial health at a glance.
Looking For More Investment Ideas Beyond Accenture?
If Accenture's AI and automation story has you thinking about portfolio upgrades, it can help to widen the lens and compare it with other companies that match your risk, income, or quality preferences.
- If you want resilient balance sheets and strong fundamentals to anchor your portfolio, start with this curated list of solid balance sheet and fundamentals (24 results) that filters for financial strength first.
- For investors who prefer mispriced quality, there is a focused 28 high quality undervalued stocks that highlights businesses where fundamentals and market pricing look out of sync.
- If income stability is your priority, use the targeted 5 dividend fortresses to zero in on companies offering higher yields with an emphasis on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com