


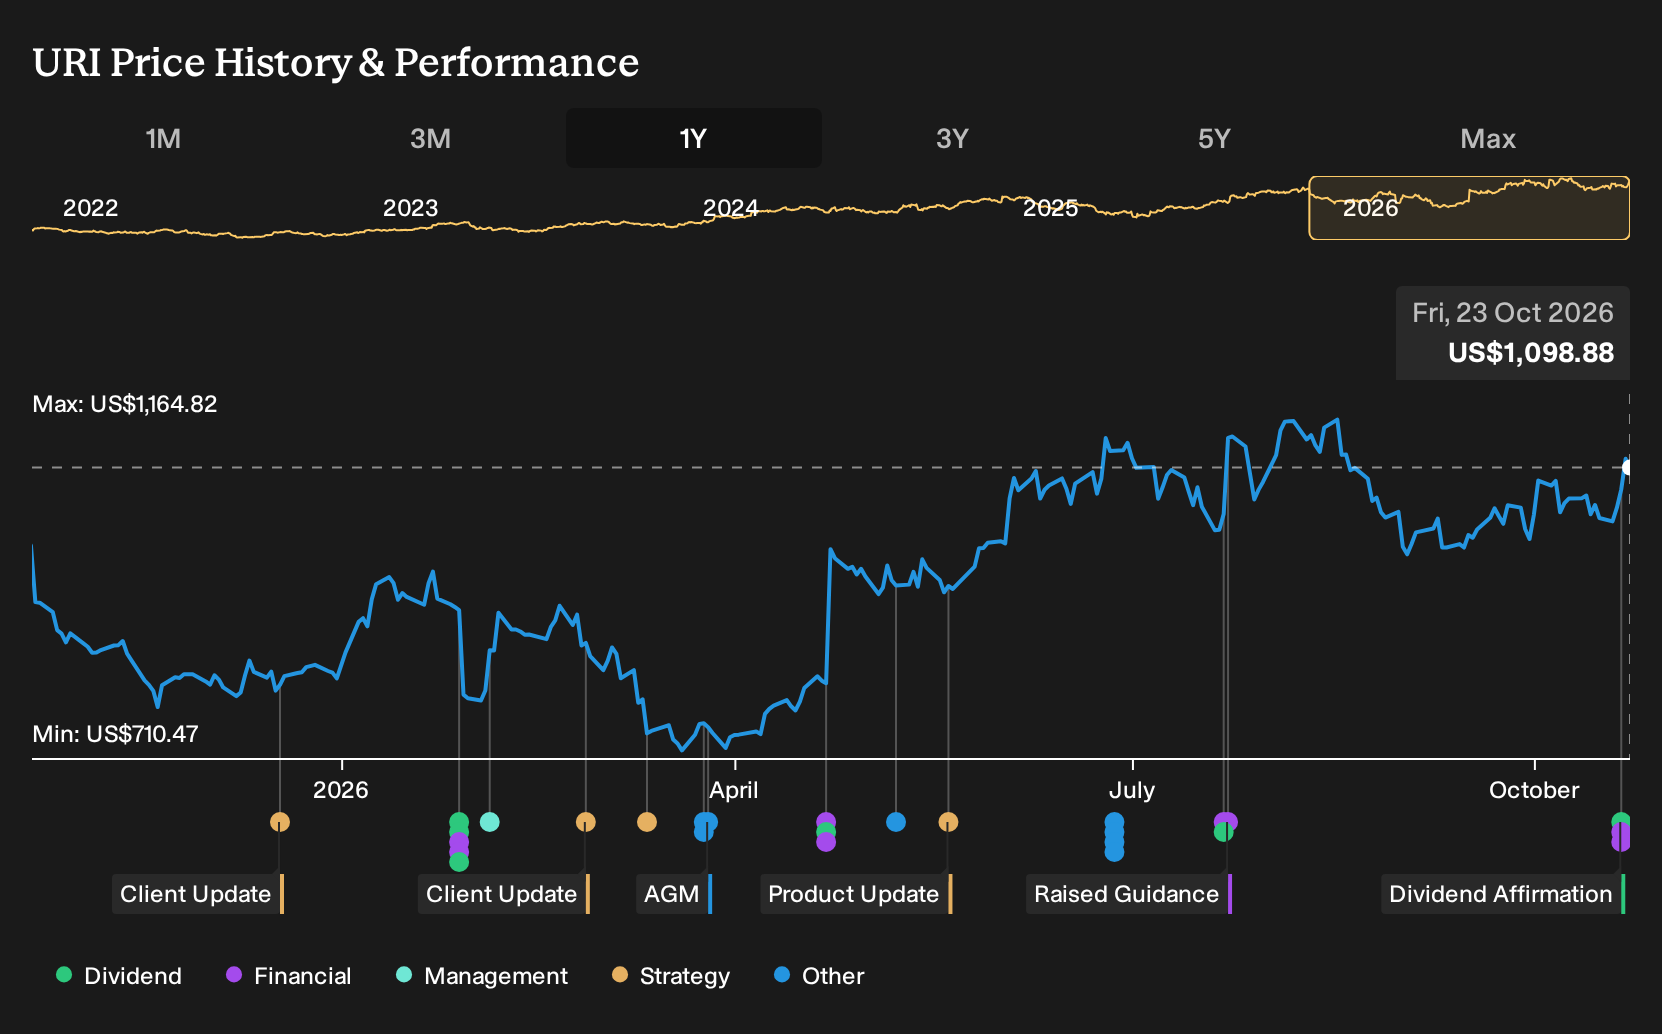
- United Rentals reported third quarter 2026 revenue of US$4.893b and net income of US$920m, raised full year 2026 revenue guidance to a range of US$18.0b to US$18.2b, affirmed a quarterly dividend of US$1.97 per share, and completed a US$791.36m buyback tranche, with a new universal shelf registration filed for potential future capital raising.
- The combination of higher guidance, active capital returns through dividends and repurchases, and fresh shelf capacity gives United Rentals multiple levers to fund projects and acquisitions while still returning cash to shareholders, supported by record year-to-date operating results through September 2026.
- We will now examine how United Rentals' raised 2026 revenue guidance could shape the existing investment narrative around large projects and specialty rentals.
Scan how United Rentals' fresh guidance and capital moves compare with peers by focusing on resilient infrastructure and construction plays screened as 30 resilient stocks with low risk scores
United Rentals Investment Narrative Recap
To own United Rentals, you need to believe the rental model can keep absorbing heavy fleet and CapEx spending into solid returns from large projects and specialty categories. The raised 2026 revenue outlook to US$18.0b to US$18.2b supports that view. The short term swing factor still looks like how consistently big infrastructure, power, and data center work converts into equipment on rent and utilization.
The biggest near term risk remains execution on that project heavy mix while managing margins and cash outlays. Higher ancillary and re rent activity carries lower contribution, and sizeable CapEx commitments can pressure free cash flow if project timing slips. The latest earnings beat does not remove that risk but allows more headroom to manage it.
The new universal shelf registration is the announcement that ties most directly into this update. It gives United Rentals a pre cleared path to issue common stock, preferred shares, or warrants if it wants to support fleet growth, specialty expansion, or future deals. For you as a shareholder, the key question is how any future use of that shelf would interact with returns on capital already in the ground.
That sits alongside a company that is still returning cash through the US$1.97 quarterly dividend and the completed US$791.36m buyback tranche. Capital flexibility cuts both ways. Easier market access can help the business respond to large project demand, but heavier reliance on external funding, on top of an already debt heavy structure, can amplify the impact if project activity or pricing softens.
United Rentals' analyst narrative links to forecast revenues of US$22.4b and earnings of US$4.0b by 2029, based on an assumed 10.0% yearly revenue growth rate and an increase in profit margins from 15.7% to 17.7%. This implies an earnings increase of about US$1.4b from roughly US$2.6b today.
Uncover why United Rentals' fair value indicates a 16% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate angle on United Rentals leans hard into optimism around future returns on all this extra capital. The most bullish analysts were penciling in up to US$23.5b of revenue and US$4.3b of earnings by 2029, before this guidance raise and shelf filing. You could read those numbers as a signal to explore how far opinions already stretch, and how this latest news might shift them again.
Explore another United Rentals fair value estimate, including one that suggests as much as 16% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your United Rentals research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for United Rentals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate United Rentals' overall financial health at a glance.
Looking for more investment ideas beyond United Rentals?
Once you are comfortable with where United Rentals fits in your portfolio, it can help to widen the lens and scan other stocks with different return and risk profiles using the Simply Wall St Screener.
- For investors who want staying power at the balance sheet level, start with a list of solid balance sheet and fundamentals (24 results) that can handle tougher conditions without leaning heavily on fresh capital.
- If value is the main focus, scan our 28 high quality undervalued stocks and see which businesses currently combine quality fundamentals with prices that look compressed against their underlying metrics.
- Income oriented readers who want more yielding options beyond United Rentals' dividend can review a curated 5 dividend fortresses offering higher payout potential.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com