


Credit for AI is splitting into winners and everyone else. SpaceX just lined up US$40b in callable debt to fund Nvidia GPU purchases, while Elon Musk warned that lenders are turning away firms without meaningful non AI data center income. That mix of abundant money for some and tighter terms for others creates real openings. This article reveals three stocks exposed to that news and why the market reaction matters.
The stocks highlighted in the list below are just a starter pack. The full screen surfaced 36 more companies with equally compelling financing and leasing narratives that do not fit into a single article. To go straight to the source and identify which of these AI credit and equipment financiers best matches your own thesis, analyze the AI Infrastructure Financing and Equipment Leasing Providers screener.
Climb Global Solutions (CLMB)
Overview: Climb Global Solutions is a value added IT distributor and solutions provider that resells software, hardware and cloud services across North America and Europe.
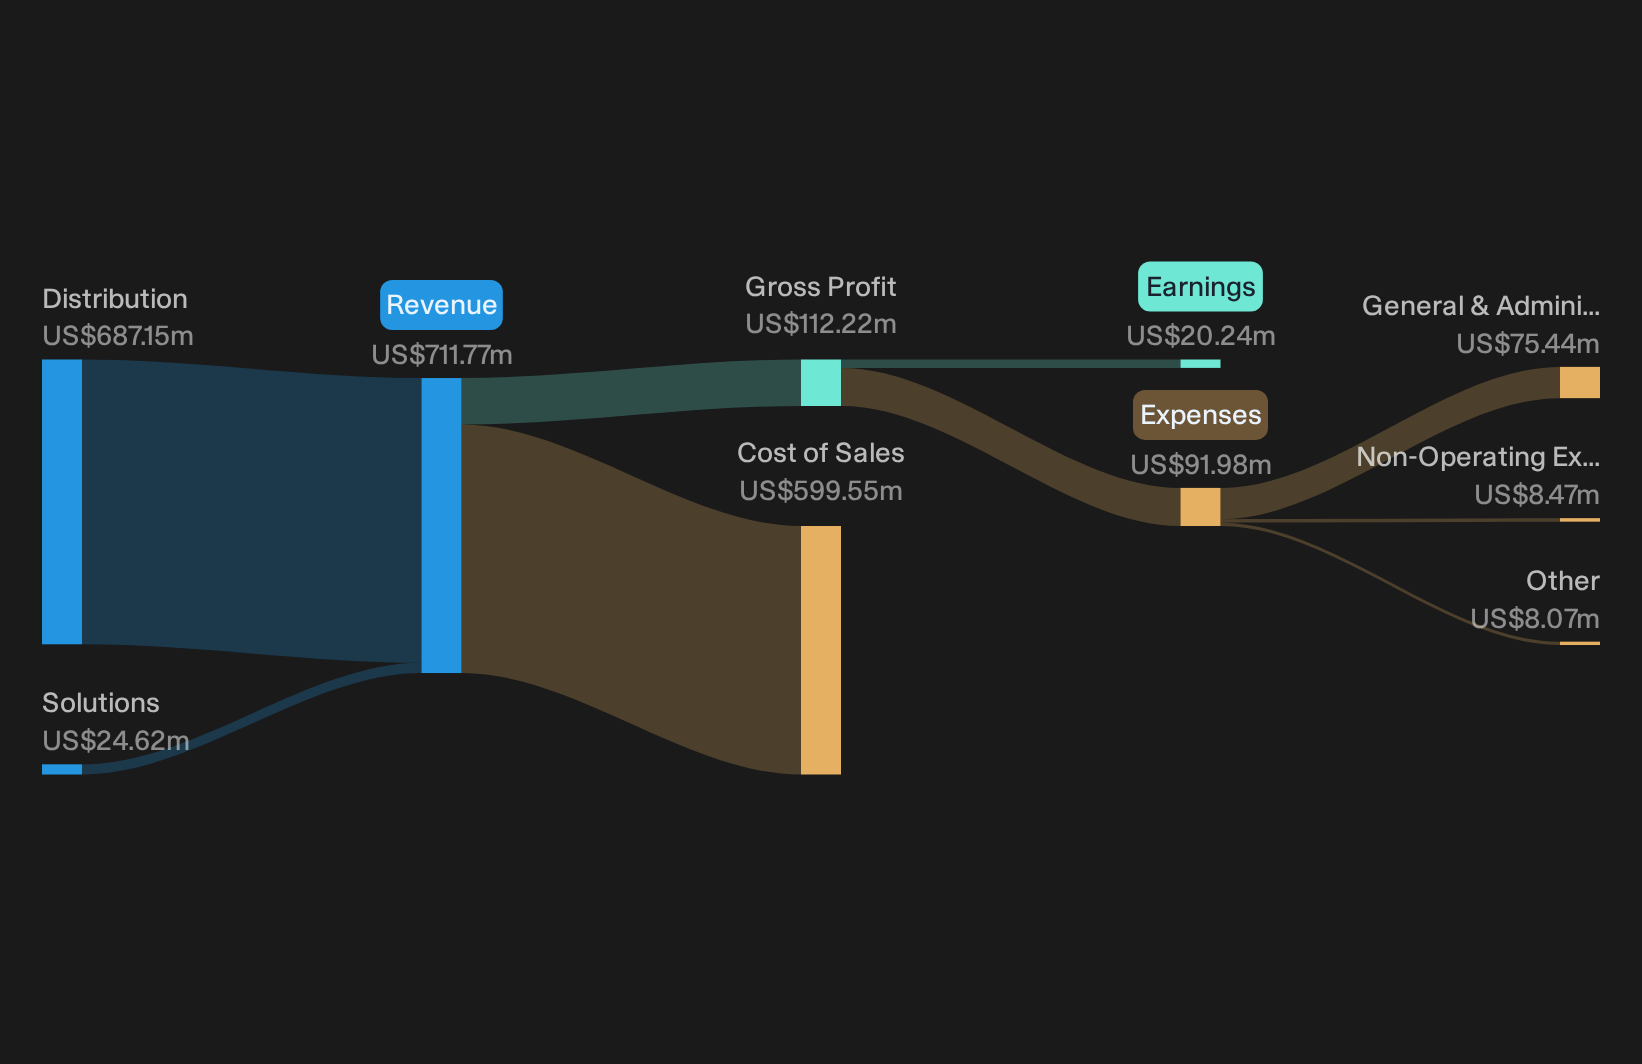
Operations: Climb Global Solutions generates about US$687 million from Distribution and US$25 million from Solutions, with most revenue coming from the United States.
Market Cap: US$604 million
Climb Global Solutions sits in this screener because its IT distribution and solutions platform can sit between GPU hungry data centers and the financing partners that fund their hardware refresh cycles.
"Climb Global Solutions is still selectively adding larger, established software and security vendors such as Fortinet, Ivanti and Checkmk, and is reporting double digit organic growth with 19 of its top 20 vendors along with new relationships like Darktrace ramping into the top 20, which supports further gross billings growth and a richer gross profit mix."
The real swing factor is how one unresolved cost pressure interacts with that richer vendor mix to shape future margins and cash generation.
That margin puzzle is exactly what the full narrative for Climb Global Solutions unpacks, revealing how Climb Global Solutions could see those costs decouple from its potential to generate cash.
Clearfield (CLFD)
Overview: Clearfield designs and supplies fiber management hardware that helps data centers and broadband providers expand high capacity, low latency networks for AI era traffic.
Operations: Clearfield reports about US$154 million in revenue, with roughly US$147 million from the United States and around US$6 million from other markets.
Market Cap: US$376 million
Clearfield matters for this screener because it sells the fiber plumbing that AI focused data centers, cloud operators and edge sites need when lenders fund new GPU heavy builds rather than pure compute renters.
"The proliferation of AI, IoT, and 5G applications is associated with an accelerating need for low-latency, high-capacity networks, which in turn is linked to demand for Clearfield's fiber management and connectivity solutions. This context, together with Clearfield's new product developments (for example, TetherSmart MFT and Home Deployment Kits), is cited by some analysts when discussing potential revenue trajectories and long-term earnings characteristics."
Investors may wish to consider how Clearfield’s earnings profile could be affected if one relatively quiet constraint on how quickly carriers commit to fresh fiber builds starts to ease.
That quiet constraint is exactly what the full narrative for Clearfield unpacks, showing where Clearfield’s AI traffic story could be stalled today and where acceleration might surprise next.

Harmonic (HLIT)
Overview: Harmonic provides software driven broadband access platforms, related hardware and cloud services that help cable and telco operators run faster, smarter networks.
Operations: Harmonic generates most of its sales in the Americas at about US$392 million, with additional revenue from EMEA and Asia Pacific.
Market Cap: US$1.10 billion
Harmonic matters for this AI infrastructure financing screen because its broadband gear and software sit inside the networks lenders are backing, even though Harmonic itself sells equipment and services rather than arranging leases or loans.
"Build out of Harmonic’s intelligence and AIOps portfolio, including the SensAI platform and a broadband intelligence opportunity sized at $1 billion to $2 billion annually, is expected to grow at more than 100% CAGR over three years and materially increase software driven revenue and earnings contribution."
What really shifts the story is how one emerging piece of that broadband and intelligence mix interacts with margins as AI era demand builds.
That shift is what the full narrative for Harmonic lays out in detail, highlighting where Harmonic’s broadband intelligence push could accelerate earnings power and reframe AI era risk.

Seeking Fresh Alternatives Before They Fly
Markets move fast and early money often captures the cleanest breakout before momentum gets crowded, stories get picked over and pricing gaps close. Scan fresh ideas while it matters and get in early.
- Spot potential breakout value plays before screens everywhere light up with the same tickers by running the 28 high quality undervalued stocks while pricing dislocations are still under the radar for now.
- Track structural trends in automation, logistics and smart factories by scanning the 94 robotics and automation stocks before capital enters the sector and entry points change.
- Position around structural demand for reliable electricity by reviewing the 42 power grid technology and infrastructure stocks before that story is fully reflected in broader coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com