


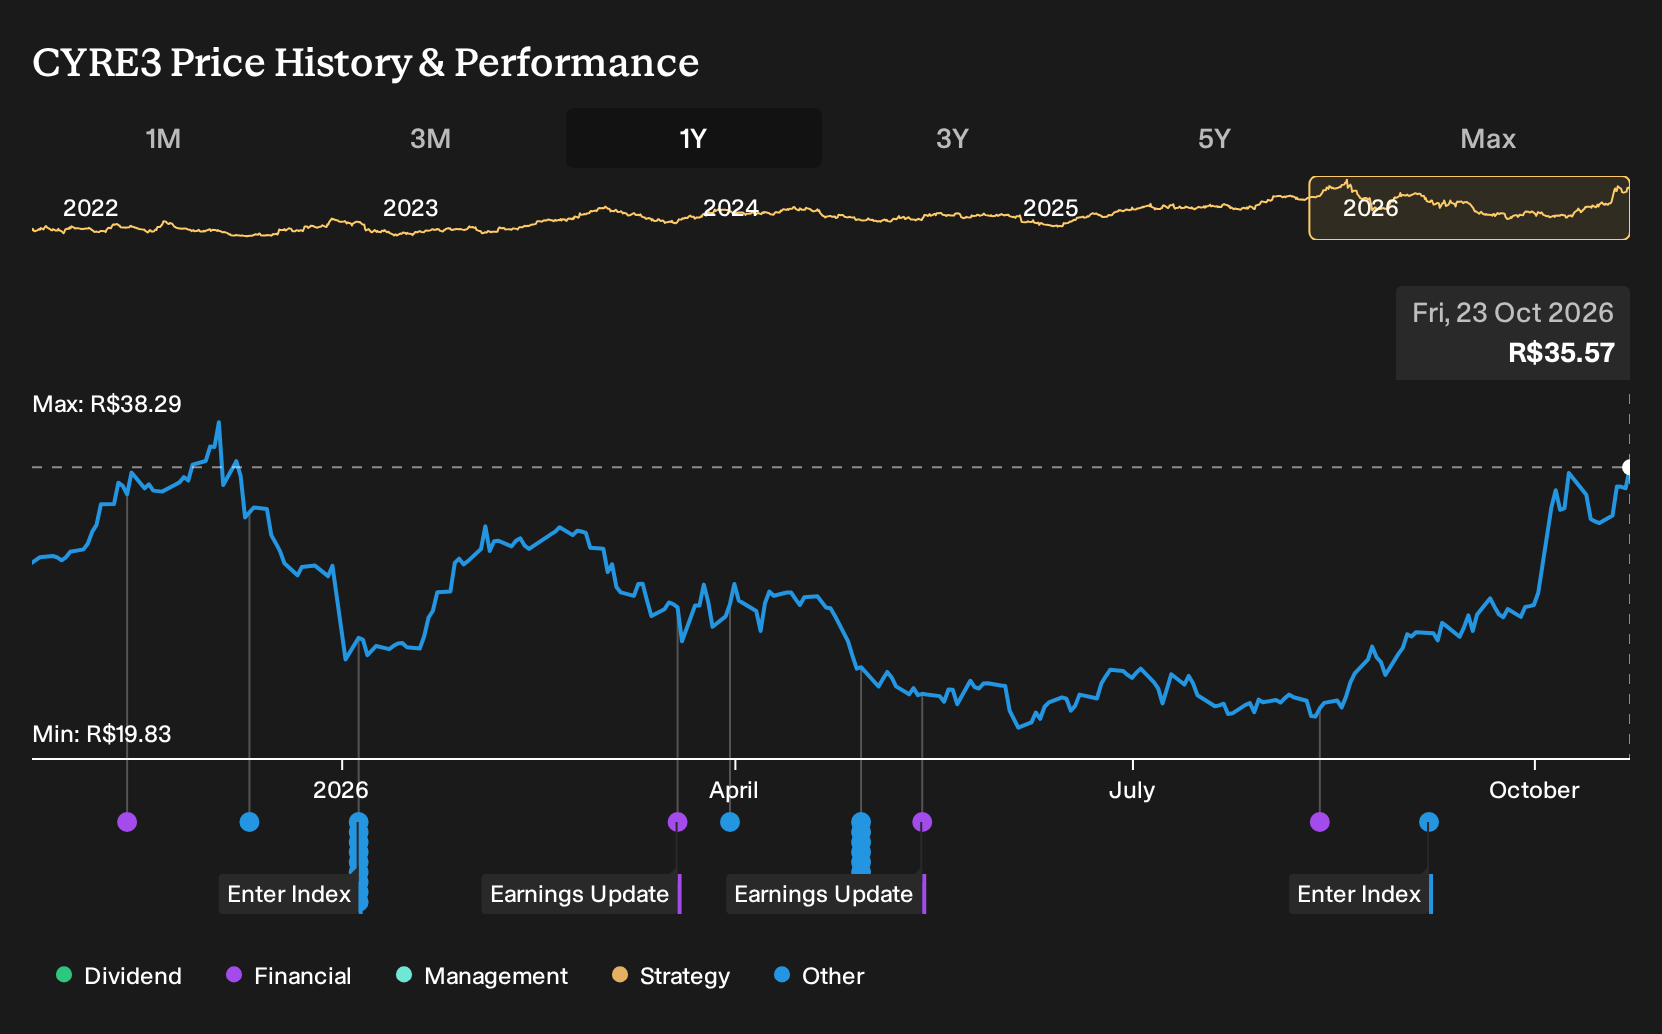
If you had bought Cyrela Brazil Realty Empreendimentos e Participações on 23 October 2025, you would probably be replaying that click today. For Cyrela Brazil Realty Empreendimentos e Participações shareholders, the return over the past year was 53.2%, including dividends. Analysts back then were split between easing Brazil rates and cost inflation biting into profitability, with fair value estimates pulling in opposite directions. If you were weighing those arguments at the time, which evidence would have carried more weight for you?
Cyrela Brazil Realty Empreendimentos e Participações has already moved. See which of 196 high quality undervalued stocks still trade below our estimates.
The Argument You Would Have Been Weighing On Cyrela Brazil Realty
The shares cost R$29.95 at the start of the period, and anyone looking at Cyrela Brazil Realty Empreendimentos e Participações had to choose between two very different stories.
On the bullish side, the October 2025 Narrative pointed to a Fair Value of R$34.58, a price implied by assumptions of 10.1% annual revenue growth supported by easing Brazil rates and heavier use of digital sales.
The bearish August 2025 view anchored on a Fair Value of R$26, built on worries that prolonged high interest costs and weaker cash conversion would pressure profitability even if margins reached 21.0% and the future P/E settled at 7.5x.
What The Results Changed For Cyrela Brazil Realty
The most concrete update came from Cyrela Brazil Realty Empreendimentos e Participações reporting Q2 2026 numbers. Revenue was R$2,480.871m compared with R$2,107.13m a year earlier, and net income moved from R$387.807m to R$451.676m, which leaned toward the optimistic case. Net margin slipped from 18.4% to 18.2%, so profitability resilience stayed unproven and the evidence cut both ways.
The core assumption under review was whether higher sales would translate into stronger profitability. When you assess another housing stock, track not only revenue and earnings, but also whether net margin actually moves toward the scenario analysts set out in their original thesis.
What Cyrela Brazil Realty's Price Now Asks You To Believe
Cyrela Brazil Realty now trades at R$35.57, and the selected Narrative’s Fair Value sits below that level. The story it tells is less about macro swings and more about whether cost control, cash generation and the Vivaz mix can keep current profitability steady.
A buyer at today’s price is effectively betting that Cyrela Brazil Realty can hold strong margins and returns. How securely does the selected Narrative think rising SG&A, guided construction cost inflation and working capital swings leave that assumption?
"Although Cyrela Brazil Realty Empreendimentos e Participações is currently reporting gross margins near 34% and ROE around 21%, management now guides 2026 SG&A to be more than 15% of revenue due to point of sale demobilization effects and launch growth. This could structurally cap operating leverage and weigh on future net margins and earnings."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Looking One Step Beyond Cyrela
Cyrela Brazil Realty points you toward housing and credit cycles. That is the obvious story.
Step sideways and a different question appears. What happens when household budgets tilt toward sport, wellness and premium gear instead of bigger mortgages?
Another business is leaning into that shift, building a premium athletic brand around pricing power and direct sales to loyal runners and gym goers.
Its plan depends on selling more through its own stores and digital channels, alongside a push into higher margin apparel.
If that mix shift holds, the result could be a very different way to hitch your capital to consumer spending.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 94% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com