


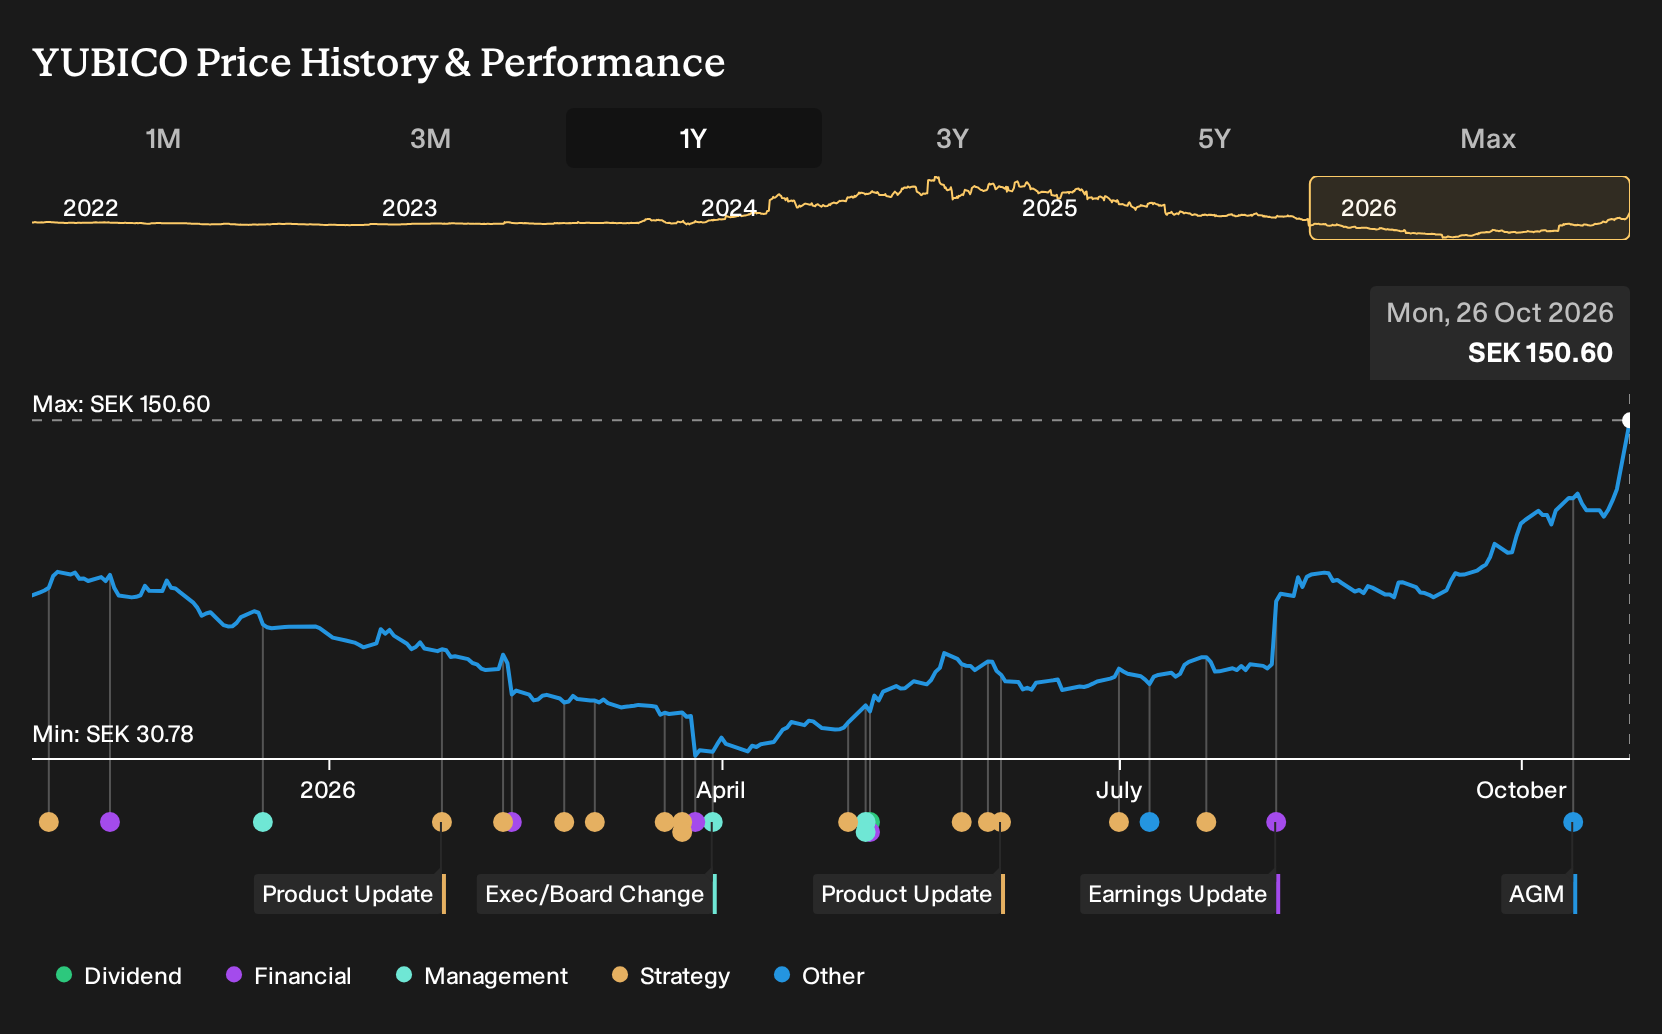
- Yubico has drawn fresh attention after a 72.6% year to date share price run, as investors question how far expected cash generation and the underlying security business can support current enthusiasm for its phishing resistant authentication and passkey offerings.
- The real tension sits in how Yubico balances premium expectations for hardware backed cybersecurity with execution risks around product mix, subscription transition, and a market that increasingly weighs software heavy identity solutions.
- We will now see how Yubico's investment narrative lines up with stronger demand for phishing resistant authentication in an AI driven threat environment.
Scan how the market is pricing similar cybersecurity plays by comparing Yubico's premium story with a curated set of 610 high quality undiscovered gems.
Yubico Investment Narrative Recap
To own Yubico after a 72.6% year to date share price run, you need to trust that the shift to subscription offerings and broader identity products eventually makes its current hardware heavy model more resilient. The key short term swing factor is whether large enterprise deals and recurring contracts can offset the pressure from weaker perpetual hardware sales and softer margins.
The biggest operational risk is that the market tilts faster toward software first or built in passkeys than Yubico can adapt, which could curb demand for physical keys and compress its current 7.1% net margin. The recent share price spike does not clearly change that core risk reward equation; it mainly magnifies execution scrutiny.
With no fresh company announcements tied directly to this latest share price move, the most relevant reference point remains Yubico's ongoing pivot to YubiKey as a Service and recurring revenue. That transition is described as gaining traction with large US and tech customers, and it sits right beside the market's focus on expected cash generation behind the current valuation.
For you as a shareholder, that subscription effort is effectively the main operational catalyst. If recurring deals scale smoothly, it can help stabilise revenue, partially offset currency and tariff headwinds, and reduce sensitivity to lumpier hardware cycles. If adoption is slower, the combination of lower recent profit margins, a high P/E multiple and volatile trading becomes a more obvious risk to sentiment.
What The Current Yubico Forecasts Actually Assume
Yubico's current analyst story hinges on a fairly punchy earnings ramp. Consensus points to profit of SEK 458.0 million by 2029, from SEK 151.0 million today, which implies roughly a 3x increase in earnings alongside forecast revenue of SEK 3.0 billion in that same year, underpinned by an assumed 12.6% yearly top line growth rate.
Yubico's narrative projects SEK 3.0 billion in revenue and SEK 458.0 million in earnings by 2029. This rests on 12.6% annual revenue growth and roughly a 3x increase in earnings from SEK 151.0 million today.
Uncover why Yubico's fair value indicates a 30% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
One alternate view focuses on Yubico’s order volatility rather than the subscription shift. You see this in the bearish cohort that models revenue at about SEK 2.9b and earnings near SEK 353.7m by 2029, a far more cautious script than consensus. These forecasts were set before this latest move, so updated opinions could shift sharply.
Explore 4 other Yubico fair value estimates, including one that suggests as much as 60% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Yubico research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Yubico. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Yubico's overall financial health at a glance.
Looking for more Yubico investment ideas?
If the Yubico story has sharpened your questions about price, quality and risk, it can help to widen the lens and compare it with other listed businesses that fit different profiles.
- If you want to focus on stability first, filter for companies that combine balance sheet strength with solid fundamentals using the list of solid balance sheet and fundamentals (207 results).
- If value matters most to you, scan for opportunities where quality metrics and pricing look more favourable through the 194 high quality undervalued stocks.
- If downside protection is your priority, narrow in on businesses with lower overall risk scores via the 223 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com