


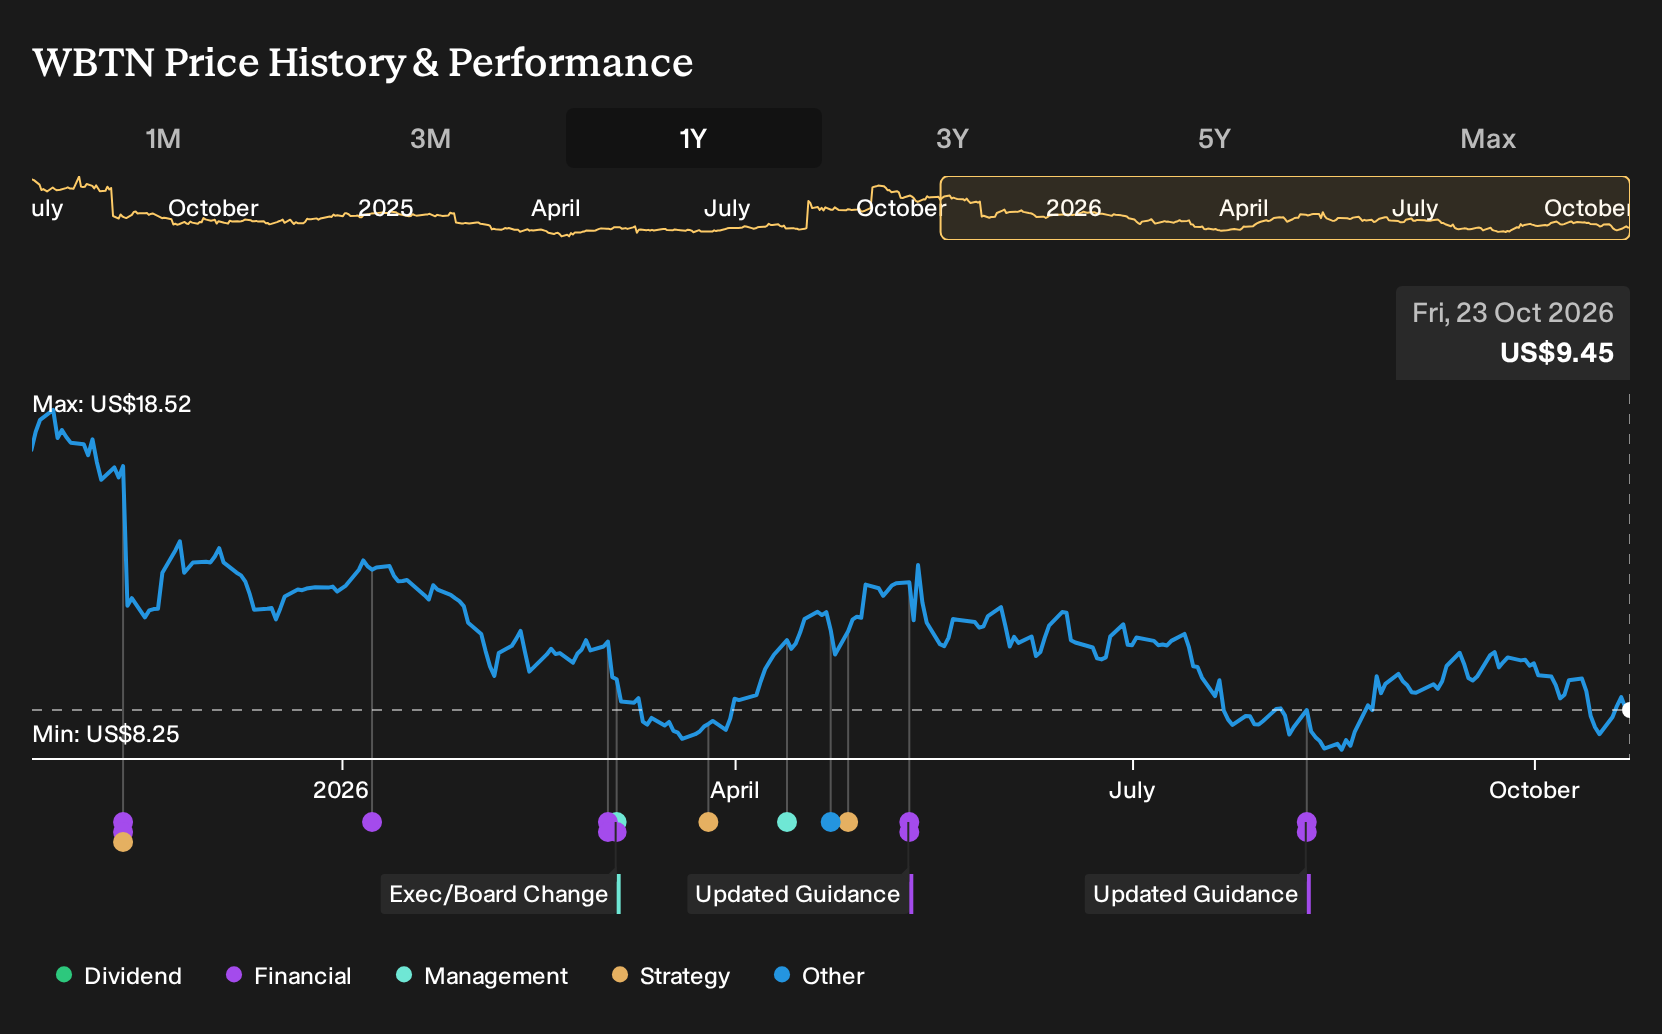
If you only glanced at the headlines this year, WEBTOON Entertainment looked busy building partnerships with Disney, Warner Bros. Animation, Genies and now a majority stake in RI Games. Holding WEBTOON Entertainment over the past year would have meant a 49.0% loss, including dividends. If you had been deciding whether to buy on 23 October 2025, how much of that risk was already visible in the early revenue and margin pressures?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The easy part of this move is behind WEBTOON Entertainment. Zero in on 28 high quality undervalued stocks for companies trading below our estimates.
The Two WEBTOON Entertainment Stories Investors Were Weighing
The shares cost US$17.86 at the start of the period, and anyone looking at WEBTOON Entertainment then had to decide which story felt more realistic.
The bullish narrative put fair value at US$22.25. It leaned on revenue climbing 17.3% a year and profit margin improving from a loss to 5.4% within three years, supported by the Disney partnership and a future P/E assumption of 32.1x.
The bearish case pointed to fair value of US$11. It assumed revenue growth of 11.7% and profit margin eventually reaching 11.0%, while warning that digital saturation, AI tools and weaker Western monetization could justify a future P/E of 9.0x instead.
What The Results Changed For The WEBTOON Entertainment Thesis
The clearest new fact was operational. WEBTOON Entertainment recorded Q2 2026 revenue of US$338.5m compared with US$348.3m a year earlier, and the loss deepened as net margin moved from 1.3% in Q2 2025 to 4.5% in Q2 2026. That combination challenged the bullish push toward positive profitability and pointed closer to the cautious case.
The lesson is simple. When a story leans on margin repair, track the reported net margin line in each filing and compare it with what the original model assumed, not just with headline sales.
What WEBTOON Entertainment’s Lower Price Now Asks You To Believe
WEBTOON Entertainment trades at US$9.45 today, after a 49.0% loss over the past year. The selected Narrative sees Fair Value above that price and links the gap to how AI tools, IP ownership and off platform formats might reshape the earnings mix.
For that higher figure to be considered reasonable, a buyer today would need to assume WEBTOON successfully scales higher margin advertising, IP adaptations and AI driven engagement on its existing audience base.
"Key Takeaways: Some analysts with a positive outlook expect WEBTOON Entertainment to use its AI-powered features, Disney collaboration and broader off-platform partnerships to support faster global user monetisation and strengthen its position in mobile storytelling. The main requirement for the strategy to progress is that WEBTOON successfully scales higher margin streams such as advertising and IP adaptations, including games with RI Games Holdings and the new IP Adaptation Fund, while also focusing on Japan and Rest of World growth."
The price and this Narrative do not agree. → Uncover what this Narrative says WEBTOON Entertainment is actually worth
Where WEBTOON’s Story Points Next
WEBTOON Entertainment lives where stories meet attention. Your next step could sit one layer earlier.
Those comics and animations still need a place where audiences search, watch and compare.
Another giant focuses on that discovery layer, selling the ad slots and cloud tools that keep users engaged.
Its AI systems try to understand intent, match it with content and help businesses fine tune campaigns.
If AI driven engagement deepens, that upstream position might matter more than any single storytelling platform.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 35% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com