


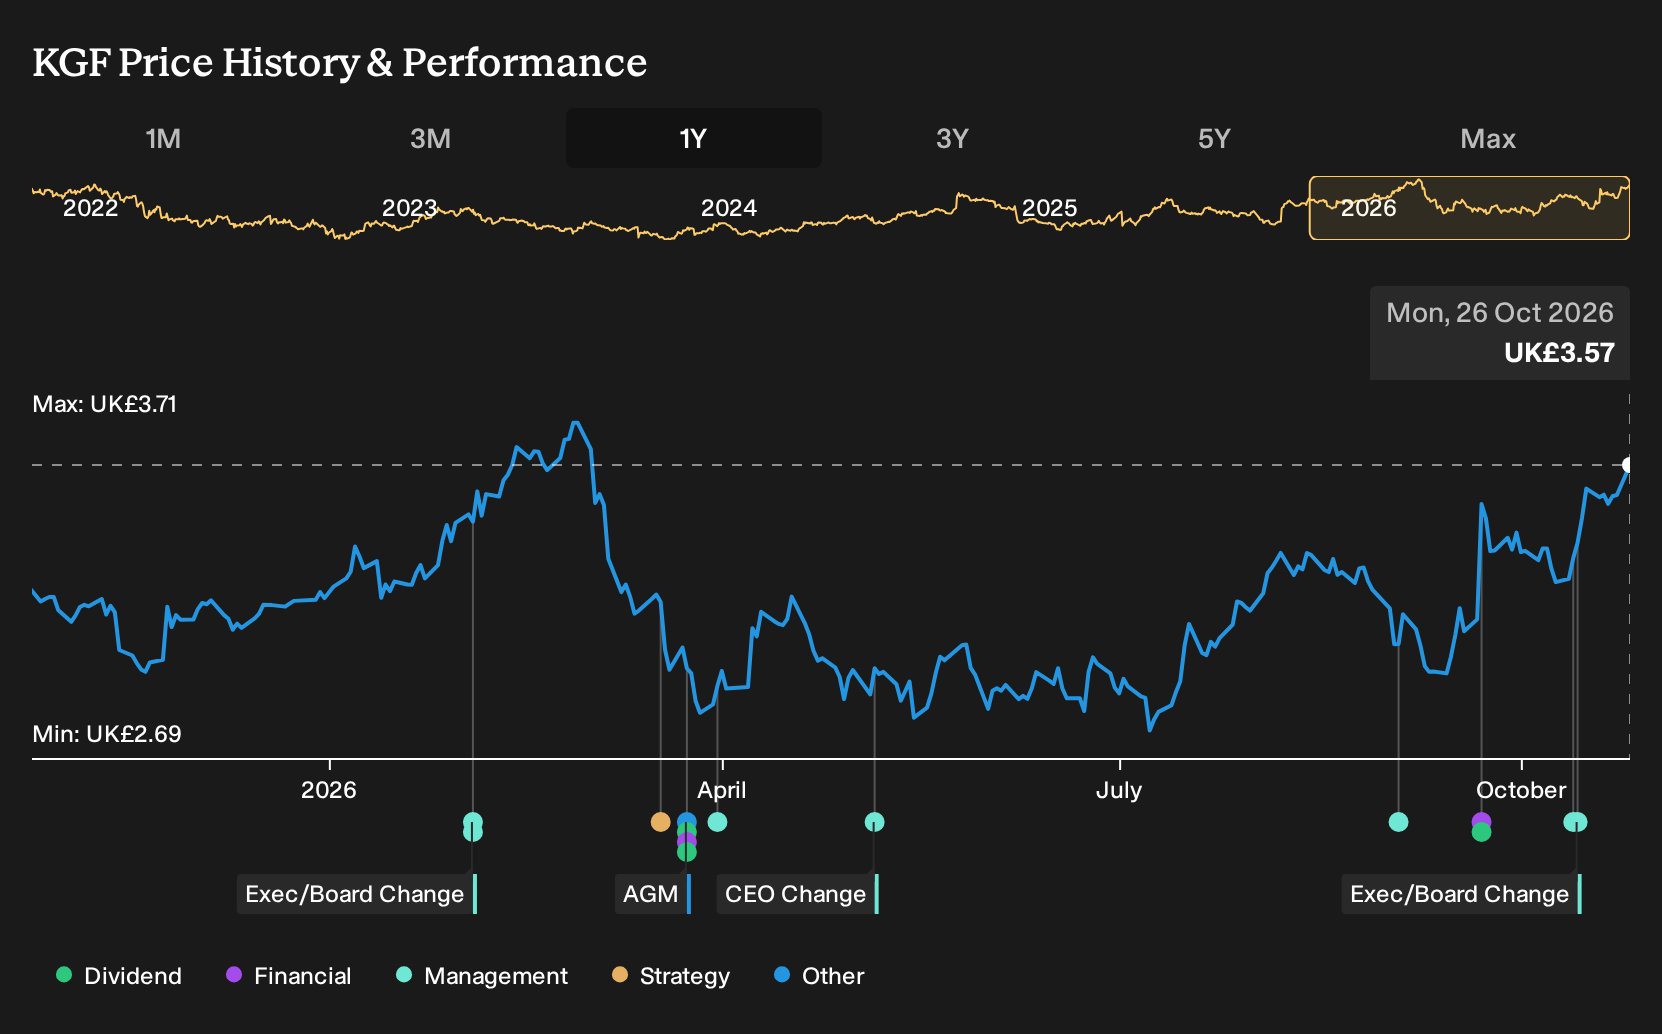
- In October 2026 Kingfisher confirmed that current chief executive Thierry Garnier will stay on the board until 31 December 2026, with Sebastian Gundel appointed as incoming CEO from February 2027 after leading DIY retailer OBI and focusing on digital channels, customer experience, and trade professional offerings.
- The leadership handover brings in Gundel’s track record in omnichannel retail and customer centric digital projects, which could influence how Kingfisher pursues e-commerce expansion, loyalty programmes, and professional trade demand across B&Q, Screwfix, Castorama, and Brico Dépôt.
- Attention now turns to how Kingfisher’s investment narrative might evolve as Sebastian Gundel’s digital retail experience feeds into future execution priorities.
Scan Kingfisher’s leadership shift alongside other retailers positioning for an omnichannel push by reviewing the hand picked 5 high quality undiscovered gems in this space.
Kingfisher Investment Narrative Recap
To own Kingfisher, you need to be comfortable with a slow revenue outlook and a focus on improving earnings through cost control, e-commerce and trade customers across the UK, France and Poland. The short term swing factor is still execution in weaker consumer markets, especially where sentiment is already under pressure.
The CEO transition to Sebastian Gundel looks more operational than thesis changing in the near term. The main risk remains softer like for like sales and cost inflation squeezing already modest 2.3% net margins, while management tries to keep restructuring and one off items from obscuring reported progress.
The most relevant update is Kingfisher confirming the CEO timetable, with Thierry Garnier staying through December 2026, CFO Bhavesh Mistry holding the fort, and Gundel taking over from February 2027. This creates a long overlap period in which French restructuring, Screwfix expansion and e-commerce projects continue under largely the same leadership.
For catalysts, the focus is on how Gundel’s omnichannel and loyalty experience from OBI aligns with Kingfisher’s aim to lift online to 30% of sales and deepen trade professional penetration. Execution on these projects, especially in France and Poland, sits alongside cost control as the key operational watchpoint.
Kingfisher Forecasts Under the New CEO Timetable
Analyst models sketch out a version of Kingfisher that leans on incremental progress rather than big swings. Consensus assumes revenue ticks along at 1.8% a year over the next three years, while profit margins shift from 2.3% today toward 3.5% in that period as cost work and mix changes feed through.
Earnings form the backbone of that story. Forecasters see profit rising from £298.0 million today to £487.0 million by 2029, with the more optimistic end of the range at £583.4 million. That implies roughly a 63% uplift in earnings from the current base if the central estimate plays out, which is a meaningful jump for a retailer that still depends heavily on mature markets.
Valuation thinking follows that earnings path quite closely. To line up with the analyst price target, Kingfisher would be trading on a P/E of 14.6x those 2029 earnings, compared with 18.3x on the current number and 13.7x for the wider GB Specialty Retail group. In simple terms, the consensus view rests on profit growing while the multiple contracts toward, but not below, the sector average.
Kingfisher's narrative projects £13.7 billion revenue and £487.0 million earnings by 2029. This assumes 1.8% yearly revenue growth and roughly a £189.0 million earnings increase from £298.0 million today.
Uncover why Kingfisher's fair value indicates a 7% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
You might see Kingfisher very differently if you focus on the risk that heavier marketplace and third party e commerce could pressure margins. The most bearish analysts were already pencilling in slower 1.1% yearly revenue growth and £452.8 million earnings by 2029 before this CEO news, so their story may shift the most as views update.
Explore 5 other Kingfisher fair value estimates, including one that suggests as much as 26% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Kingfisher research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Kingfisher. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kingfisher's overall financial health at a glance.
Looking For More Ideas Beyond Kingfisher?
If you are weighing Kingfisher against other opportunities, it can help to scan a broader universe of companies that fit clear financial filters. The Simply Wall St Screener lets you quickly line up candidates that match the type of risk and balance sheet profile you are comfortable with.
- For investors who care most about financial resilience, start with a list of solid balance sheet and fundamentals (10 results) and see which businesses pair cleaner debt profiles with steadier fundamentals.
- If capital preservation is your priority, filter the market through 4 resilient stocks with low risk scores and focus your attention on companies with more measured risk scores.
- When you want ideas that are not already crowded, scan the 5 high quality undiscovered gems that combine stronger fundamentals with less widely followed stories.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com