


Beijer Alma (OM:BEIA B) just posted third quarter earnings, with profit growing faster than sales, highlighting tighter cost control and higher efficiency at a time when demand questions and acquisition integration are still in focus for investors.
Beijer Alma's third quarter update and upcoming CEO transition arrived after a steady grind higher in the share price. A 1 day share price return of 1.50% took the stock to SEK303.5 and added to a 5.38% year to date share price gain. The 3 year total shareholder return of 78.80% signals that longer term holders have already seen a strong payoff, even as shorter term momentum has cooled over the past week with a 7 day share price return of 3.19% lower.
Spot opportunities alongside Beijer Alma by scanning a curated list of solid balance sheet and fundamentals (207 results) that echoes its focus on efficiency and disciplined cost control.After a strong three year run and a fresh push higher on these Q3 numbers, the real question for Beijer Alma holders is simple. Is most of the payoff already in the price, or is there still meaningful upside ahead as valuation comes into focus?
Most Popular Narrative: 8% Undervalued
Beijer Alma's most followed narrative pegs fair value at SEK328.5, a touch above the latest close at SEK303.5, which keeps attention on how far efficiency gains and disciplined expansion can carry the investment case.
The ongoing global acceleration in industrial automation and smart manufacturing is increasing demand for precision and engineered components, Beijer Alma's continued expansion (e.g., investments in higher-capacity production lines to meet excess demand and diversification into high-value sectors like rail) positions the company to capture elevated order volumes and drive future revenue growth.
See why 2 investors see Beijer Alma as 8% undervalued.
The narrative builds this view using a 6.96% discount rate and a long term revenue growth assumption of 5.68%, paired with an 11.72% net margin and a future P/E of 22.31x to arrive at a fair value of SEK328.5. That compares with the current analyst consensus target of SEK328.5 and implies the stock is trading at about a 7.6% discount to that central fair value estimate.
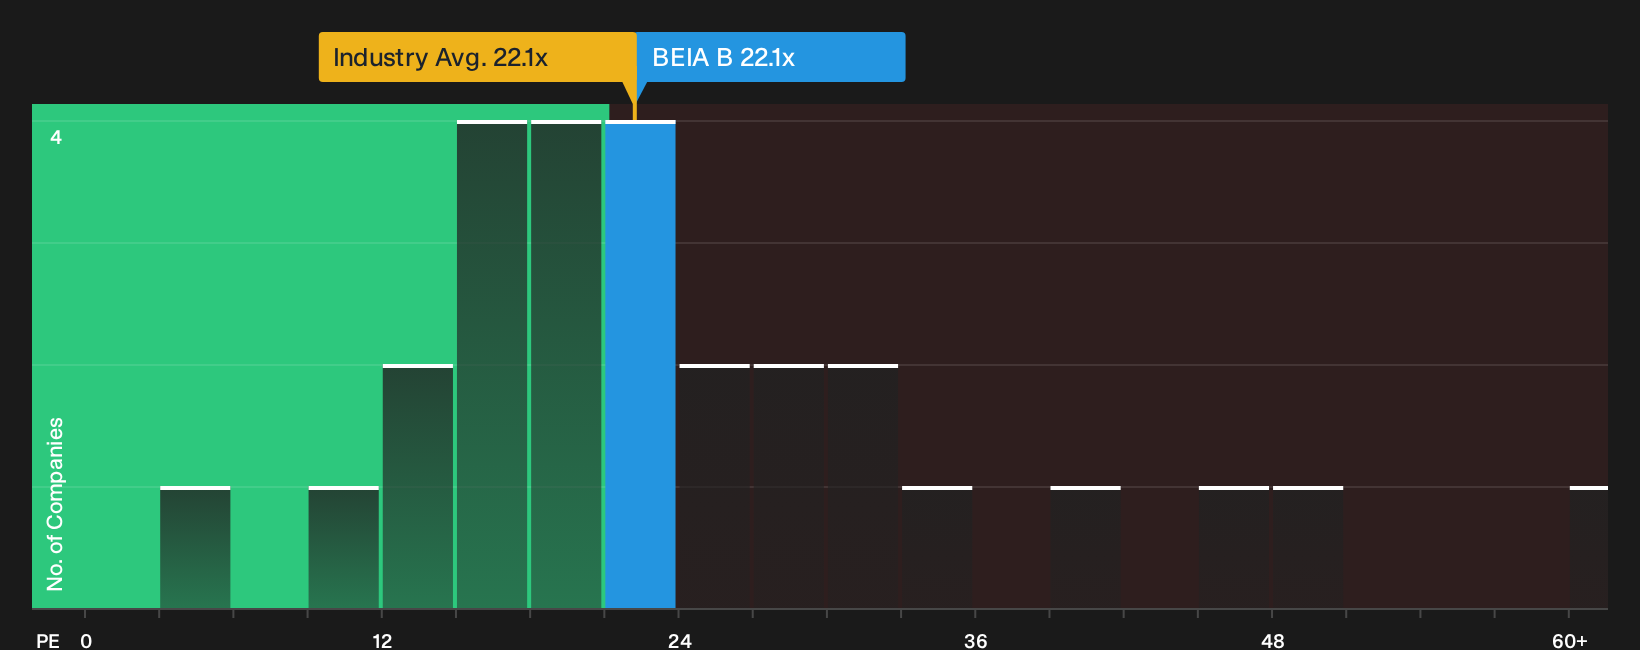
To line up with this story you would need to be comfortable that Beijer Alma can reach around SEK9.2b of revenue and SEK1.1b of earnings by 2029, while also supporting a mid 20s earnings multiple in a sector where Swedish Machinery peers currently sit at 22.1x according to the narrative inputs. You would also be leaning on the idea that current profit margin of 10.2% can move closer to the 11.7% mark over time through ongoing cost control, decentralisation and restructuring of underperforming assets such as Alcomex.
Result: Fair Value of SEK328.5 (UNDERVALUED)
Still, if industrial demand in core Nordic and US markets stays weak or the Alcomex restructuring drags on, the bullish Beijer Alma narrative could easily crack.
Find out about the key risks to this Beijer Alma narrative.
Another View: Beijer Alma Through The P/E Lens
On the flip side of that fair value story, Beijer Alma trades on a P/E of 22.1x compared with a fair ratio of 19.9x and peer average of 25x. That points to a stock that screens slightly expensive versus its own history but not stretched against rivals. Does that premium feel justified to you?
To pressure test whether this P/E gap signals risk or a reasonable quality mark up, it helps to go back to the detailed valuation breakdown, where the fair ratio and peer comparisons are set out side by side, and see how much conviction you really have in those earnings assumptions before leaning too heavily on a single metric. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Beijer Alma so far. Act while the data and narratives are fresh in mind and weigh both sides through the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Beijer Alma?
If Beijer Alma has sharpened your focus on quality, do not stop here. Use fresh data and structured filters to hunt for your next edge.
- Target resilient balance sheets and steady fundamentals by running your own screen through the list of solid balance sheet and fundamentals (207 results).
- Hunt for potential mispricing by scanning the 195 high quality undervalued stocks that filters for quality first and low headline multiples second.
- Anchor your portfolio with income ideas by checking the 224 dividend fortresses built around higher yields and durability of payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com