


Why Rachael Vegas Joining the Board Matters for Premium Brands Holdings
Premium Brands Holdings (TSX:PBH) is drawing attention after appointing retail veteran Rachael Vegas to its board, linking the packaged food group more closely with front-line grocery, club, and mass retail decision making.
Recent trading shows that interest around Premium Brands Holdings is picking up again, with a 7 day share price return of 3.15% and a 30 day share price gain of 2.18%. However, the share price is still down 19.62% over 90 days and the 1 year total shareholder return has declined 20.81%, which points to a rebound attempt after a tougher stretch for longer term holders.
Scan for other consumer and food producers that could be setting up for a similar sentiment reset with our curated list of 3 high quality undervalued stocks.
Premium Brands Holdings has bounced in the short term while longer term holders are still under water. Is the recent board change and share price uptick the start of a rerating, or has most of the easy upside already occurred?
Most Popular Narrative: 34% Undervalued
Premium Brands Holdings last closed at CA$74.09 while the most followed narrative sees fair value closer to CA$112.25, so the gap between price and that view of future cash generation is wide.
The completion of Premium Brands Holdings'' roughly $1.1b capital investment program, with only about $41.6m left to spend and over $2b of new sales capacity available, provides room for additional volume from existing and new programs, which can support revenue and EBITDA as utilization improves.
See why 17 investors see Premium Brands Holdings as 34% undervalued.
Result: Fair Value of CA$112.25 (UNDERVALUED)
Still, if Premium Brands Holdings struggles to ramp new U.S. programs or delays asset sales, the cash flow and deleveraging narrative could easily lose momentum.
Find out about the key risks to this Premium Brands Holdings narrative.
Another View on Premium Brands Holdings' Valuation
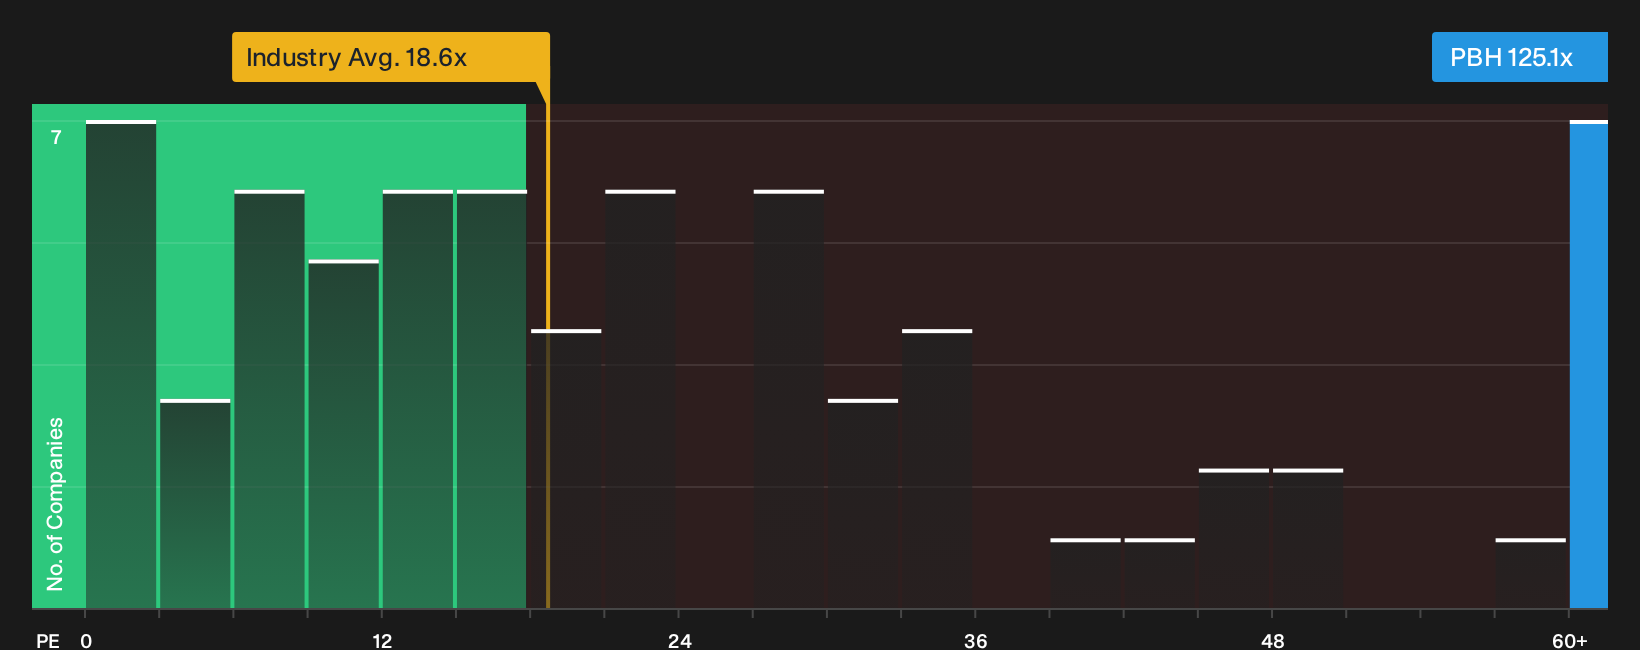
The earlier fair value of CA$112.25 leaned heavily on future earnings and cash flow assumptions. A different lens comes from where Premium Brands Holdings trades today on P/E. At roughly 125.1x earnings, the stock sits well above a fair ratio of 60x, the North American Food industry at 18.6x, and a 22.2x peer average. That gap points to meaningful valuation risk if the optimistic growth story does not play out as expected. This raises the question: which set of assumptions do you place more weight on?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around Premium Brands Holdings feels conflicted, that is exactly the point. Step in now and stress test the story against the 3 key rewards and 5 important warning signs.
Looking for more investment ideas beyond Premium Brands Holdings?
Consider looking at multiple tickers and comparing several clear opportunities side by side using a consistent framework.
- Spot potential value resets early by reviewing the 3 high quality undervalued stocks that combine strong fundamentals with room for sentiment to catch up.
- Anchor your portfolio with reliability by filtering for companies in the list of solid balance sheet and fundamentals (7 results) that can better handle tougher conditions.
- Get ahead of the crowd by scanning the 9 high quality undiscovered gems that strong fundamentals already support before they are widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com