


- Taisei Corporation announced that, together with TIER IV and Taisei Rotec, it has been selected by Japan's Ministry of Land, Infrastructure, Transport and Tourism for a Fiscal Year 2026 Autoflow Road demonstration that will test multi-vehicle autonomous logistics operations in dedicated lanes and tunnel environments using three experimental unmanned vehicles.
- The project places Taisei's T-Localizer self-localization support technology and simplified roadside infrastructure design at the center of a government-backed effort to define how vehicle autonomy and road hardware should work together in future logistics corridors, with direct implications for capital intensity and long-term operating costs in this field.
- We will now look at how Taisei's role in validating Autoflow Road logistics lanes could influence the broader investment narrative around the company.
What Is Taisei's Investment Narrative?
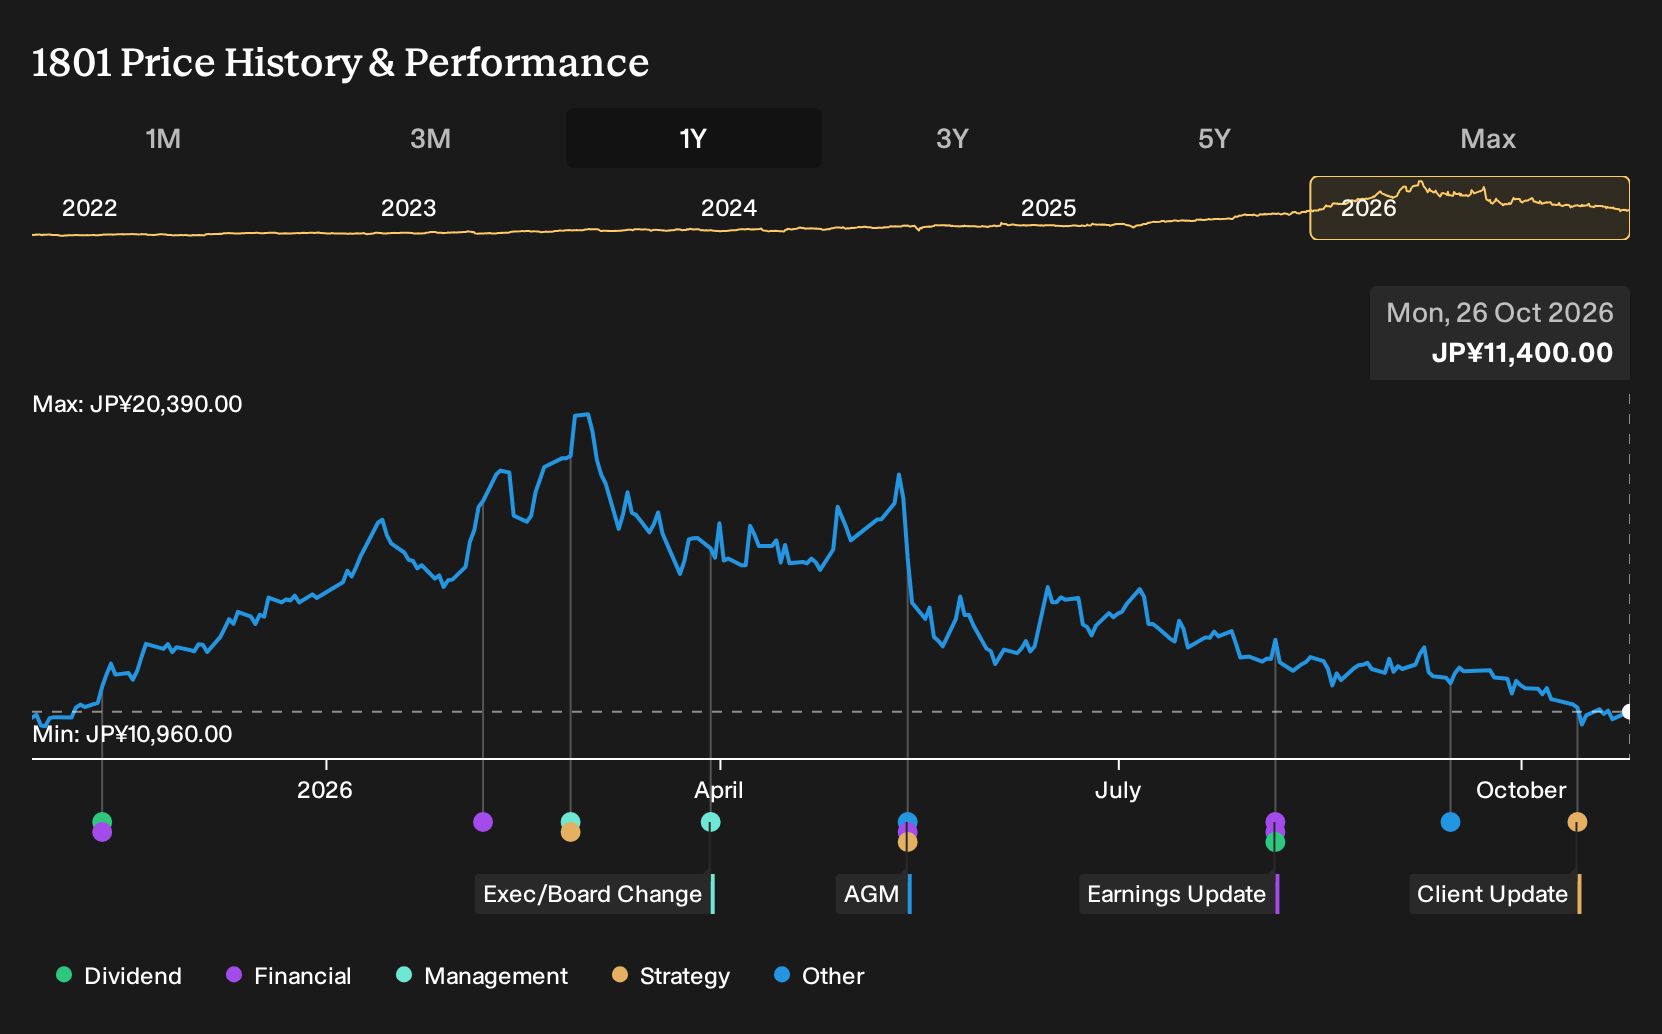
To own Taisei, you need to believe a mature construction and development group can keep translating a broad project base into steady earnings and cash, rather than chasing headline growth. The share price has fallen 25.5% year to date while earnings have grown 31.9% over the past year, with revenue growth at 4.9%. That mix, along with a P/E of 10.8x that screens below an estimated fair multiple of 18x and a 3.33% dividend, points to a story that leans on execution discipline more than big expansion.
The Autoflow Road project fits that story as an operational experiment, not yet a financial needle mover. It reinforces Taisei as a technical partner on complex infrastructure where T-Localizer and tunnel logistics can matter for future tenders, but the near term drivers still look like construction margins, one off items in earnings quality, and capital demands across civil works and development. With 1 year returns lagging both the Japanese market and construction sector, the key question is whether current profitability and cash flow can justify reinvestment and shareholder payouts without stretching the balance sheet.
Yet there is a pressure point in Taisei's recent numbers and governance profile that could change that balance if ...
There's only one way to know the right time to buy, sell or hold Taisei. Head to Simply Wall St's company report for the latest analysis of Taisei's Fair Value.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Taisei research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Taisei. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Taisei's overall financial health at a glance.
Looking For More Ideas Beyond Taisei?
Once you have a view on Taisei, it can help to set that against a wider watchlist built around clear themes and risk profiles.
- If you are focused on capital preservation and smoother returns, consider broadening your research with a group of 22 resilient stocks with low risk scores that score well on resilience metrics.
- Income oriented investors who care about consistency can scan a curated set of 29 dividend fortresses that combine higher yields with more established payout records.
- For those hunting for future leaders before they are widely followed, it may be worth reviewing a cluster of 72 high quality undiscovered gems that already show solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com