


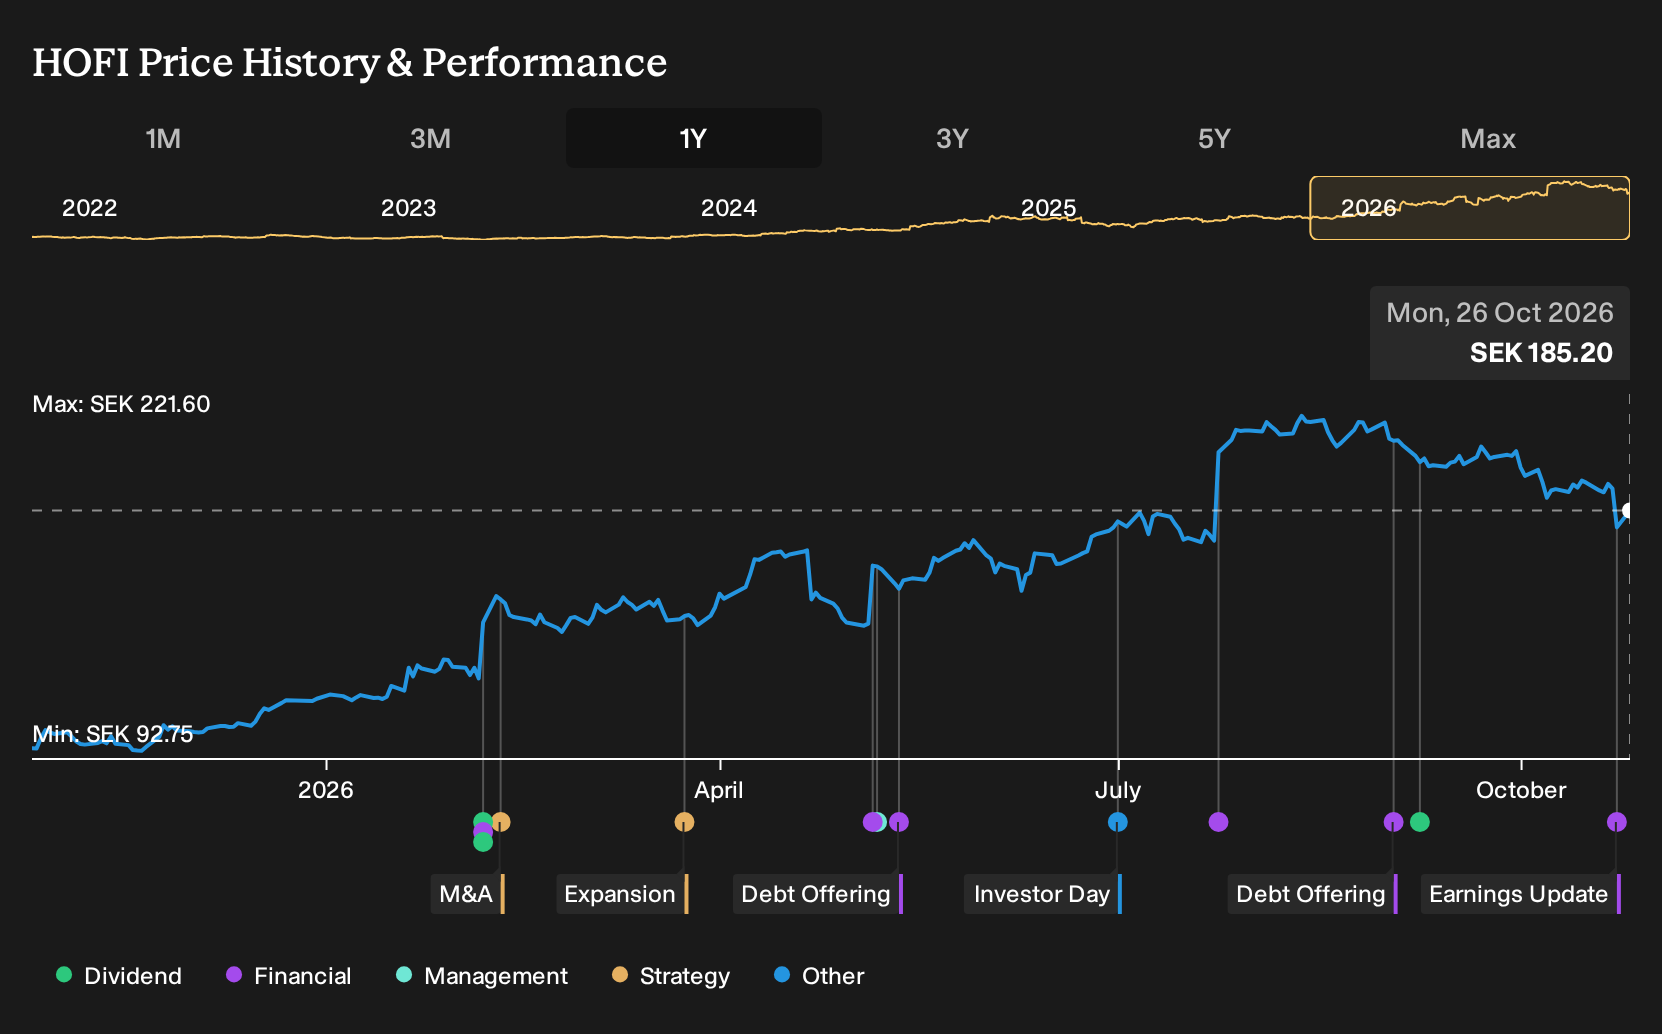
- Hoist Finance reported Q3 2026 net income of SEK 384 million and basic earnings per share of SEK 4.05, with nine-month net income at SEK 1,195 million and basic earnings per share at SEK 12.76, all from continuing operations.
- The earnings release highlights higher return on equity at 21.2% and a strong net profit margin of 28.3%, alongside portfolio risks flagged from recent write-downs and expected credit loss adjustments.
- We will now assess how Hoist Finance's higher net income and return on equity might reshape the investment narrative that investors rely on.
Scan Hoist Finance's latest earnings against a hand picked field of peers by reviewing the list of solid balance sheet and fundamentals (207 results), which combines resilient funding profiles with disciplined risk management.
Hoist Finance Investment Narrative Recap
To own Hoist Finance, an investor needs to believe the firm can keep turning a large European non performing loan pipeline and its funding model into solid returns while controlling credit risk. The latest quarter supports that view on profitability, with SEK 384 million in Q3 net income and a 21.2% return on equity, even after earlier portfolio write downs.
The key near term catalyst is still execution on the existing NPL book and Azzurro funding plan, because realised collections and funding cost will shape earnings quality. The biggest risk remains that further write downs or expected credit loss tweaks reveal weaker portfolio performance, which could quickly pressure margins and challenge that 20% return on equity profile.
The most relevant fresh data point is the Q3 and nine month 2026 earnings release. It shows SEK 1,195 million in net income for the first three quarters and basic earnings per share of SEK 12.76 from continuing operations. That is paired with a 28.3% net profit margin, which suggests the current operating structure is carrying reasonable efficiency.
For catalysts, those figures sit alongside earlier commentary on EU NPL rules, Hoist Finance’s Specialized Debt Restructurer status and the low cost funding model. If regulation continues to steer more loans to market and the firm maintains its margin discipline while avoiding additional material write downs, the existing NPL portfolio and recent deployment could remain the main driver of cash generation and return on equity.
What The Current Hoist Finance Forecasts Assume
Hoist Finance's current analyst narrative leans on a revenue outlook that points to SEK 6.6 billion in sales and SEK 1.7 billion in earnings by 2029. That profile rests on an 11.3% yearly increase in revenue and an earnings uplift of SEK 300 million from SEK 1.4 billion today.
Uncover why Hoist Finance's fair value indicates an 11% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between SEK 205 and about SEK 246 per share, showing a tight band of retail opinion even before the latest Hoist Finance results. When you set that against recent write downs, credit loss adjustments and tougher NPL competition, you see why investor views can diverge sharply, so it pays to compare several community perspectives before forming your own stance.
Explore 2 other Hoist Finance fair value estimates, including one that suggests it could be worth just SEK 205.00.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Hoist Finance research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Hoist Finance. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hoist Finance's overall financial health at a glance.
Looking For More Hoist Finance Style Ideas?
If Hoist Finance has sharpened your focus on balance sheets, cash generation and risk, broaden that lens across the market with the Simply Wall St Screener. Line up other businesses against the same standards you are using here and see which ones truly earn a spot on your watchlist.
- For investors hunting for mispriced quality, start with companies that combine strong fundamentals with attractive valuations by reviewing the 195 high quality undervalued stocks.
- If capital preservation sits high on your priority list, filter for businesses with steadier profiles using the 223 resilient stocks with low risk scores.
- When you want to widen the net and look beyond the usual tickers, scan a 610 high quality undiscovered gems that may not yet be on most radars but still show solid underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com