


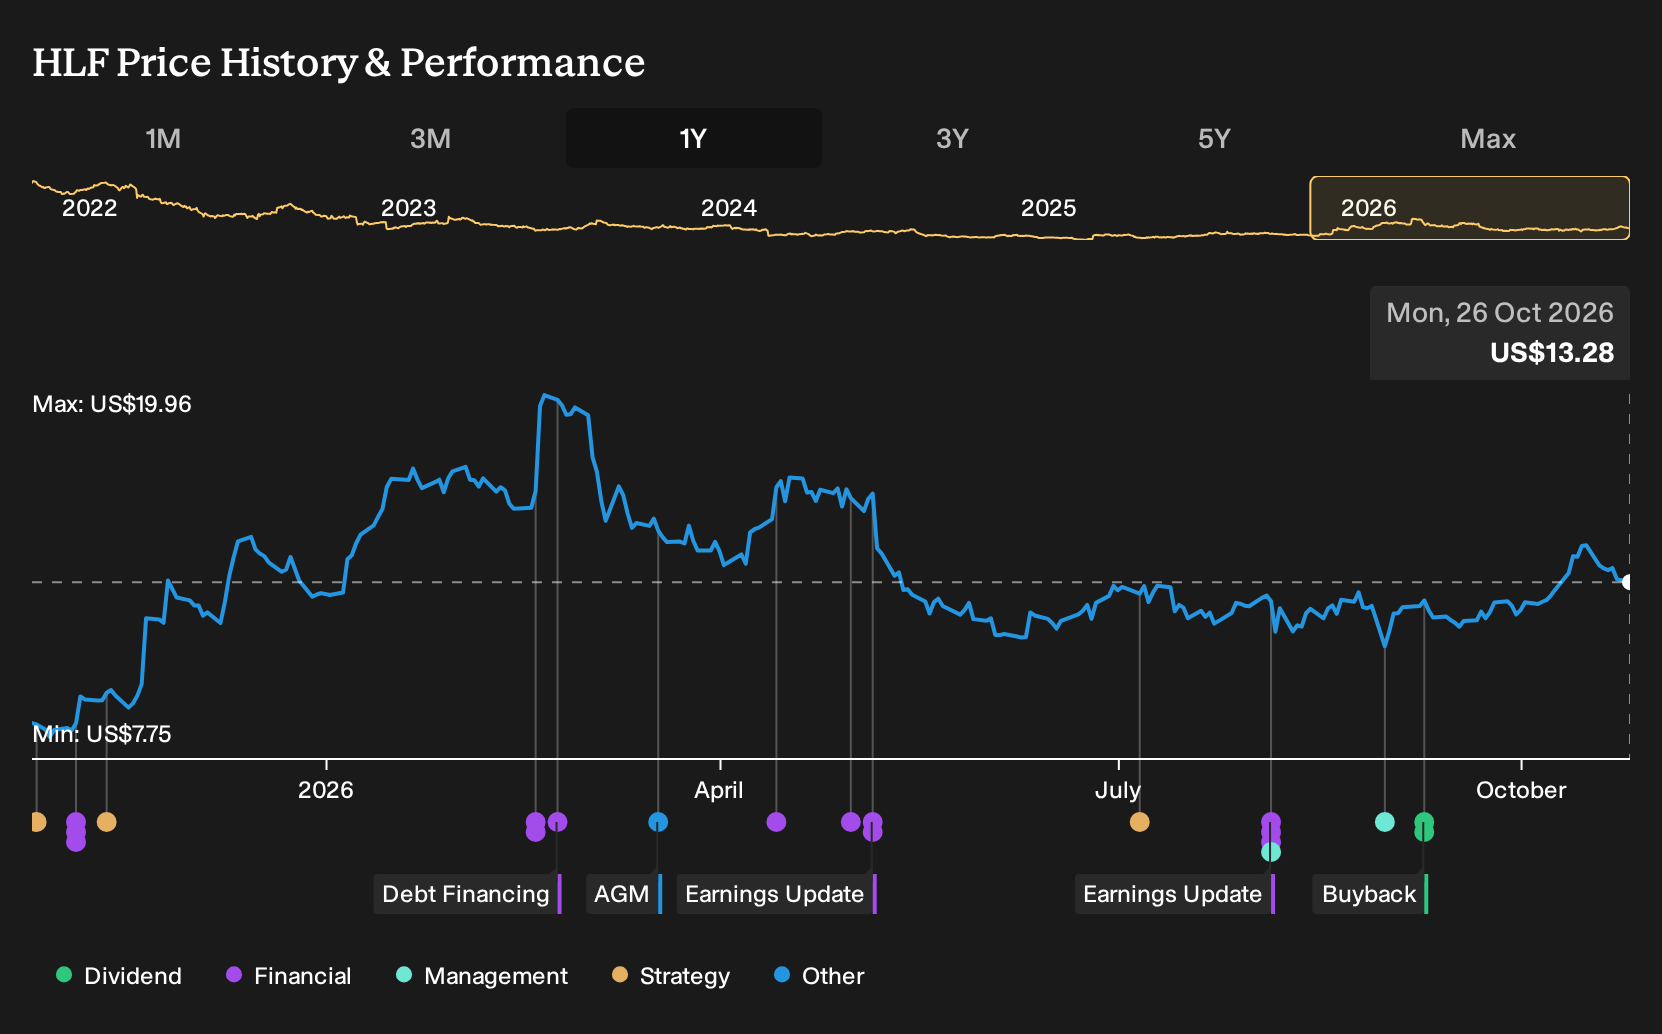
If Herbalife was just sitting on a watchlist rather than in your account over the past year, the move in the share price may feel like an opportunity that slipped away. Investors who held Herbalife over the past year are up 62.0%, including dividends. That jump invites a simple question. Back on 26 October 2025, could the tension between mounting global MLM regulation and management’s push into personalized wellness have been enough to flag this potential?
If the move has made Herbalife harder to judge, start where the gap is still open and scan 29 high quality undervalued stocks.
The Argument Herbalife Investors Were Really Weighing
The shares cost US$8.34 at the start of the period, and Herbalife sat between two very different stories about what came next.
The first narrative set a Fair Value of US$9, a rough guide to what the projections implied, built on the idea that global MLM and supplement regulation would keep tightening while Herbalife tried to pivot toward personalized wellness and better distributor tools.
The opposing case put Fair Value at US$7 and treated rising investigations, pressure on processed supplements, distributor strain, and high debt as risks that could restrict market access and keep margins under pressure.
What The Herbalife Results Put To The Test
Herbalife’s Q2 2026 report gave the bullish story fresh support on revenue, with sales at US$1,326.8m compared with US$1,259.1m in Q2 2025, following earlier guidance upgrades and a US$1.45b refinancing that lowered interest costs. Profit told a different story. Net income moved from a US$49.3m gain to a US$26.3m loss and net margin fell from 3.9% to 2.0%, so the evidence cut both ways.
The whole episode turned on one assumption: that higher sales and new wellness moves would translate into healthier earnings. When you assess another consumer stock, line that claim up against later filings by tracking revenue beside net income and margin, not just the top line on its own.
What Herbalife’s Price Already Bakes In
Today Herbalife trades at US$13.28, and the selected Narrative’s Fair Value sits below that quote. The gap reflects a view that current guidance, balance sheet plans and cash generation already price in a smooth shift toward personalized, tech enabled nutrition and heavier exposure to India and Latin America.
For that to hold, you would need to believe Herbalife can push these programs through while tax, ERP spending and leadership turnover do not blunt margin rebuild or cash generation. The practical question for a buyer is whether execution stays tight enough for earnings quality to match what the present valuation implies.
"The primary requirement for success is that Herbalife executes its personalized, data enabled nutrition and technology programs while managing emerging market mix shifts, India GST headwinds, and leadership transitions without eroding margins or cash generation."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Go Straight To The Source
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 32% below our estimate - turn shorter subsea tieback cycles into higher margin services revenue streams.
- Company 2 - 37% below our estimate - tackle complex failure, safety and regulatory challenges in opaque hardware and AI systems.
- Company 3 - 22% below our estimate - embed AI copilots and developer tools into established cloud and security software workflows.
Three companies from the same screener. Open every one of the 24 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com