


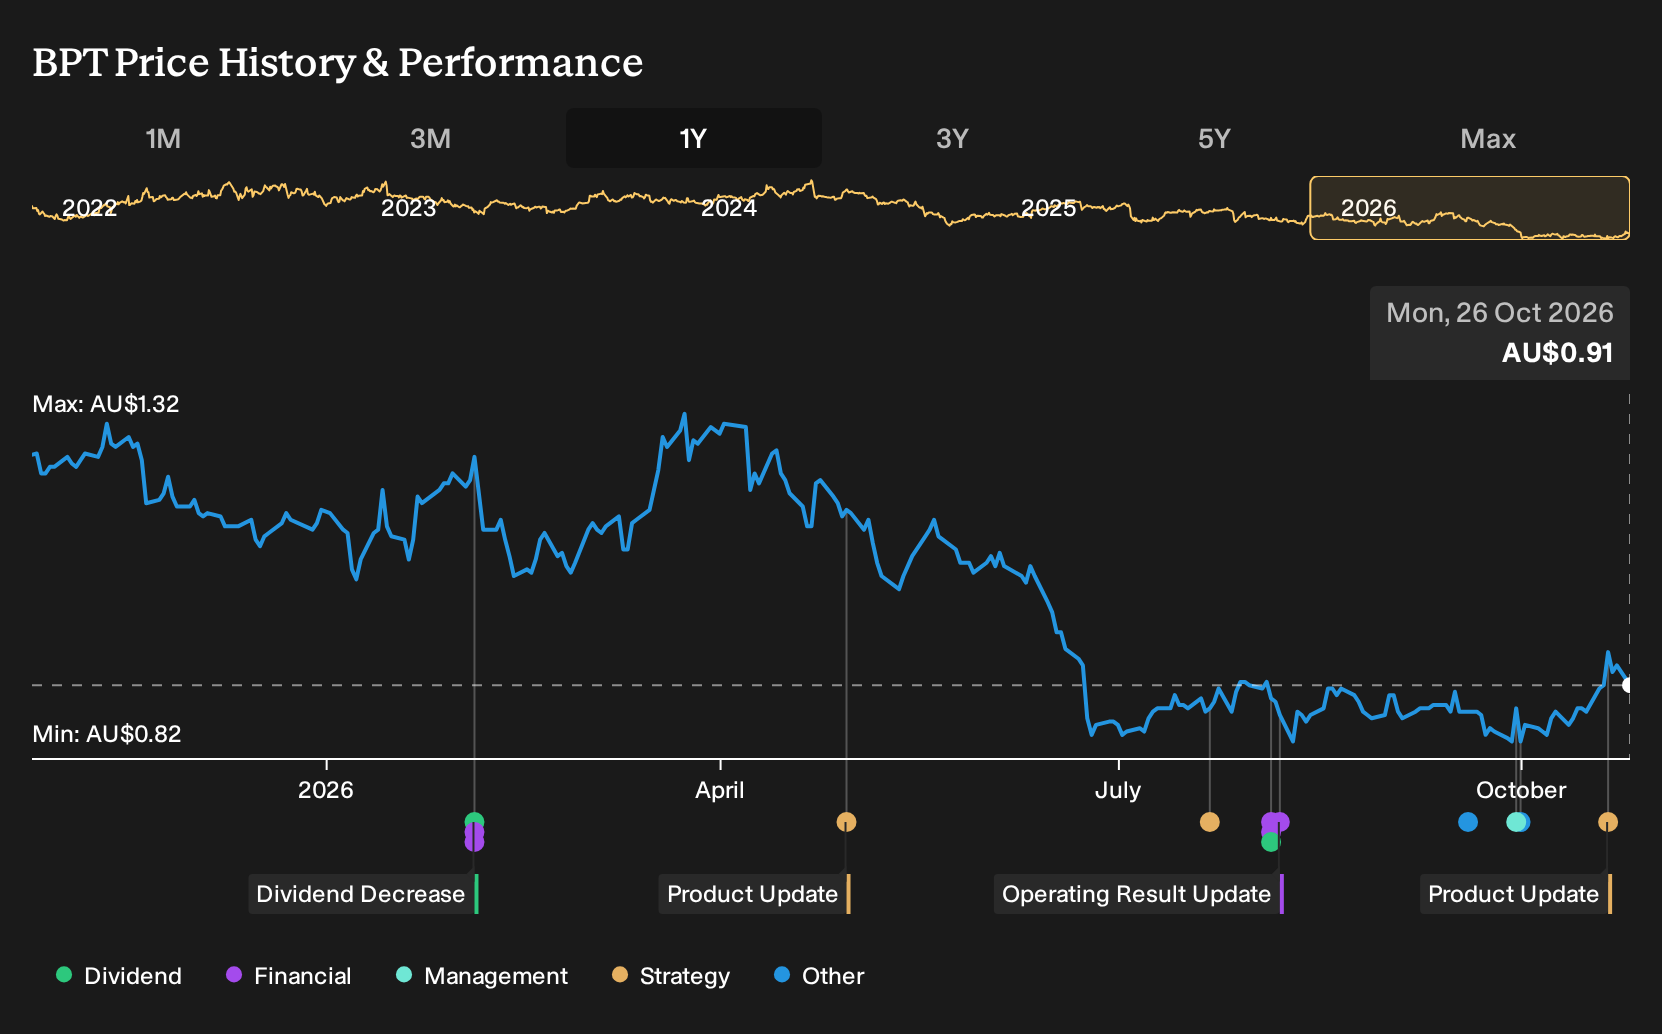
If you only glanced at the headlines on Beach Energy over the year, strong quarterly revenue, record production updates, and big gas project deals might have sounded encouraging. Holding Beach Energy over the past year would have meant a 25.4% loss, including dividends. If you had been weighing up a purchase in October 2025, how much of that eventual hit was hinted at in the reserve worries, project execution questions, and dividend cut already on record?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The move put Beach Energy in the middle of this trade. Scan 16 nuclear energy infrastructure stocks for other companies exposed to it.
The Two Beach Energy Stories Investors Had To Weigh
The shares cost A$1.25 at the start of the period, and anyone looking at Beach Energy then had to pick between two very different stories.
On the optimistic side, the bull Narrative put Fair Value at A$2.03. This view was built on the idea that Waitsia and LNG agreements would support 4.5% annual revenue growth and lift profit margins to 36.5%.
The bear Narrative argued for a Fair Value of A$0.95. It focused on declining 2P reserve life and an assumption that revenue would fall 12.7% a year even if margins rose to 29.9%.
What The Beach Energy Results Actually Tested
Beach Energy cut its interim dividend and reported a non cash impairment, which backed the cautious worries about capital intensity and reserve quality. The later H2 2026 figures then showed revenue down from A$1,062.4m to A$881.2m, while net income swung from a A$266.1m loss to a A$131.2m profit and margin moved from -25.0% to 14.9%. The evidence cut both ways.
The key assumption here was future cash generation from Waitsia and gas projects. For any other producer, check whether revenue and net margin trends in later reports line up with the stated project objectives before relying on the growth narrative.
What You Are Paying For In Beach Energy Today
Beach Energy now trades at A$0.91, after a 25.4% loss over the past year. The selected Narrative sees Fair Value above that level, based on cost discipline, reserve work and a gas focused portfolio rather than new project optionality.
On that view, a buyer today would be assuming Beach Energy turns lower operating costs and released capital into consistently stronger free cash flow backed by ongoing reserve replacement.
"Bullish analysts expect Beach Energy to use its low operating costs, disciplined sustaining capex, and growing gas and LNG platform to generate stronger and more durable free cash flow over time. The main requirement for this scenario is that Beach Energy converts its cost discipline and capital-light portfolio reshaping into sustained reserve replacement while managing domestic gas policy and pricing risk."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Beyond Beach Energy’s Gas Story
Beach Energy asks you to judge project execution and future cash power. The next step is considering who is building larger LNG capacity beside it.
Another producer is developing major export projects and cutting overheads. Its focus is shifting from heavy construction towards leaner operations and steadier cash generation.
Both businesses rely on long life gas infrastructure instead of short term wins. Where Beach Energy leans on reserves and costs, this peer leans on scale and delivery.
If that build converts into durable cash flows, this larger exporter’s role could look very different from today.
That argument has a Narrative and a number behind it. → See the company one Narrative values 29% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com