


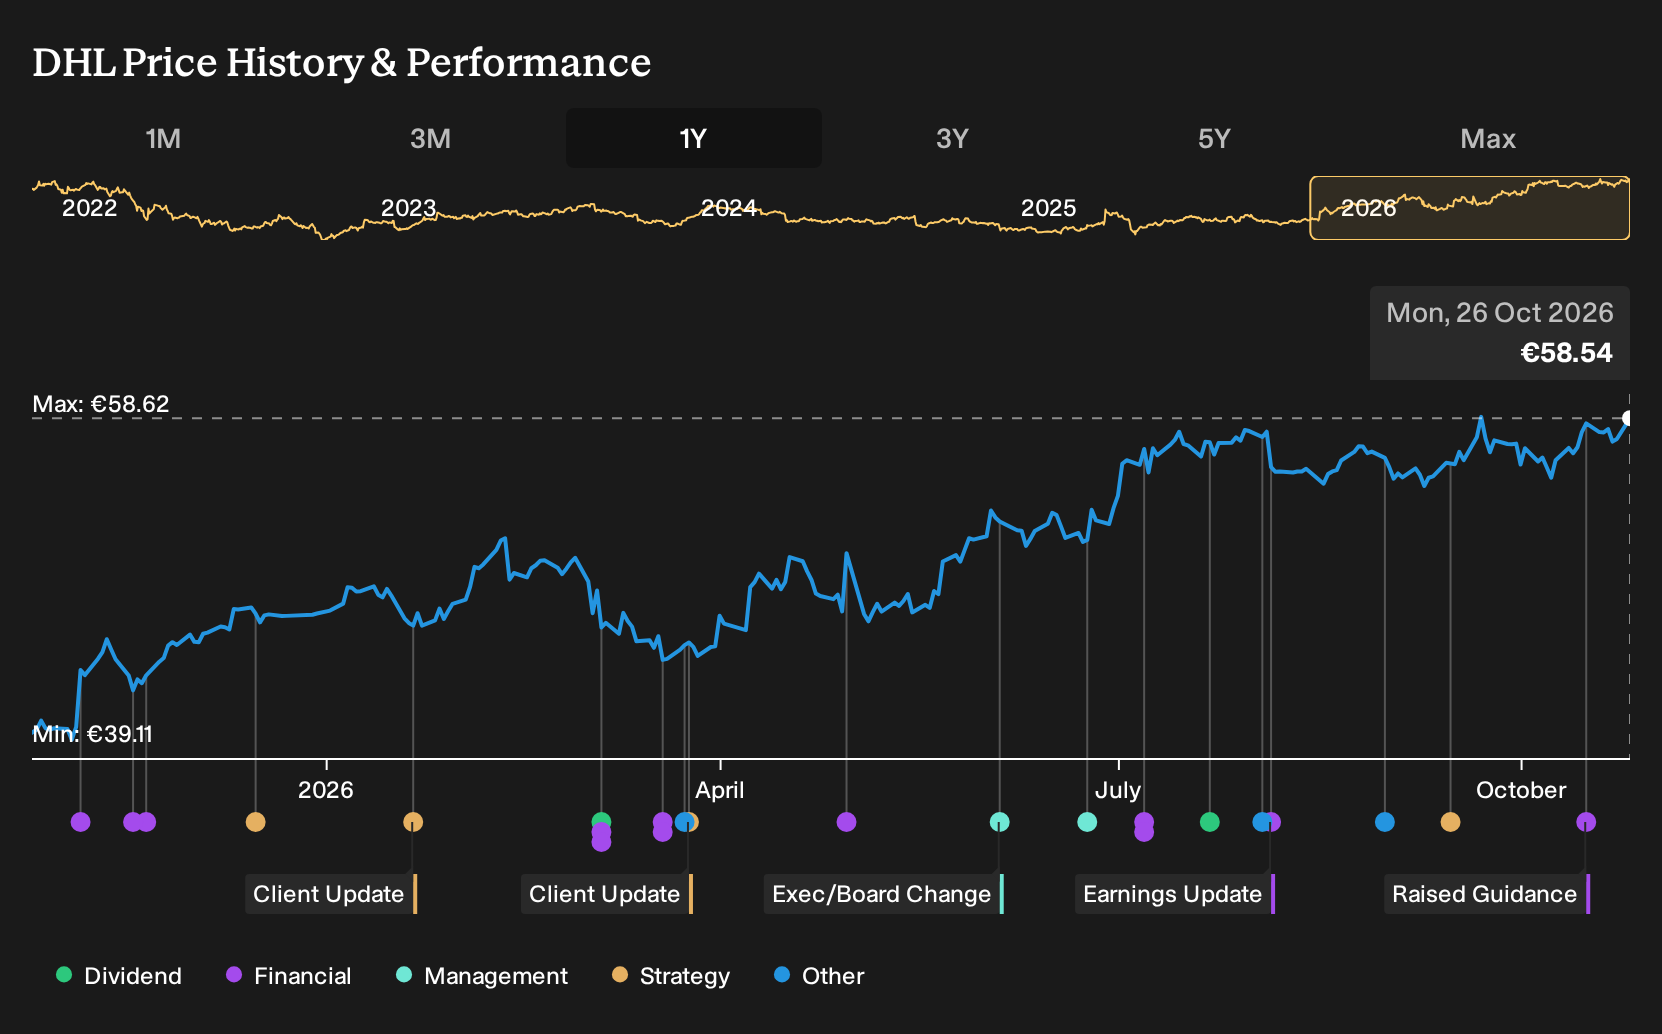
- DHL raised its full year 2026 EBIT guidance, now expecting Group EBIT to exceed €7.0b, with DHL divisions targeted at more than €6.4b while Post & Parcel Germany and Group Functions guidance remain unchanged.
- The uplift in guidance leans heavily on earnings momentum in the Express division and expectations for a strong Q4 seasonal peak. This highlights where DHL currently sees the healthiest demand and pricing power in its portfolio.
- The next focus will be on how DHL's higher full year EBIT outlook could influence the existing investment narrative around margin resilience.
DHL Investment Narrative Recap
To own DHL, you need to buy into a logistics group that relies on Express, heavier B2B shipments and cost programs to keep earnings quality intact while trade remains supportive. The raised 2026 EBIT guidance points to solid operational traction in those areas. The key near term catalyst is how Express handles the upcoming peak season and whether that momentum extends across heavier freight and eCommerce volumes.
The biggest current risk sits on the regulatory and macro side. Tighter de minimis rules and any cooling in goods trade could chip away at shipment counts and blunt operating leverage just as DHL leans harder into higher EBIT targets. If trade flows soften or customs rules tighten further, the new guidance could quickly look demanding rather than conservative.
There have been no major fresh announcements beyond the guidance change that directly reframe the DHL story. The raised EBIT target therefore becomes the reference point for how you think about near term execution on existing priorities. That means watching Express volumes, yield mix in B2B heavyweight and how fast Fit for Growth cost measures drop to the bottom line.
Put differently, the upgraded outlook sharpens focus on whether existing catalysts, such as automation in eCommerce and the push into high value freight corridors, can offset live risks around customs changes and any slowdown in DHL focus markets. If goods trade or pricing softens while regulations tighten, the company may need even more cost efficiency to keep EBIT close to the new bar.
DHL Analyst Framework In Focus
DHL's narrative projects €95.9b revenue and €4.6b earnings by 2029. This is based on an assumption of 3.9% yearly revenue growth and an earnings increase of about €0.9b from €3.7b today.
Uncover how DHL's fair value indicates a 4% potential downside to its current price, reflecting a valuation premium that leaves little room for error.
Exploring Other Perspectives
One alternate view leans hard into DHL’s heavier B2B and GT20 corridor exposure as a potential upside catalyst. Those bullish analysts were already pencilling in €101.4b in 2029 revenue and €4.9b in earnings before this guidance lift. That is far more optimistic than consensus, and it shows how sharply opinions can differ. Use this new EBIT outlook as a prompt to compare those competing stories and decide which assumptions feel realistic to you.
Explore 6 other DHL fair value estimates, including one that suggests as much as 43% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your DHL research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for DHL. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DHL's overall financial health at a glance.
Looking for more investment ideas beyond DHL?
Once you have formed a view on DHL, it can help to cross check that thesis against other opportunities that fit your risk tolerance and income or growth goals.
- For income focused investors who still want a quality tilt, scan a set of resilient payers that screen as 224 dividend fortresses and compare their yield, payout habits and balance sheet strength against DHL.
- If capital preservation sits higher on your priority list, weigh DHL against a 223 resilient stocks with low risk scores and see how its business profile stacks up on volatility and financial resilience.
- For those hunting for less crowded ideas, broaden the watchlist with a 610 high quality undiscovered gems and contrast their fundamentals with what you see in DHL today.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com