


Aisin has given long term holders a powerful ride over the past few years, yet the recent pullback raises a simple question for you as an investor: Is the current share price still aligned with what the business is earning, or has the market moved ahead of, or behind, those earnings?
- Over the past 5 years the stock has gained 83.9%, which puts real weight on whether that climb is consistent with the company’s earnings power.
- The group’s role as a major auto components supplier means future earnings are closely tied to how well it can convert vehicle program wins and production volumes into steady margins and cash flow.
- There is a second opinion on Aisin worth weighing. See what analysts think Aisin's shares could be worth.
The issue now is whether Aisin’s recent share price, after this mix of long term gains and shorter term weakness, is properly supported by its earnings profile.
If you want to stress test this same earnings question beyond Aisin, compare it with 16 high quality undervalued stocks to see how other stocks are currently priced against their fundamentals.
Is Aisin a Bargain on Earnings?
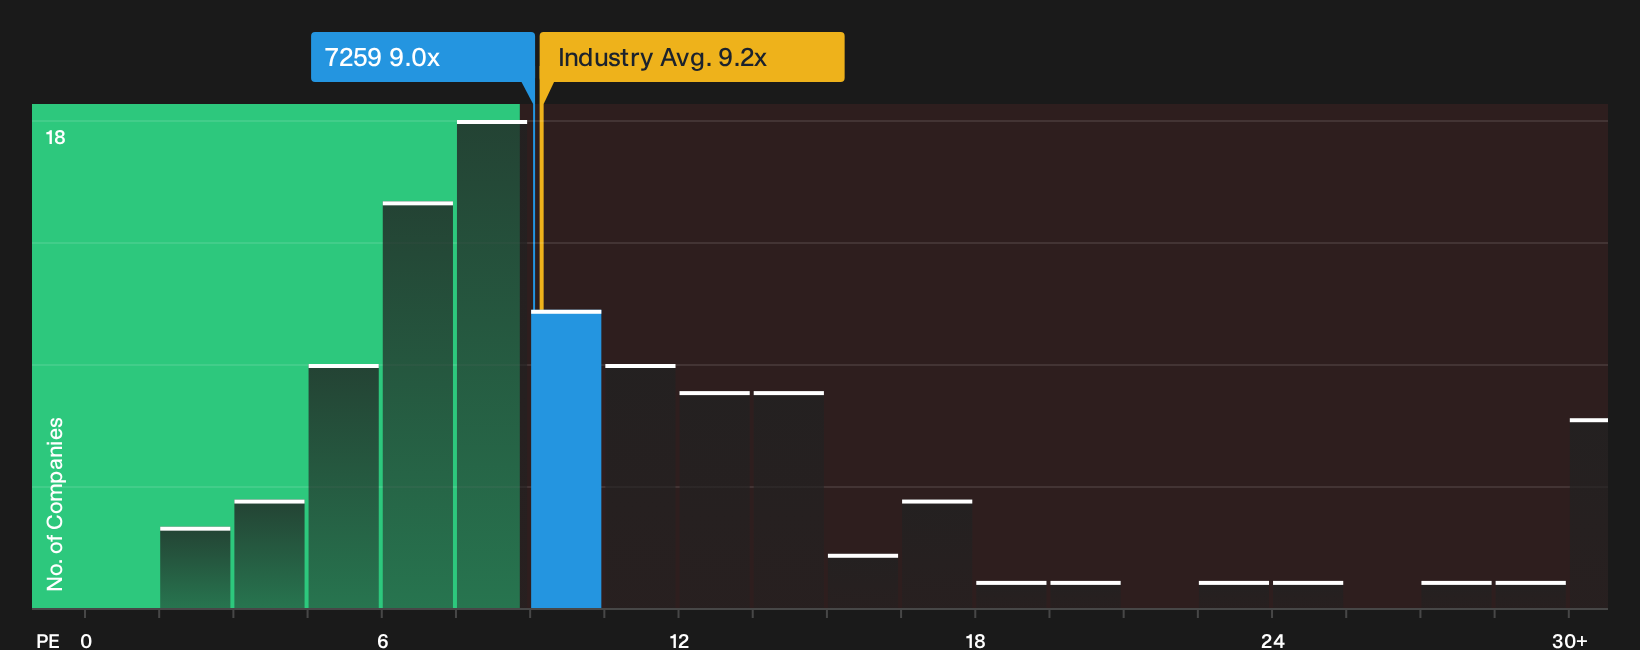
P/E works well for Aisin because earnings remain a central reference point for how the market values large auto component suppliers. On this measure, the stock trades on a P/E of 9.0x, which is slightly below the Auto Components sector average of about 9.2x and far below a broader peer group that sits around 22.5x.
The fair value modelling suggests a higher P/E would be typical for Aisin given its specific mix of profitability, risk and scale. The current 9.0x sits on the cheaper side of that tailored range. That gap implies the market is applying a cautious label to the earnings stream and leaves you judging whether that discount fairly reflects the business risks or leans too heavily on them. Explore the numbers behind Aisin's P/E valuation.
The Aisin Narrative: What Would Justify Today's Price?
Narratives for Aisin pick up where the P/E puzzle leaves off and explain which paths for future growth, profitability and earnings would need to occur for the current price to appear meaningfully higher or lower. Instead of a single output from a ratio or model, these scenarios outline the future that number depends on so you can track how Aisin's actual progress compares with the expectations built into the valuation. They are available on Simply Wall St's Community page.
A written, number driven narrative on Aisin right now gives you a clear record of what you expect for its growth, margins and execution, so you can see in real time where reality matches or challenges those assumptions as new results arrive. It turns a loose impression of the stock into a specific roadmap that can be checked and adjusted as the business data evolves.
Share your own Narrative for Aisin and set out the assumptions behind your valuation.
Before you move on from Aisin, there is one more check worth doing
Price ratios tell you how the market views Aisin right now, but the external estimates for where this business could be a few years out offer a different lens on what that valuation really implies. Explore where analysts expect Aisin to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com